1.Bonds are Safe? 30 Year has Lost 15% Since August and 12% Since October.
VGLT-Long Term Government Bond ETF.
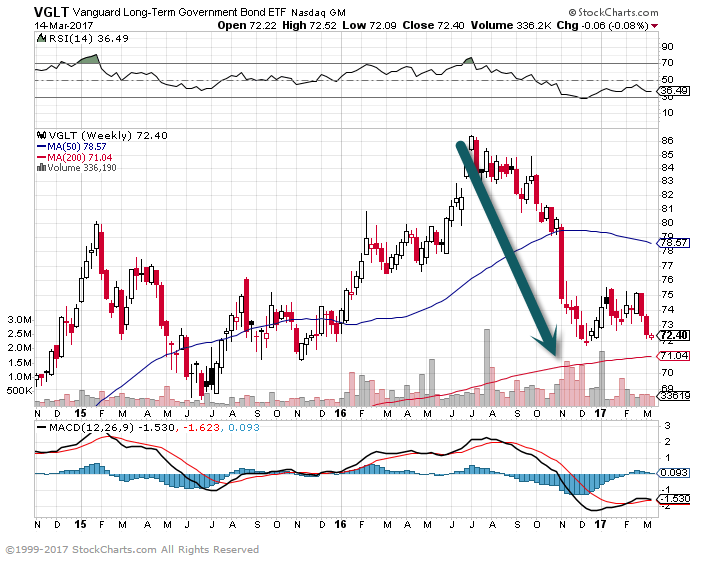
VGLT-Long Term Government Bond ETF.
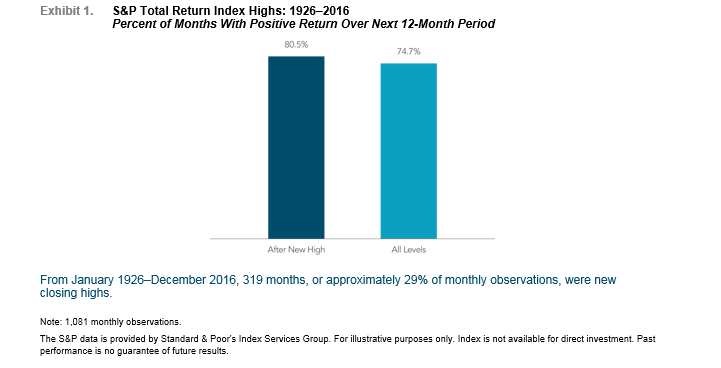
Top 10 will be a little sporadic in near-term due to travel into next week…Thanks


State Street SPDRs Group Does Great Work… Click for More
http://statestreetspdrs.com/1381/files/March_Chart_Pack_2017.pdf
Greetings,
The United States: The futures-implied Fed Funds rate hike probability for this month rose to 94%.
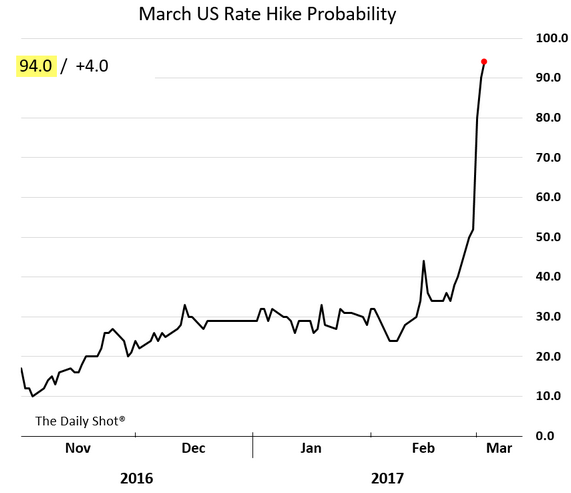
Source: @GregDaco, @WSJ, @JoshZumbrun; Read full article
www.thedailyshot.com
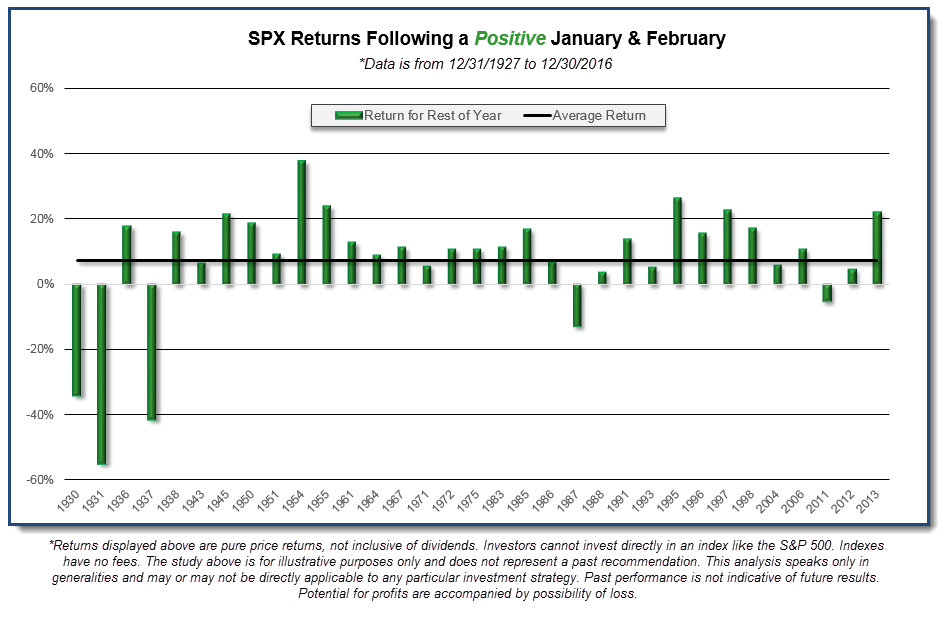
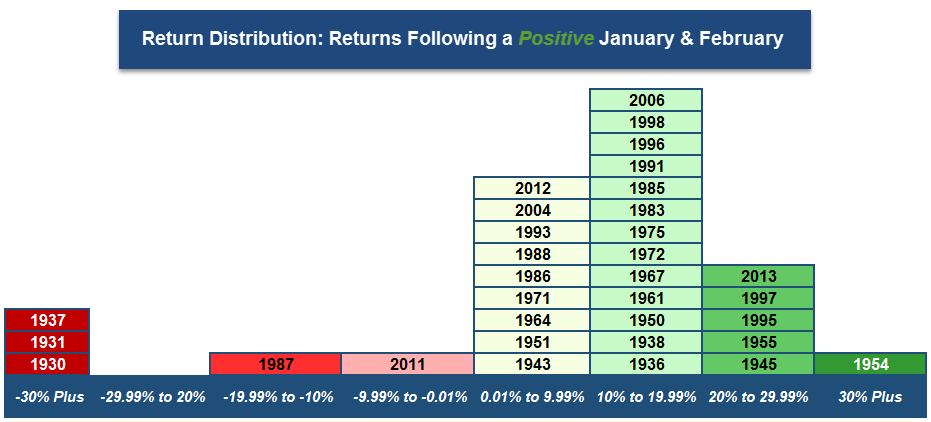
The images below show a bell curve and bar chart of the SPX returns for the remainder of the year (March – December) when both January and February returns were positive. As we can see from both images, the market tends to finish in positive territory for the remainder of the year as well, though there are a few exceptions. Here are some statistics from our findings:
· During the years where January and February were both positive the combined months average return was 7.40% (out of 33 occurrences). In 2017, the SPX was up 5.57% from 12/30/2016 to 2/28/2017.
· The remainder of the year (March – December) the SPX was up an average of 7.37%.
· Out of the 33 occurrences, 28 occurrences were positive (84.85%) and 5 were negative (15.15%).
· Average return for just the 28 positive occurrences was 14.01%.
· Of the five negative occurrences, three of them date back to the 1930’s. The two other negative occurrences were 1987, which saw the SPX fall -13.06% from March thru December (largely due to the October crash), and 2011, when the SPX finished down -5.24% from March to December.
 From Dorsey Wright
https://oxlive.dorseywright.com/research/bigwire/
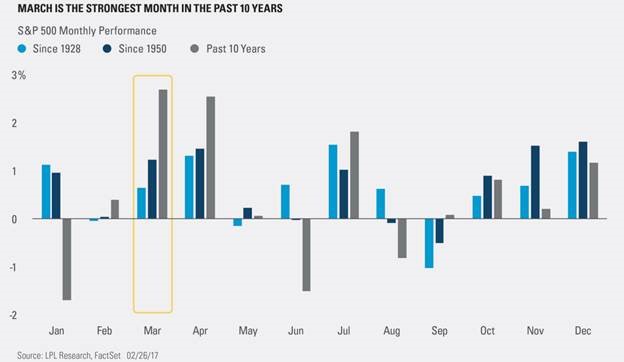
March is known for many things, from spring training, to the NCAA tournament, to spring flowers, to consistent equity gains? That’s right, over the past 10 years, there hasn’t been a month for the S&P 500 with a higher average monthly return than March.
“When the first two months of the year have been higher, March has closed higher 19 of 26 times (73.1%) and has been up an average of 1.4%” – “The S&P 500 is set to close up four consecutive months once February is in the books. When the S&P 500 has been up four or more months heading into March, then March actually has become stronger, as since 1950, it has closed higher 11 of 13 times (84.6%) with an average return of 2.3%.” noted LPL
Thanks to Dave Lutz at Jones for Chart.
Yet, the valuation has been inflated by a collapse in profits for oil companies. Because analysts expect little in the way of earnings over the next year, but a recovery later, the ratio of price to year-ahead earnings for oil stocks is elevated. The energy sector stands at more than 30 times Thomson Reuters IBES’s estimate of operating earnings over the next 12 months, higher than any time from when the sector data started in 1995 up to last year—when it briefly reached an extreme of almost 60 times.
https://www.wsj.com/articles/a-new-way-to-look-at-crazy-stock-valuations-1488212972?tesla=y
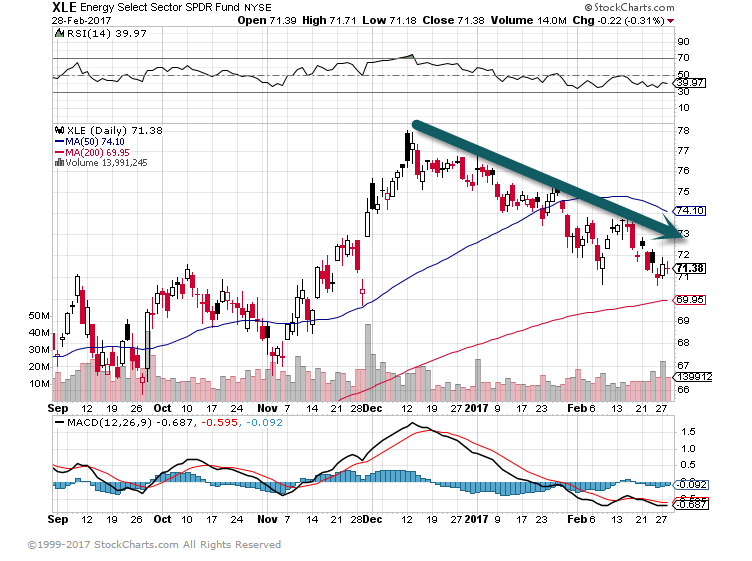
 XLE 7% Off Highs.


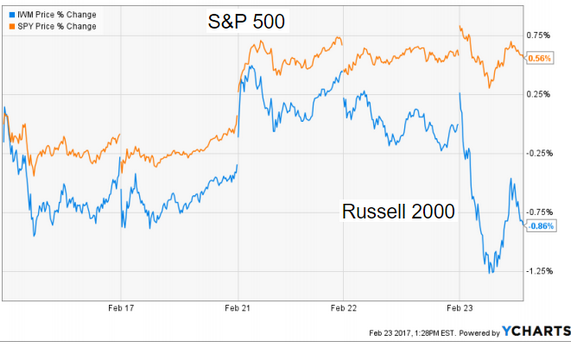
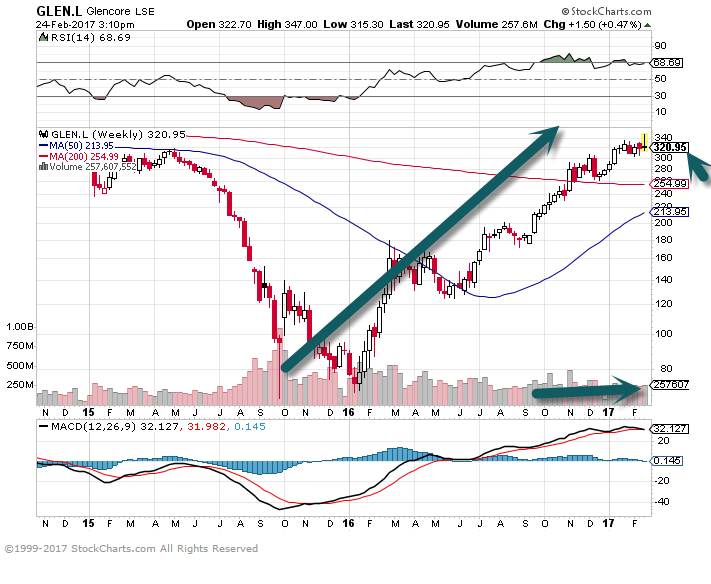
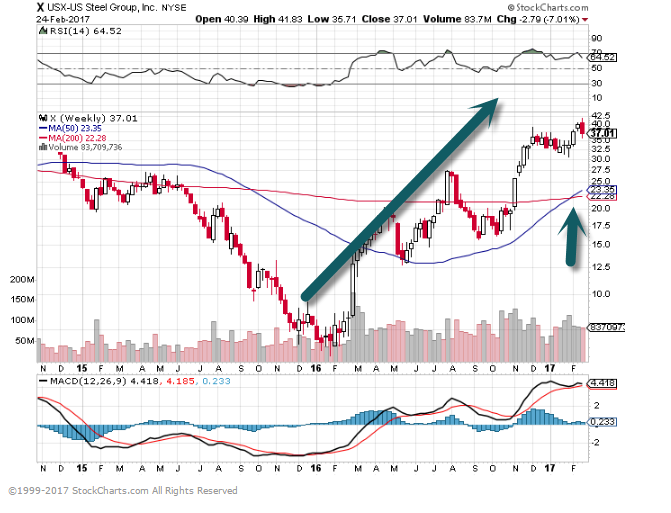
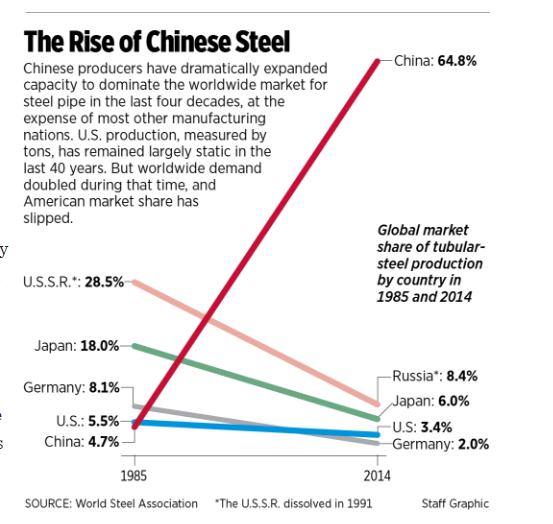
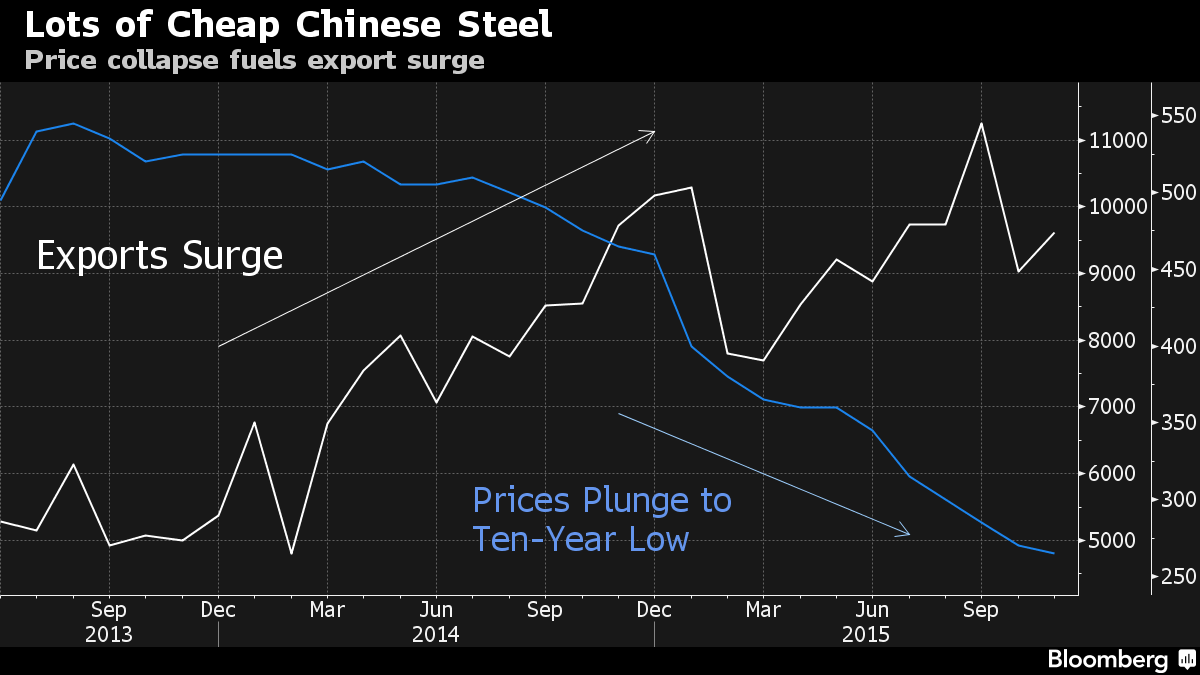
http://www.philly.com/philly/business/American-steel-pipes-Trump-Pennsylvania-Durabond.html
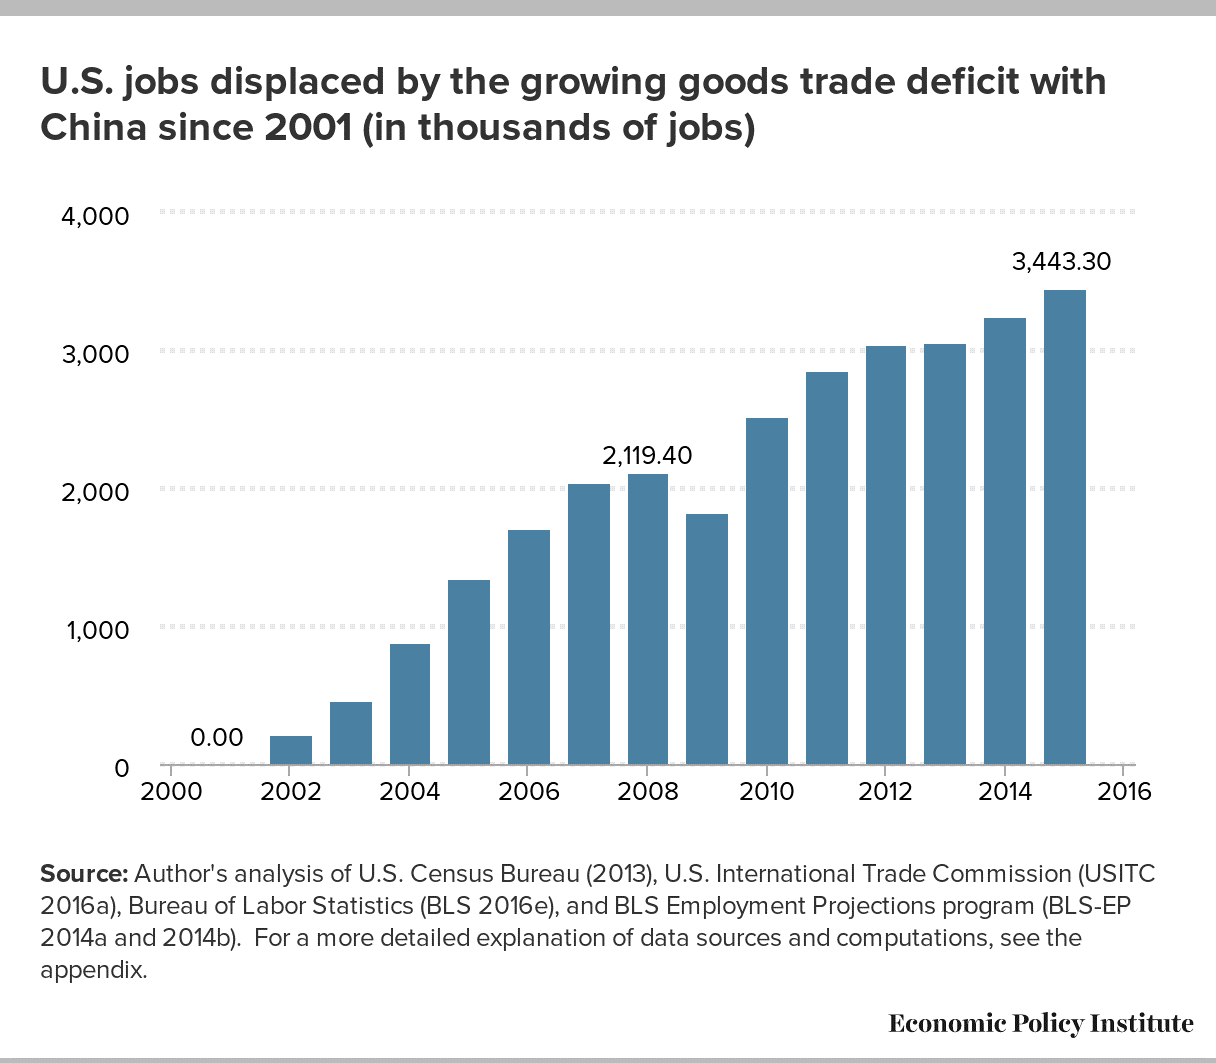
How would you advise President Trump?
We have 23½ million Americans age 25 to 54 who reside outside the confines of the labor force. It is not that they’re unemployed. They by definition have disengaged from the entire economy, and that number has never been that high. The irony is that we have a record level of job openings. There is a skills mismatch.
So we need a WPA-type program, except with education?
Yes—education, training, skills development, apprenticeship programs. We have to find a way to retool these disenfranchised prime working age folks. Enrollment in universities and colleges is going down, and we do not have nearly enough engineers, scientists, and mathematicians. The No. 1 priority should be redressing the single biggest constraint on the economy outside of the fact that we have excessive debt loads.
Read Full Interview.
http://www.barrons.com/articles/david-rosenberg-cautious-on-the-trump-rally-1488000316
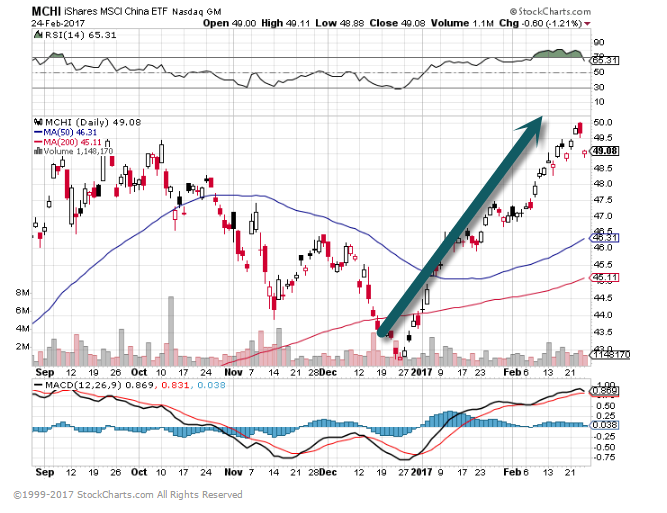
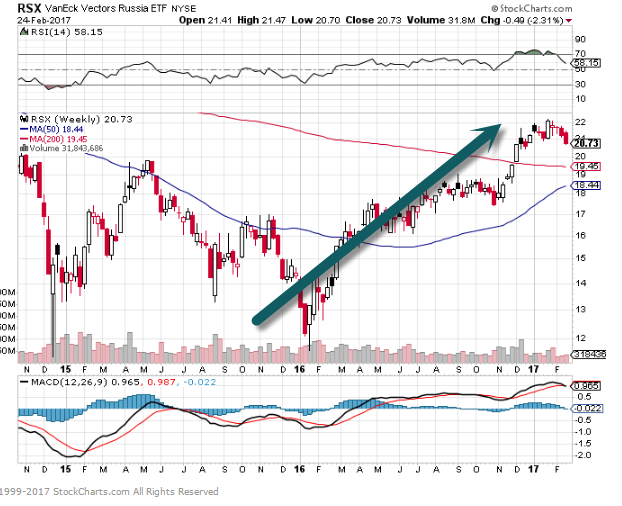
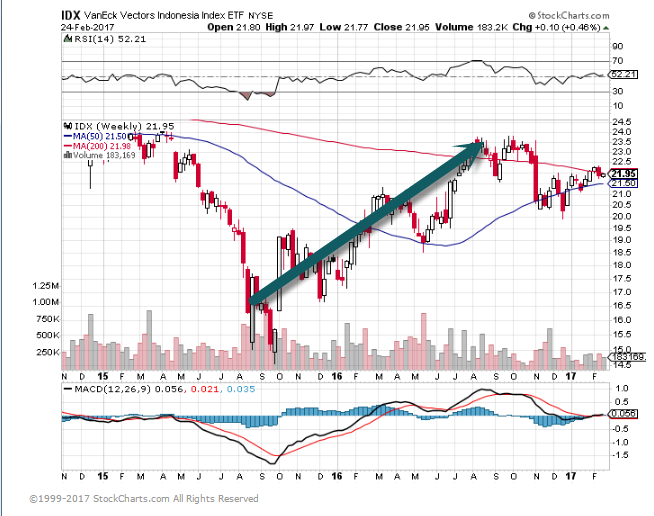
The two would benefit more than other developing economies if the U.S. and China spend heavily on infrastructure projects.
By
As commodity prices stabilize, two developing countries should be winners: Russia and Indonesia.
Among major emerging markets, commodities as a percentage of exports are greatest in Russia, at roughly 70%, followed by Brazil (51%), India (35%), and Indonesia (35%), according to World Trade Organization data provided by Pavilion Global Markets. But India imports half of its commodities and food needs, and the rise in oil prices may weigh on its economy, as will the lingering negative of last fall’s rupee demonetization. And Brazil is still struggling with high interest rates and debt, as it recovers from a deep recession.
But stronger commodity prices should benefit Russia and Indonesia. Driving demand are two factors: The first is China, which could spend close to $800 billion over the next three years on transportation improvements alone. The second is the U.S,, which also is likely to undertake infrastructure projects that will drive commodity consumption.
Exports from emerging markets have risen over the past six months, helping to boost foreign currency reserves in half of them, says François Boutin-Dufresne, a global strategist at Pavilion, an independent research and brokerage firm in Montreal. He’s bullish on buying the MSCI Emerging Markets Index over the next three to six months. The iShares MSCI Emerging Markets exchange-traded fund (ticker: EEM) is up 11% this year.
http://www.barrons.com/articles/commodity-rebound-would-be-boon-for-russia-indonesia-1488000350
Feb 24, 2017
When it comes to rankings, a “ten” is typically considered as good as it gets. In many sports, a “ten” is considered the best possible score. In 1976, Nadia Comaneci was the first gymnast to ever score a perfect ten when she was flawless on the uneven bars. Then, in 1979, Bo Derek also taught us that a ten was perfect.
In 1984, the “perfect ten” was one-upped when ‘guitarist’ Nigel Tufnel from Spinal Tap introduced the world to amps that had a volume control that topped out at eleven. His reasoning was that every once in awhile there are those times where you have the volume up to ten and everything is going great but there is nowhere else to go from there. To solve the problem Tufnel tells the interviewer (played by Rob Reiner) that his amps go to eleven for those times when the band needs the “extra push off the cliff.”
This week, the DJIA was more than perfect, and like the amps from Spinal Tap, it pulled an eleven. And it did so in dramatic fashion, as the only time that the DJIA traded in positive territory was in the final seconds of the trading day. So where do we go from here?
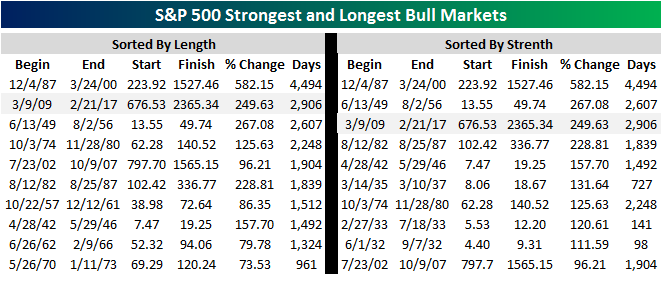
Along with the DJIA this week, all of the major averages hit new bull market and all-time highs, as one of the most unloved bull markets of all time continues to chug along. For the S&P 500, the current bull ranks as the second longest and third strongest of all time. While it will be some time before the current bull makes a run for the top spot in either category, in strength terms, a gain of 5% from here will put the current bull into second all-time as well.
https://www.bespokepremium.com/think-big-blog/
After reading Alan Greenspan’s book, I was shocked how much the FED monitored the financial press, but I am even more surprised that they are watching the VIX.
The Federal Reserve is worried that the stock market might be showing signs of complacency.
The central bank’s most recent communication — the Fed minutes for the January/February meeting — released on January 22 shows that members are split on whether President Trump’s agenda will spur economic growth.
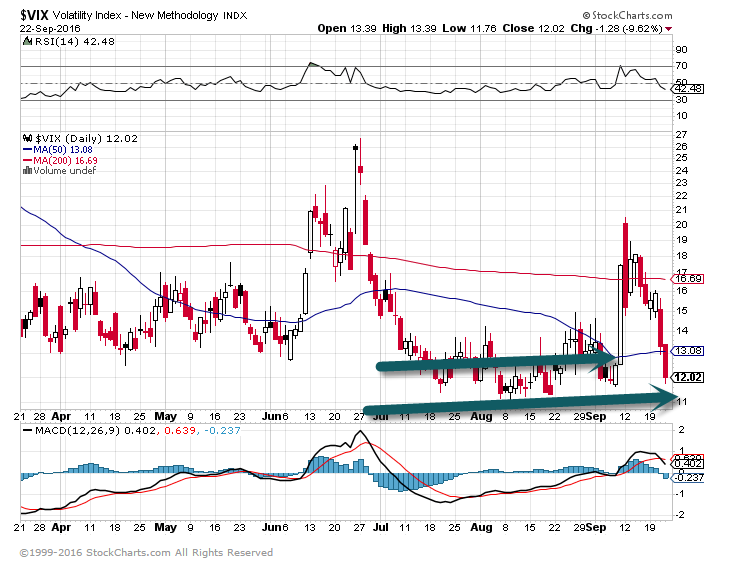
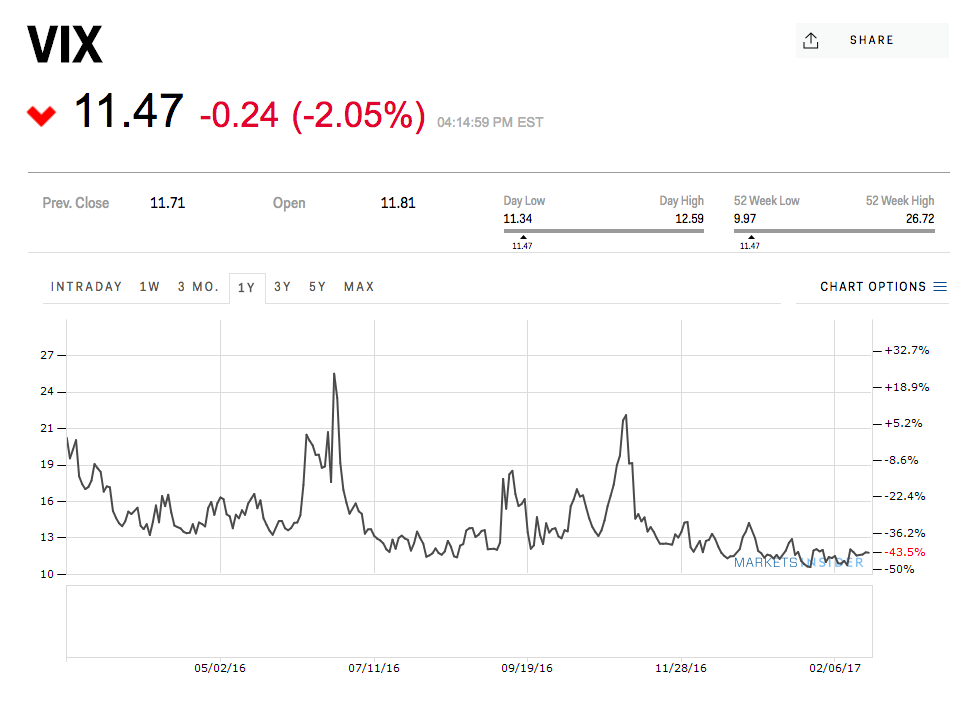
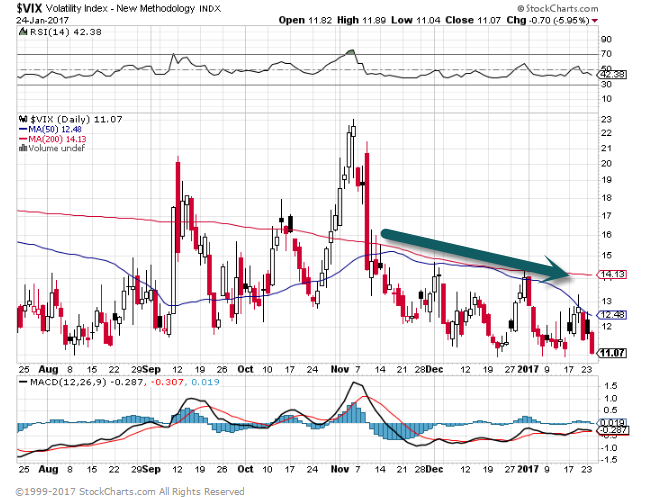
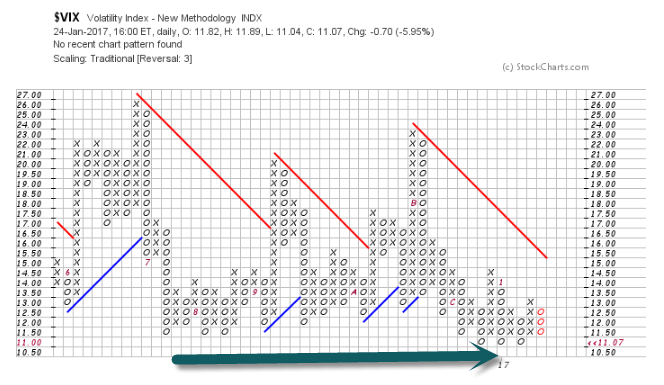
That uncertainty doesn’t seem to be showing up in the stock market, however. The Chicago Board Options Exchange volatility index, which gauges investor anxiety (technically, implied expectations for volatility in the stock market) and is widely known as the VIX index, has been trending down.
The Fed minutes said: “They also expressed concern that the low level of implied volatility in equity markets appeared inconsistent with the considerable uncertainty attending the outlook for such policy initiatives.”
What is implied volatility, and why is it so low?
The VIX is commonly read as a gauge of market fearfulness, and measures the market’s expectation of volatility implicit in the price of options on the Standard & Poor’s 500.
One way to think of it is like the cost of an insurance policy. When the market is expected to be volatile, there are more buyers of insurance, and so the cost of that insurance rises. When the market is relaxed, nobody’s interested in buying insurance against a wild swing, so the protection offered by options is inexpensive.
Lately, the VIX has barely been moving, only breaking 20 on a handful of occasions, and generally trending below 13.
After Job Skill
The billionaire investor predicts one crushing reality of automation.
When Mark Cuban speaks, people listen. The billionaire investor and Shark Tank personality has a slew of wildly successful businesses under his belt. Whether he’s commenting on the recent Time Warner and AT&T merger, recommending books for entrepreneurs, or sounding off about the 45th president, the internet hangs on Cuban’s every last word.
Now his latest prediction about the future of jobs is picking up steam. In a recent interview with Cory Johnson on Bloomberg TV, Cuban presented an interesting argument against people pursuing so-hot-right-now computer science degrees or attending learn-to-code bootcamps.
“What looks like a great job graduating from college today may be not be a great job graduating from college five years or 10 years from now,” Cuban said.
He predicts the next wave of innovation will be “the automation of automation.” By that, Cuban means software will soon begin writing itself, which will ultimately eliminate those lucrative software development jobs. About writing software, Cuban said: “It’s just math, right?” Humans will no longer be needed.
Though it’s ironic, Cuban believes technology will eventually kill tech jobs themselves. “There are no manufacturing jobs coming back. There are no coal mining jobs coming back,” Cuban said. He thinks software development jobs are next on the chopping block.
The next most in-demand job skill
If Cuban’s prediction does indeed come true, with the need for coders, developers, and engineers eventually evaporating, what sort of workers will be in demand? Those who can make sense of the data that automation is spitting out. No, not data scientists. Cuban believes employers will soon be on the hunt for candidates who excel at creative and critical thinking.
“I personally think there’s going to be a greater demand in 10 years for liberal arts majors than for programming majors and maybe even engineering,” Cuban said. He cited degrees such as English, philosophy, and foreign languages as being the most valuable. “Maybe not now,” Cuban acquiesced. “They’re gonna starve for awhile.” Their day, though, is likely coming, he says.
Cuban went on to voice his support for programs such as AmeriCorps, which engage young people in public service work across the United States. “Having people come in and have a social impact and making it a real job is what we’re gonna need.”
BREAKING DOWN ‘LIBOR’
LIBOR (or ICE LIBOR) is the world’s most widely-used benchmark for short-term interest rates. It serves as the primary indicator for the average rate at which banks that contribute to the determination of LIBOR may obtain short-term loans in the London interbank market. Currently there are 11 to 18 contributor banks for five major currencies (US$, EUR, GBP, JPY, CHF), giving rates for seven different maturities. A total of 35 rates are posted every business day (number of currencies x number of different maturities) with the 3-month U.S. dollar rate being the most common one (usually referred to as the “current LIBOR rate”).
Read more: LIBOR http://www.investopedia.com/terms/l/libor.asp#ixzz4Zb2kAkBE
Follow us: Investopedia on Facebook
https://fred.stlouisfed.org/series/USD3MTD156N
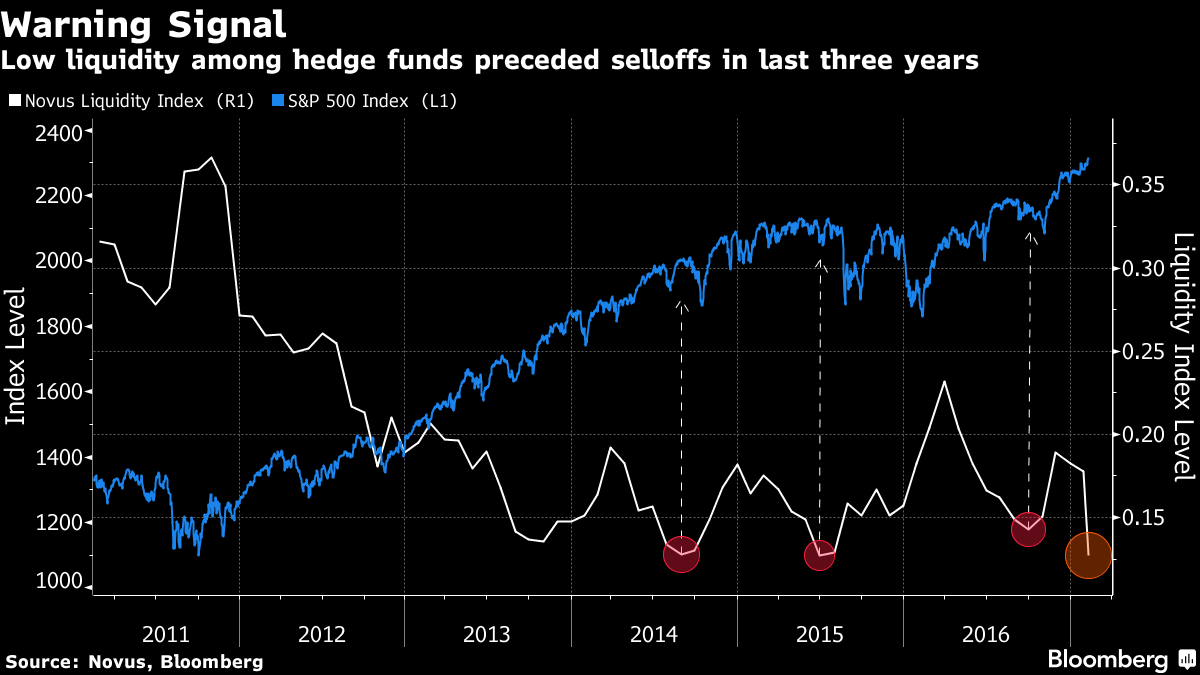
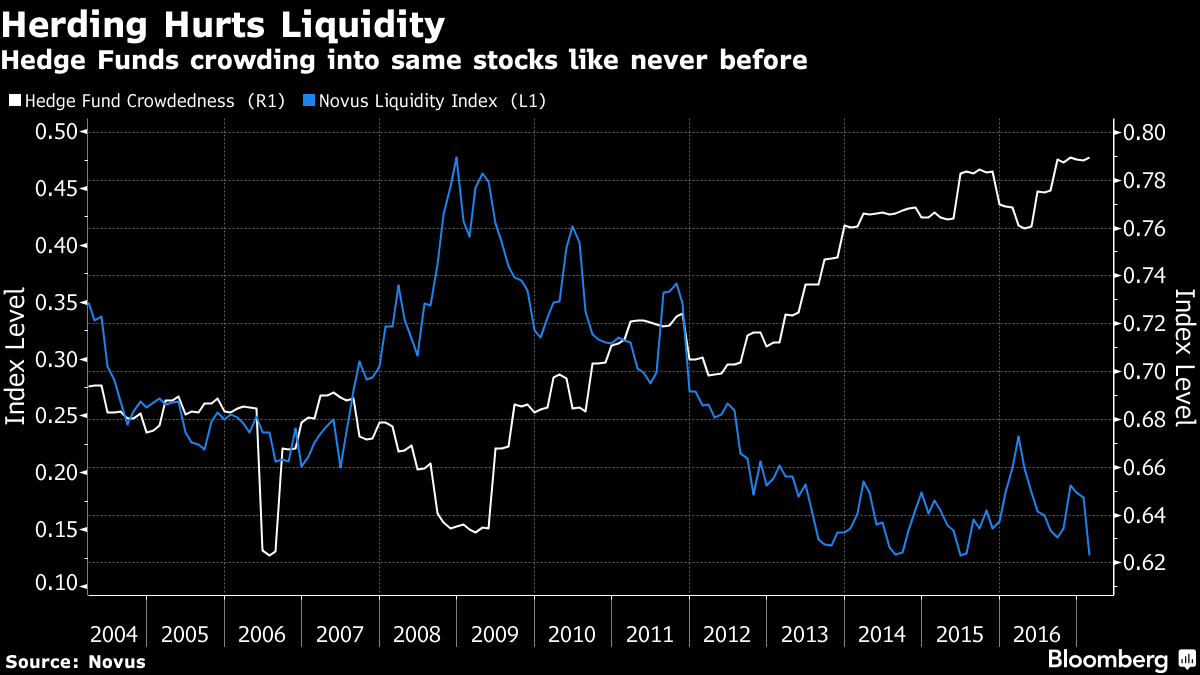
(Bloomberg) — There’s safety in numbers. Until a stampede starts.
That’s the theory underlying a study of hedge fund holdings by Novus Partners Inc., which sought to calculate how easily the market could absorb concerted selling by large money managers. Using an analysis that turns mainly on how much volume is occurring in stocks favored by professional speculators, Novus says liquidity is at an all-time low.
Read Full Article
Found at Abnormal Returns Blog
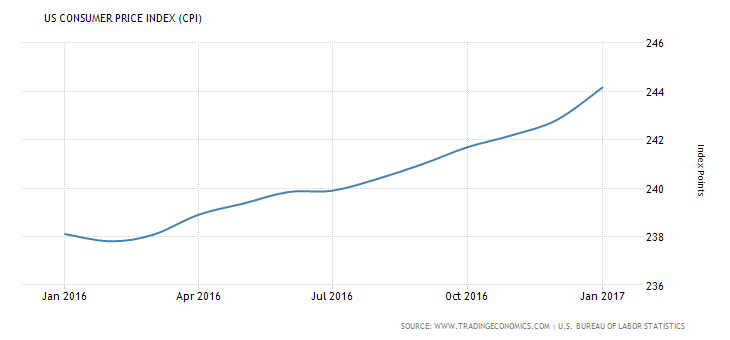
U.S. consumer prices recorded their biggest increase in nearly four years in January as
households paid more for gasoline and other goods, suggesting inflation pressures could be picking up.
The Labor Department said on Wednesday its Consumer Price Index jumped 0.6 percent last month after gaining 0.3 percent in December. January’s increase in the CPI was the largest since February 2013.
In the 12 months through January, the CPI increased 2.5 percent, the biggest year-on-year gain since March 2012.
The CPI rose 2.1 percent in the year to December.
Economists polled by Reuters had forecast the CPI rising 0.3 percent last month and advancing 2.4 percent from a year ago.
Inflation is trending higher as prices for energy goods and other commodities rebound as global demand picks up.
Found on Josh Brown Blog
http://thereformedbroker.com/2017/02/15/cpi-busts-out/
http://www.tradingeconomics.com/united-states/consumer-price-index-cpi
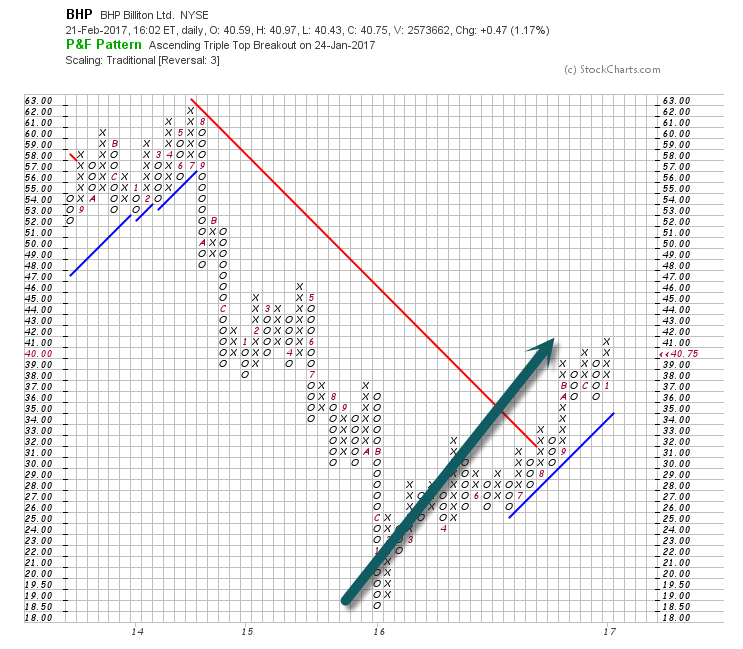
Buoyed by a resurgence in commodity prices, BHP Billiton (NYSE:BHP) swung back into the black during the fiscal first half of 2017, posting a net profit of $3.2B, compared with a loss of $5.7B in the same period a year earlier. The company said it would also raise its interim dividend to $0.40, up from $0.16, on the back of the uptick in earnings. BHP +1% premarket. www.seekingalpha.com
BHP breaks above red downtrend line from 2014
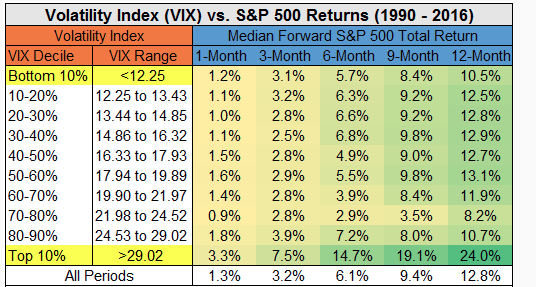
They say you should never short a dull market –>”when the VIX is in the bottom decile of historical readings, as it is now, the S&P 500’s forward returns are a hair below average but still solidly positive (1.2% in one month, 5.7% in six months and 10.5% in 12 months.) He also concludes it’s even more foolish to short a wild market: when the VIX is in its top decile, returns over the next year are a whopping 24% “
From Dave Lutz at Jones.
Source: RoadTrafficSigns.com
The big money in markets is often made by seeing what others don’t. It’s about resisting the gravitational pull of consensus, treading lightly where consensus is right, while spotting subtleties where the herd might be wrong.
#Volatility #ElectionDay
One subtlety we’ve been watching recently is volatility. Volatility, of course, is the measurement of the daily market fluctuations. In times of fear, the volatility of an asset rises. In times of buoyancy, all is well. The market simply floats higher and volatility falls.
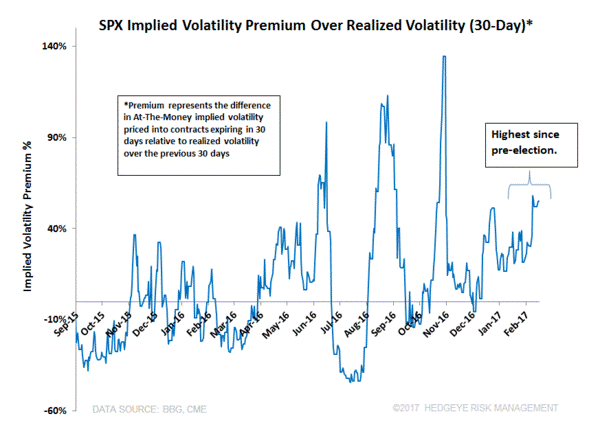
We have a nuanced view of volatility here at Hedgeye. Conceptually, there are two types of volatility we’re looking at, realized volatility (i.e. the volatility of an asset historically) and implied volatility (i.e. investors’ expectations of future volatility that’s embedded in options markets).
These volatility readings are painting a clear picture for investors today. As the stock market continues to make all-time highs, historical or realized volatility is falling to cycle lows. Meanwhile, fearful traders expect rising future volatility in the stock market and are buying downside protection in options markets to stave off the pain of an impending correction.
The Chart of the Day below from today’s Early Look is a visual representation of precisely that. The S&P 500 implied volatility premium on a 30-day basis is 52.2%. That’s a fancy way of saying investors are fearful of downside risks as historical volatility continues to fall. Note: A premium this high in the stratosphere hasn’t been hit since before Election Day.
#Economy #RetailSales #Inflation
Investors must put this volatility measure in the context of where we’re at in the economic cycle. Unsurprisingly, U.S. economic growth and inflation drive financial market returns. We believe both growth and inflation are accelerating.
Retail sales and inflation reports last week were near or above 5-year highs.
With this positive backdrop, we think equity markets can head higher from here. In other words, investors betting on significant future downside will get squeezed out of those positions.
It might actually be more risky piling into sectors like Consumer Staples (XLP) and Utilities (XLU), which are typically equity exposures investors buy when future downside is expected. In these sectors, implied volatility premiums are infinitesimal, 0.3% for Consumer Staples and 4.8% for Utilities. Implied volatility premiums this low suggest investor complacency.
The prevailing market trends say stick with U.S. equities here.
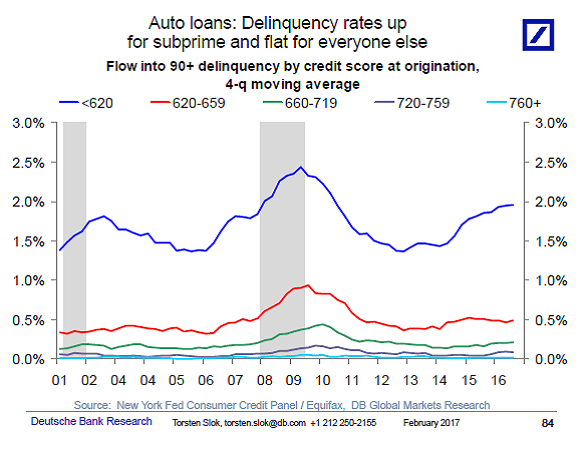
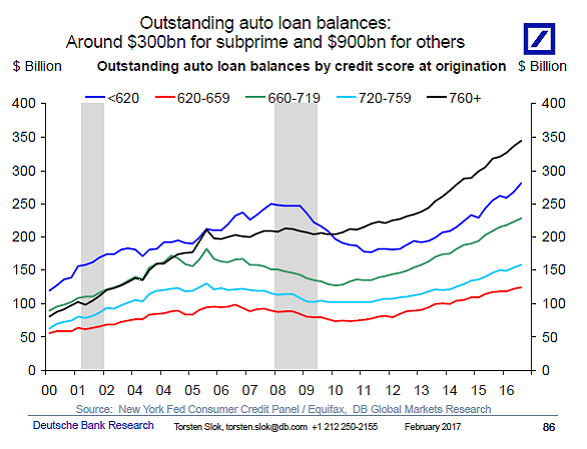
I’m getting questions from clients asking if the recent increase in subprime auto loan delinquency rates is a problem. Delinquency rates for people with credit scores lower than 620 have moved higher but for households with credit scores above 620 delinquency rates are moving sideways, see the first chart below. Also, while subprime auto loan origination has increased to 2006 levels we have seen an even bigger increase in origination and amount outstanding for prime borrowers, see the second and third chart. Finally, it is important to remember that total household net worth currently stands at $90 trillion, and in that perspective, total outstanding subprime auto loans at less than $300bn seems very small. The 2006 subprime mortgage market was much bigger than today’s subprime auto loan market, and there was much more leverage in the financial system in 2006 compared with today. The bottom line is that the increase in delinquency rates for subprime auto loans may be a worry for those holding the debt, but it is not a problem for the macro economy.
Let us know if you would like to add a colleague to this distribution list.
Torsten Sløk, Ph.D.
Chief International Economist
Managing Director
Deutsche Bank Securities
60 Wall Street
New York, New York 10005
Tel: 212 250 2155
A pullback in lending is forcing builders to scramble for financing to finish projects; ‘I haven’t seen anything this seismically different since 2008’
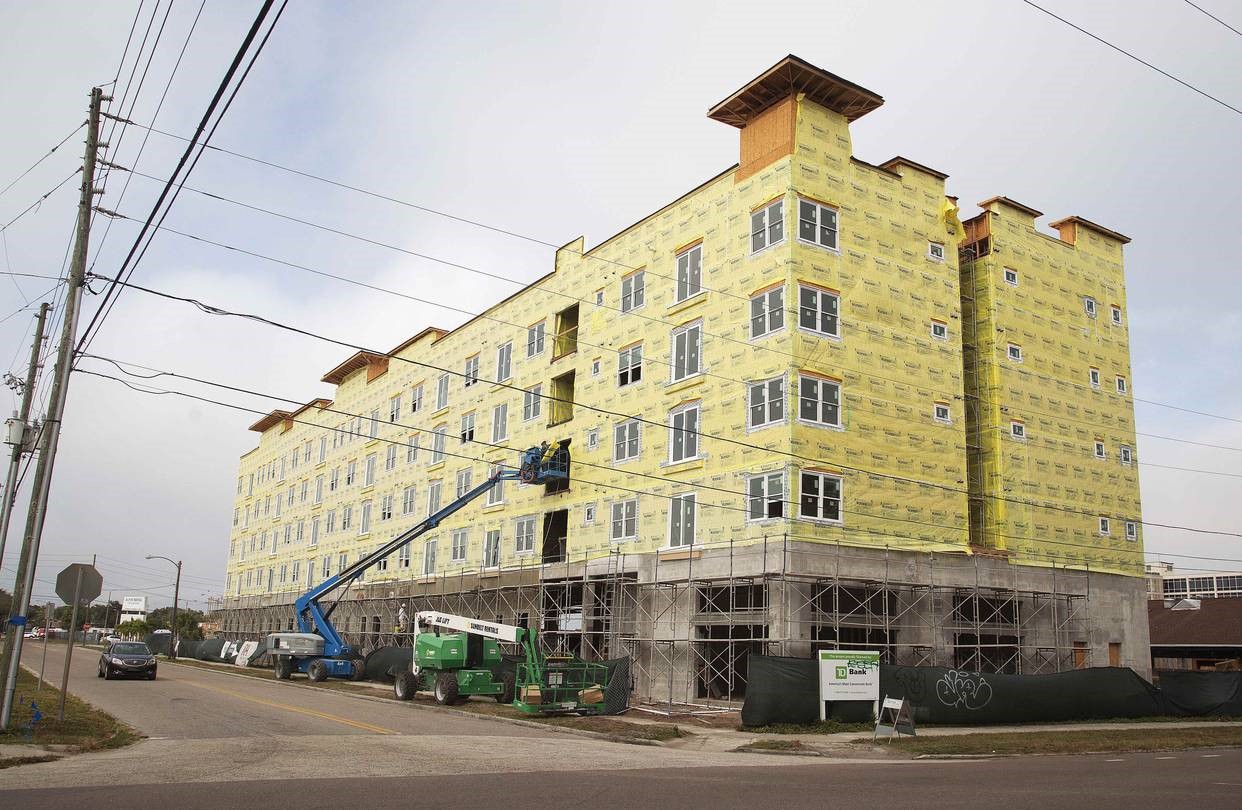
New apartment construction is seen underway in St. Petersburg, Fla. Photo: Scott Keeler/Tampa Bay Times/Zuma Press
By
Laura Kusisto
The Wall Street JournalThe apartment sector, which contributes some $284 billion to the economy annually, has been a winning bet for investors since the housing crash, as the economy recovered and more renters sought out units. Since 2010, average U.S. apartment rents have increased by 26%, according to data tracker MPF Research, a division of RealPage.“Our business has radically changed,” said Toby Bozzuto, president and chief executive of the Bozzuto Group, which owns or manages 59,000 apartments in cities across the U.S. “I haven’t seen anything this seismically different since 2008, when credit dried up.”
Now banks are in retreat, forcing developers to look to nontraditional lenders and seek more expensive types of financing to complete projects, said apartment executives, industry analysts, mortgage brokers and bankers.
“We had fairly robust growth in our construction, real estate construction book, and that’s slowing now,” said P.W. Parker, chief risk officer of Minneapolis-based U.S. Bancorp, during an earnings call last month. “Multifamily is an area that, if you look at the forecasts, there are forecasts pretty broad-based of potential rent declines in a lot of the major cities. So we’re being more cautious there.
https://www.wsj.com/articles/banks-retreat-from-apartment-market-1487678401
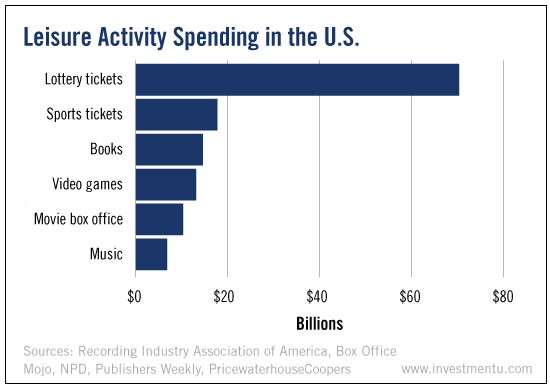
”Read Full Story http://www.investmentu.com/article/detail/53531/lottery-tickets-70-billion-tax-killing-retirement#.WK3pmG8rJhE
Published on February 21, 2017
Jeff Selingo
New York Times bestselling author, Washington Post columnist, higher education strategist, LinkedIn Top 10 Influencer
In the last few weeks I attended several higher education conferences where the talk among campus officials in the hallways and in sessions was usually centered around the same topic: President Trump. What’s clear in these conversations is that the much-discussed education divide that separated the electorate last fall between those with a college degree and those without has not dissipated since the election.
But the disdain academics exhibit for Trump these days ignores the role that their own colleges and universities played over the past two decades in fueling the working-class anger that led to his 2016 victory.
The story begins in the 1990s, when a college degree became increasingly necessary for economic success. The manufacturing sector, with its middle-class jobs requiring only a high-school diploma, had mostly collapsed the previous decade.
This shift in the economy coincided with a sea change in college admissions. The ease of travel and declining cost of communications meant that admissions was no longer a local game where even selective colleges with large endowments and strong brand names recruited mostly in surrounding states. When the U.S. News & World Report rankings became an annual publication in the late 1980s, colleges jockeyed to move up the rankings in order to gain prestige. To do that, they had to find better students outside their usual recruitment zone. And for schools a few rungs down the rankings ladder, it required luring top-notch students with boatloads of financial aid—even if their families didn’t need the money to send their kids to college.
Access to higher education for students at all income levels, which had been prevailing policy since the signing of the Higher Education Act in 1965, was shoved aside. In the drive for prestige, selective colleges in particular became less economically diverse, full of wealthy students and a few smart kids lucky to get a Pell grant (which mostly go to students from families making less than $50,000 annually). In 2013-14, only 22 percent of students received Pell grants at top universities, compared to around 38 percent everywhere else. Students on Pell grants tend to be clustered at less-selective public and private colleges, and poor-performing for-profit colleges.
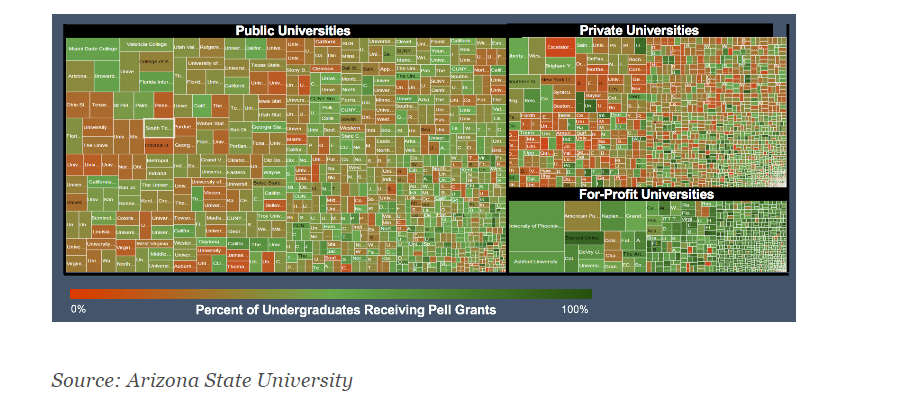
Source: Arizona State University
This economic disparity is well known in higher education, but the extent of it became clear last month when researchers released the most comprehensive look to date at the financial background of students on college campuses. The results of the study—gleaned from analyzing the tax records of some 30 million students born between 1980 and 1991 and linked to nearly every college in the country—were startling.
At 38 colleges, including five in the Ivy League, there are more students from families in the top 1 percent in income than the bottom 60 percent. What’s more, about 25 percent of the richest students attend a selective, elite college. By comparison, less than one-half of 1 percent of children from the bottom fifth of U.S. families by income attend an elite college.
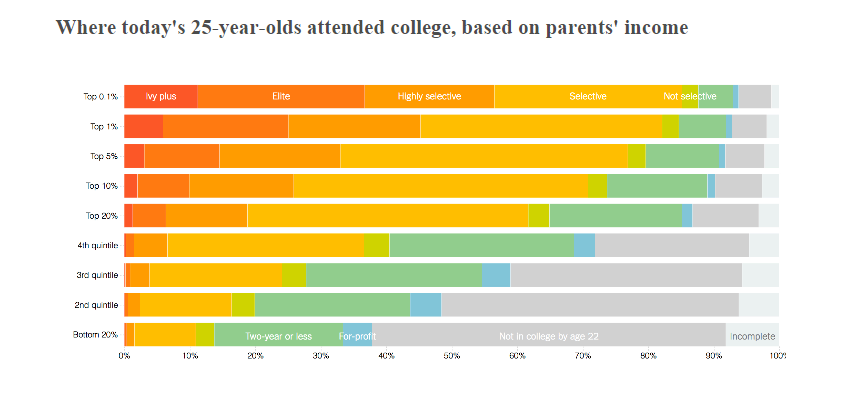
Source: New York Times
As the economic divide grew ever wider among students on campuses over the last two decades, countless students graduated from college without the benefit of ever really knowing classmates from working-class families. Some of them then came to Washington to work on Capitol Hill, in the White House and in federal agencies to develop policies that would impact people without a college degree. They had little idea what it was like to lack a credential that carried so much weight in the job market.
Instead of being shocked by Trump’s win, higher education leaders should look internally at their own strategies that focused on gaining prestige and often exacerbated the growing economic divide by favoring students from wealthy and middle-class families.
College leaders are beginning to take notice. In December, a handful of selective colleges and universities announced an effort to identify, recruit, and support highly qualified low-income students. The American Talent Initiative aims to boost the number of Pell grant recipients at the 270 colleges with the highest graduation rates by 50,000 within 10 years (an increase of more than 10 percent).
This effort is a good start to reverse the trends of the last two decades, but it might be too little, too late. Higher education lost an entire generation of students who will become leaders in the future and missed out on an opportunity to have an undergraduate experience full of students from different economic backgrounds.
Jeffrey Selingo is author of There Is Life After College: What Parents and Students Should Know About Navigating School to Prepare for the Jobs of Tomorrow. You can follow his writing here, on Twitter @jselingo, on Facebook, and sign up for free newsletters about the future of higher education at jeffselingo.com.
He is a regular contributor to the Washington Post’s Grade Point blog, a professor of practice at Arizona State University, and a visiting scholar at Georgia Tech’s Center for 21st Century Universities.
Cross-posted from The Washington Post
What could the sport of running teach us about the secrets of self-leadership and reaching our business finish lines?
I’ve been a fan of Dean Karnazes ever since I read his book Ultramarathon Man several years ago, so I eagerly devoured his newest, The Road to Sparta, which tells the story of history’s first-ever marathon.
Some of us know the popular version of the story, where after the Athenians defeated Persian invaders at the battle of Marathon 490 B.C., a messenger ran 26 miles to share the exciting news.
But Karnazes shares the real story, where the runner, whose name was Pheidippides, actually ran more than 150 miles all the way from Athens to Sparta, then back again, before the battle.
That’s 300 miles.
Why would a person willingly go through something like that?
“Western culture has things a little backwards right now,” Karnazes said. “We equate comfort with happiness. And now we’re so comfortable we’re miserable. There’s no struggle in our lives.”
That observation doesn’t just apply to running. That applies to all of life, including leading our organizations. When it comes to work, comfort equals boredom.
Engagement and even happiness come when we’re gunning toward major goals. I’m talking about the kind of achievements that push us outside our comfort zone.
Maybe it’s launching a new product line, starting a new career, or growing a sales channel by double digits. If staring down the goal makes you feel uneasy, you’re on the right track.
This ‘Discomfort Advantage’ is only one of the lessons running can teach us. Here are three leadership takeaways I discovered when I read The Road to Sparta:
When Karnazes was a child, he went to a basketball camp coached by the legendary John Wooden. A small kid, Karnazes struggled to get rebounds like the bigger children. But Wooden could see his spirit and gave him some advice: “Do what you can.” Instead of going for rebounds, he started playing the backcourt. And he dominated.
When we compete head-to-head as if our abilities are the same as others, we sometimes miss playing to our strengths. It’s like we tilt the playing field against ourselves. Instead, we need to focus on what makes us unique. Steve Jobs is one of the best examples of this in recent years. Apple played its own game and rose to dominance.
We have to be careful that our jobs don’t dominate our lives, but there’s a natural tension in play if we really love what we do. “People speak of finding balance,” says Karnazes. “To me, that’s a misplaced ambition. If you have balance, you do everything okay. … Balance doesn’t lead to happiness—impassioned dedication to one’s life purpose does.”
What else could lead a person to run 153 miles through Greece? What else could lead an entrepreneur to do what the market believes is impossible? Balance is desirable, but it’s not the endgame. Finding and achieving your life’s purpose is.
When we reach our goals, we need to take the appropriate time to celebrate. That’s a critical way to honor our work. But it’s also a key component of living a full life.
Hosting another run in Greece called the Navarino Challenge, Karnazes was surprised at how the townspeople came out to celebrate the winners. “These people were all willing to put aside what they were doing and join together,” he remembered, “rejoicing in the moment.”
“If we always made decisions with our heads instead of our hearts, we’d probably live much more orderly lives,” he says, “but they would much less joyous. … How many people spend their entire lives striving for something with their nose to the grindstone, only to wake up one day and realize they haven’t really lived at all?”
Trade on your unique abilities, stay fueled by passion for your work, and take time to celebrate your accomplishments.
Those three takeaways might serve an athlete. But I’m confident they’ll serve leaders even more.
Originally published by Michael Hyatt on December 16, 2016
http://www.earlytorise.com/self-leadership-secrets-extreme-athlete/
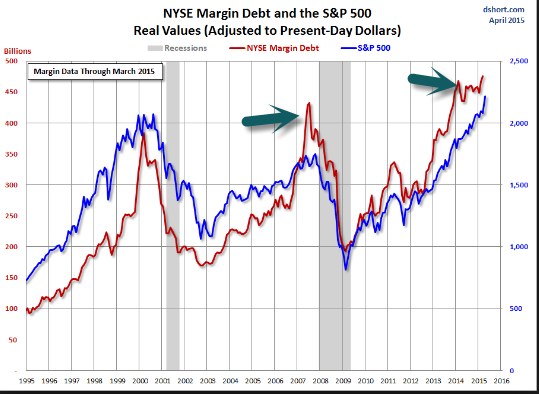
 1. Margin debt has increased 193% since the bull market began—the same as the rise from 2002 to 2007.
Michael Belkin called the 2000 market top. Now the publisher of the Belkin Report, an institutional newsletter on asset allocation, and the Belkin Gold Stock Report is waving a warning flag about the level of margin debt on the New York Stock Exchange.
Margin debt is the loans banks and brokerages make to investors, using their stock- and bond-holdings as collateral. In November, it neared an all-time high of $507 billion and has hovered close to that level since. “It’s something that’s hanging over the market,” he says. “The market is addicted to debt.”
There’s precedent for a high level of margin debt foreshadowing a market collapse. It peaked in March 2000, congruent with the market’s March 24 top and subsequent 49% decline. And it peaked again in July 2007, a few months before the market top in October. Another disturbing factor: The percentage rise in margin debt over the latest bull market is 193%, exactly the increase from 2002 to 2007, when the financial crisis began and the Standard & Poor’s 500 index later fell 57%.
The problem with margin debt is that it causes a cascade effect. As the market falls, investors get margin calls on their loans and have to sell stocks to maintain their margin-debt minimum.
Ed Yardeni, president of Yardeni Research, says, “As long as the market is going up, margin debt tends to go up as well.” And margin debt exacerbates a bear market. But Yardeni doesn’t know of any time when margin debt triggered a bear market. That’s a relief.
http://www.barrons.com/articles/is-margin-debt-a-bear-market-indicator-1487394796
The NYSE has released new data for margin debt, now available through December. The latest debt level is down 2.2% month-over-month. The current level is 3.5% below its record high set in April 2015. The December data gives us an additional sense of investor behavior during the election rally.
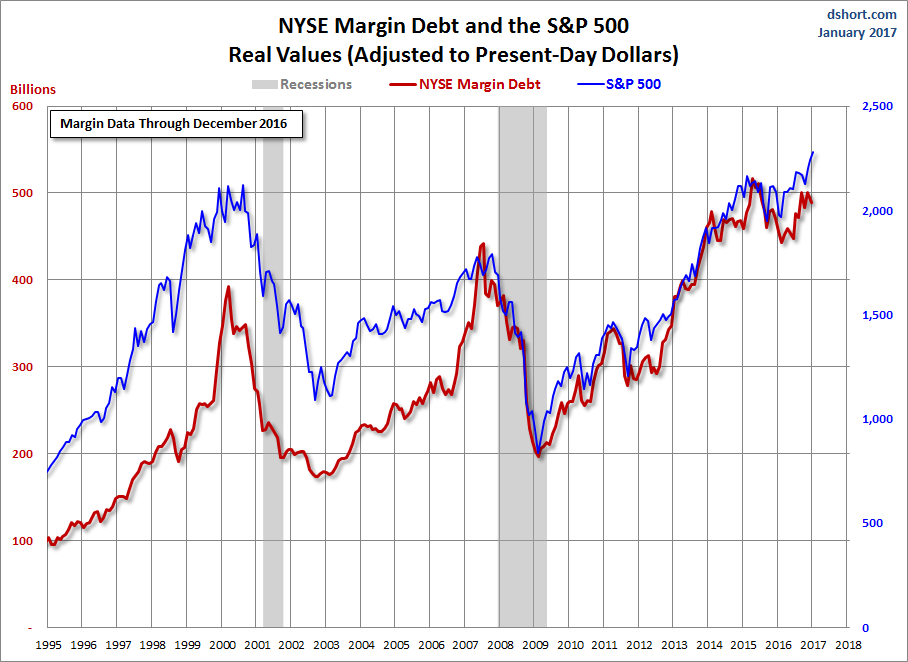
https://www.advisorperspectives.com/dshort/updates/2017/02/01/a-new-look-at-nyse-margin-debt-and-the-market
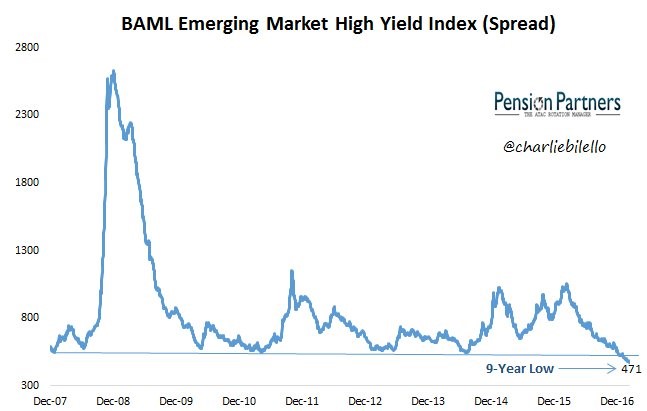
Yield Spread and Risk
Typically, the higher risk a bond or asset class carries, the higher its yield spread. When an investment is viewed as low-risk, investors do not require a large yield for tying up their cash. However, if an investment is viewed as higher risk, investors demand adequate compensation through a higher yield spread in exchange for taking on the risk of their principal declining. For example, a bond issued by a large, financially healthy company typically trades at a relatively low spread in relation to U.S. Treasuries. In contrast, a bond issued by a smaller company with weaker financial strength typically trades at a higher spread relative to Treasuries. For this reason, bonds in emerging markets and developed markets, as well as similar securities with different maturities, typically trade at significantly different yields.
Read more: Yield Spread Definition | Investopedia http://www.investopedia.com/terms/y/yieldspread.asp#ixzz4YeksCSSR
Found on abnormal returns hot links
 Emerging Markets Ex-China
The index measures the stock performance of up to 700 emerging market companies, excluding companies domiciled in China and Hong Kong. Companies are selected and weighted according to free-float market capitalization.
http://etfdb.com/index/egai-emerging-markets-ex-china-index/
Charts from Yahoo
http://finance.yahoo.com/quote/EEM/?p=EEM
Continue reading
For some perspective on a key US stock market index, today’s chart illustrates the overall trend of the tech-laden Nasdaq Composite since 2000. As today’s chart illustrates, the Nasdaq’s seven-year post-financial crisis rally is still very much intact. While other major indices have pulled back slightly (though still trade near historic highs — the Dow just closed above 20,000 and the S&P 500 is closing in on 2,300) the Nasdaq continues to post all-time record highs and, today, did so once again.
 Continue reading
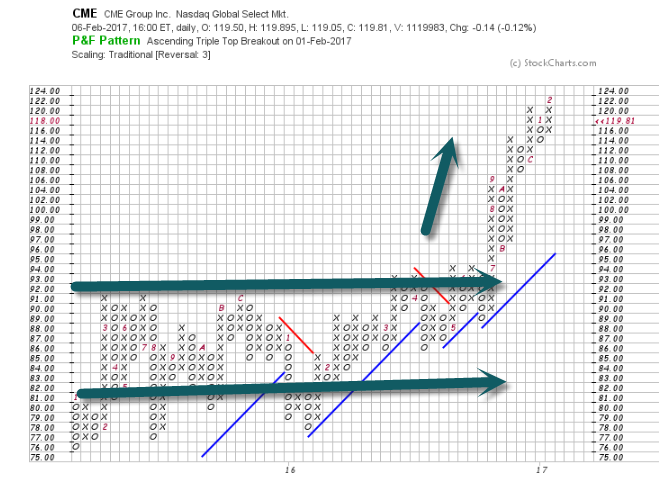
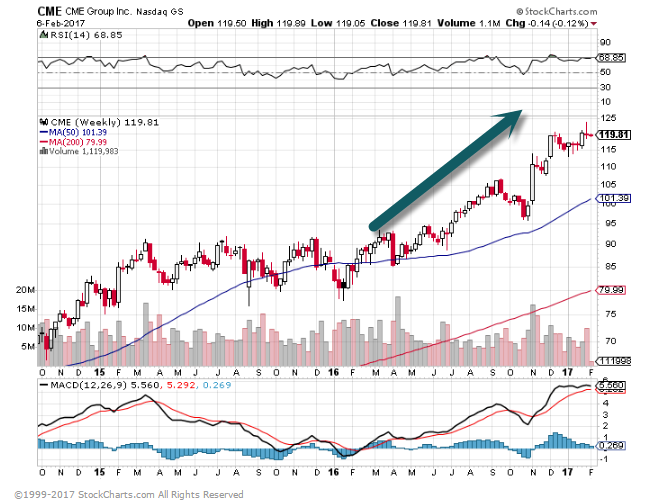
CME Group is the world’s leading and most diverse derivatives marketplace, handling 3 billion contracts worth approximately $1 quadrillion annually (on average). The company provides a marketplace for buyers and sellers, bringing together individuals, companies and institutions that need to manage risk or that want to profit by accepting risk.
Our exchanges – CME, CBOT, NYMEX and COMEX – offer the widest range of global benchmark products across all major asset classes, including futures and options based on interest rates, equity indexes, foreign exchange, energy, agricultural commodities, metals, weather and real estate. As part of our commitment to providing innovative risk-management solutions to the marketplace, CME Group also offers a growing slate of cleared OTC products and services.
Through our CME Globex electronic trading platform, users worldwide are able to access the broadest array of the most liquid financial derivatives markets available anywhere. Additionally, CME Group operates CME Clearing, one of the world’s leading central counterparty clearing providers. By serving as the counterparty to every trade that happens in our markets, we protect the integrity of our markets, virtually eliminating third-party credit risk.
For the global economy, this unparalleled access translates into opportunity.
http://www.cmegroup.com/company/history/
www.stockcharts.com

Inflation across the world is beating analysts’ forecasts even before the potential effect from Donald Trump’s economic policies. The global Citi Inflation Surprise Index, which measures price surprises relative to market expectations, is at the highest in more than five years. The reading turned positive in December — meaning inflation data were higher than expected — for the first time since 2012.
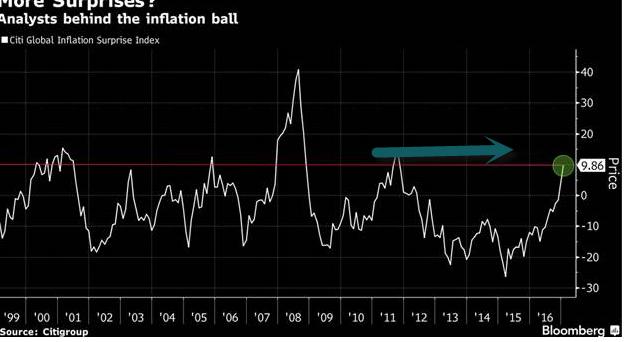
Thanks to Dave Lutz at Jones for Chart.
 Emerging Markets Rally After Dollar Fall
 www.yahoofinance.com
There have been 75 sessions (including Monday) without a 1% drop in the S&P, which marks the longest such streak in about 11 years, according to Krinsky. A period of sideways trading tends to suggest that the market has pent up momentum. And if history is any gauge, momentum may be leaning toward a downturn, given the market’s tendencies in February.
http://www.marketwatch.com/story/a-big-stock-market-selloff-in-february-looks-increasingly-likely-2017-01-30
From Doug Short Blog
https://www.investing.com/analysis/margin-debt-and-the-stock-market-200161449
 www.stockcharts.com
 Continue reading
 Clear Vision of Possible New Lows.
 Continue reading
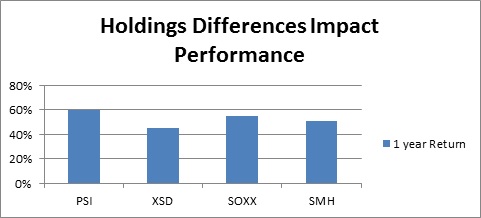
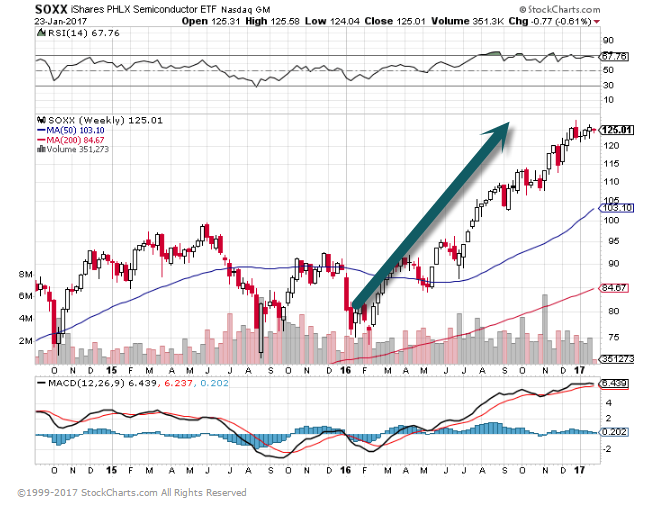 Semiconductor ETFs To Consider
The iShares PHLX Semiconductor ETF (SOXX) has $660 million in assets. Exposure is primarily in semiconductor stocks (87% of assets), while semiconductor equipment stocks (13%) like Applied Materials (AMAT) are much less represented. In addition to U.S. stocks, the ETF has exposure to companies based in Singapore and Taiwan, The ETF trades on average 515,000 shares on a daily basis and has a 0.48% net expense ratio.
http://www.etf.com/sections/blog/semiconductor-etfs-looking-another-banner-year
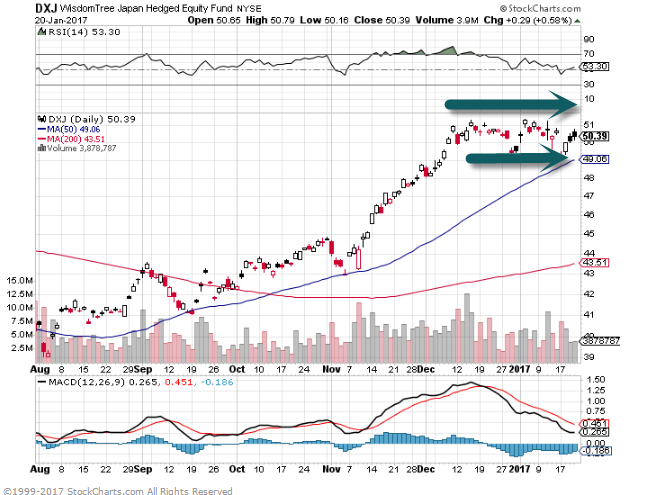
 Long Japan Hedged…Central Bank now Buying Stocks.
 Read Full Gundlach Comments
http://www.barrons.com/articles/2017-roundtable-part-2-manual-for-a-mixed-up-market-1484976857?tesla=y&mod=BOL_twm_ls
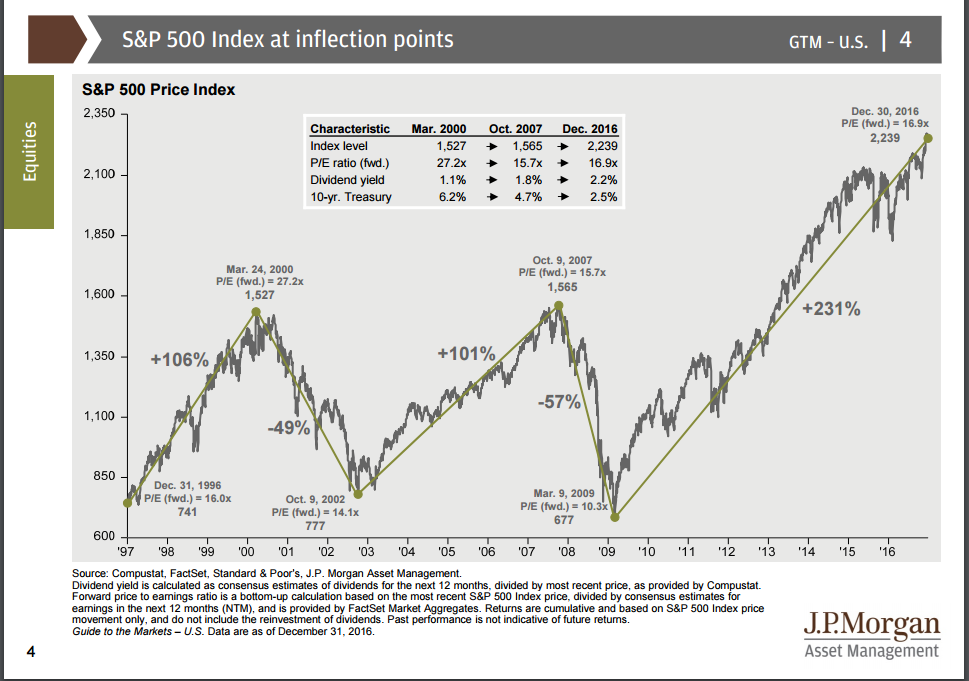
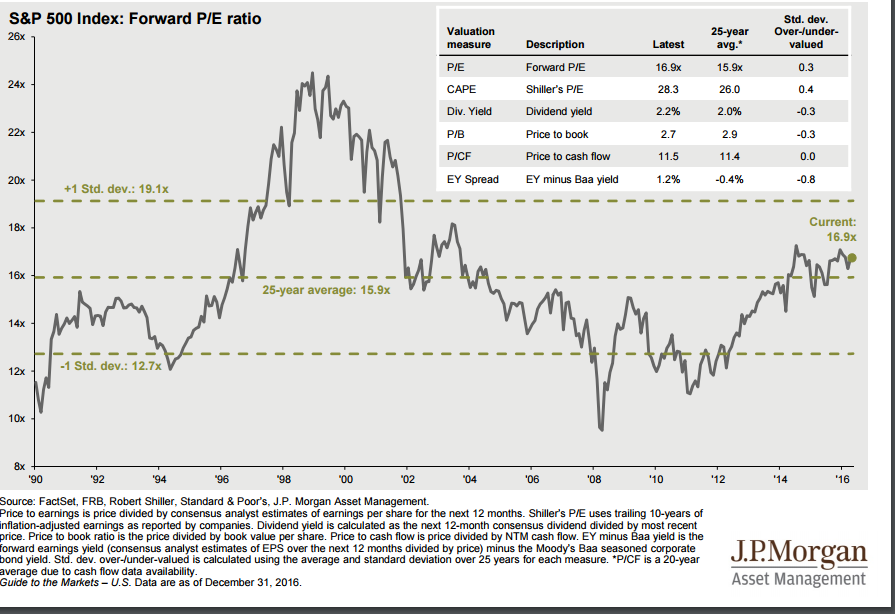
https://am.jpmorgan.com/blob-gim/1383280028969/83456/jp-littlebook.pdf
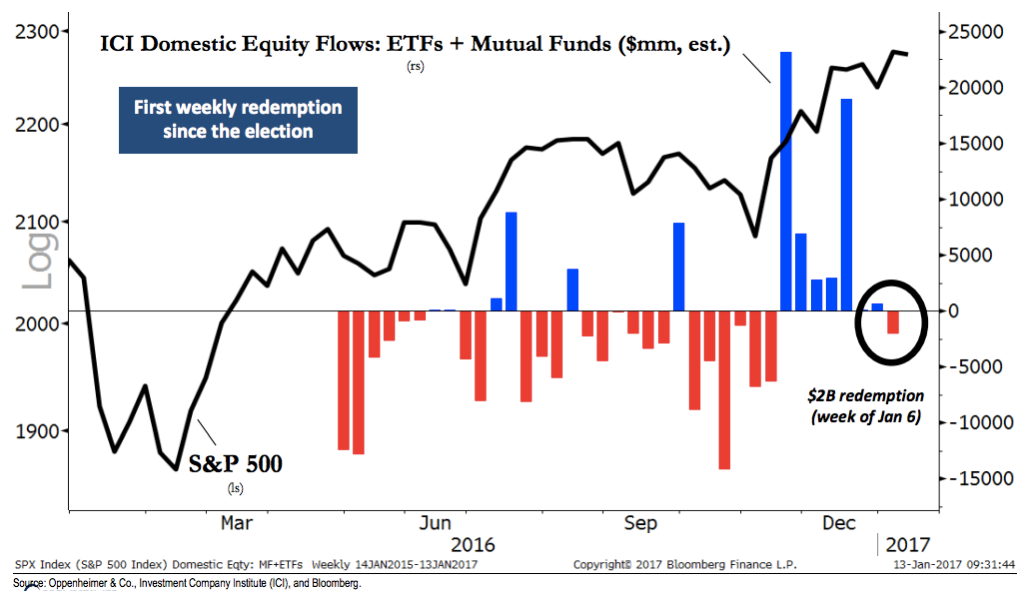
Euphoria? Okay, sure. Maybe in word, but not in deed. Here’s Oppenheimer’s Ari Wald highlighting a divergence that merits attention…
While newsletter surveys are signaling optimism, recent fund flow data suggests that investor skepticism still lingers. For instance, ICI estimated a $2B net outflow from domestic equity ETFs and mutual funds for the week of Jan 6 which marks the first redemption since the US election. What investors are doing is often more important than what they’re saying, and we therefore view this lack of euphoria as a positive for the overall equity cycle.
From Josh Brown Blog
http://thereformedbroker.com/2017/01/17/chart-o-the-day-bullish-but-selling/
as falling unemployment and record-low interest rates boosted spending. According to the Federal Statistics Office, GDP growth rose 1.9%, after a gain of 1.7% the previous year. Germany is the first of the world’s biggest developed economies to provide preliminary GDP data for 2016.
www.seekingalpha.com
Chart of the Day
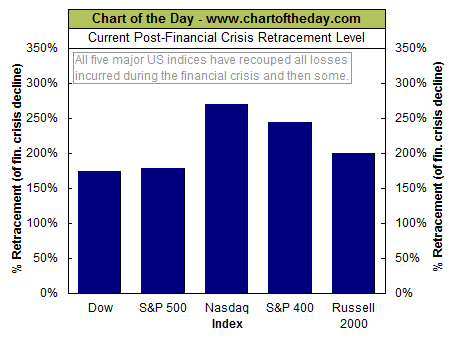
For some perspective on the post-financial crisis rally, today’s chart illustrates how much of the downturn that occurred as a result of the financial crisis has been retraced by each of the five major stock market indexes. For example, the Dow peaked at 14,164.53 back in October 9, 2007 and troughed at 6,547.05 back on March 9, 2009. The most recent close for the Dow is 19,855.53 — it has retraced 174.7% of its financial crisis bear market decline. As today’s chart illustrates, each of these five major stock market indices have retraced over 170% of their financial crisis decline. However, it is the tech-laden Nasdaq that leads the pack with a retracement of 269% — impressive considering the severity of the financial crisis bear market.
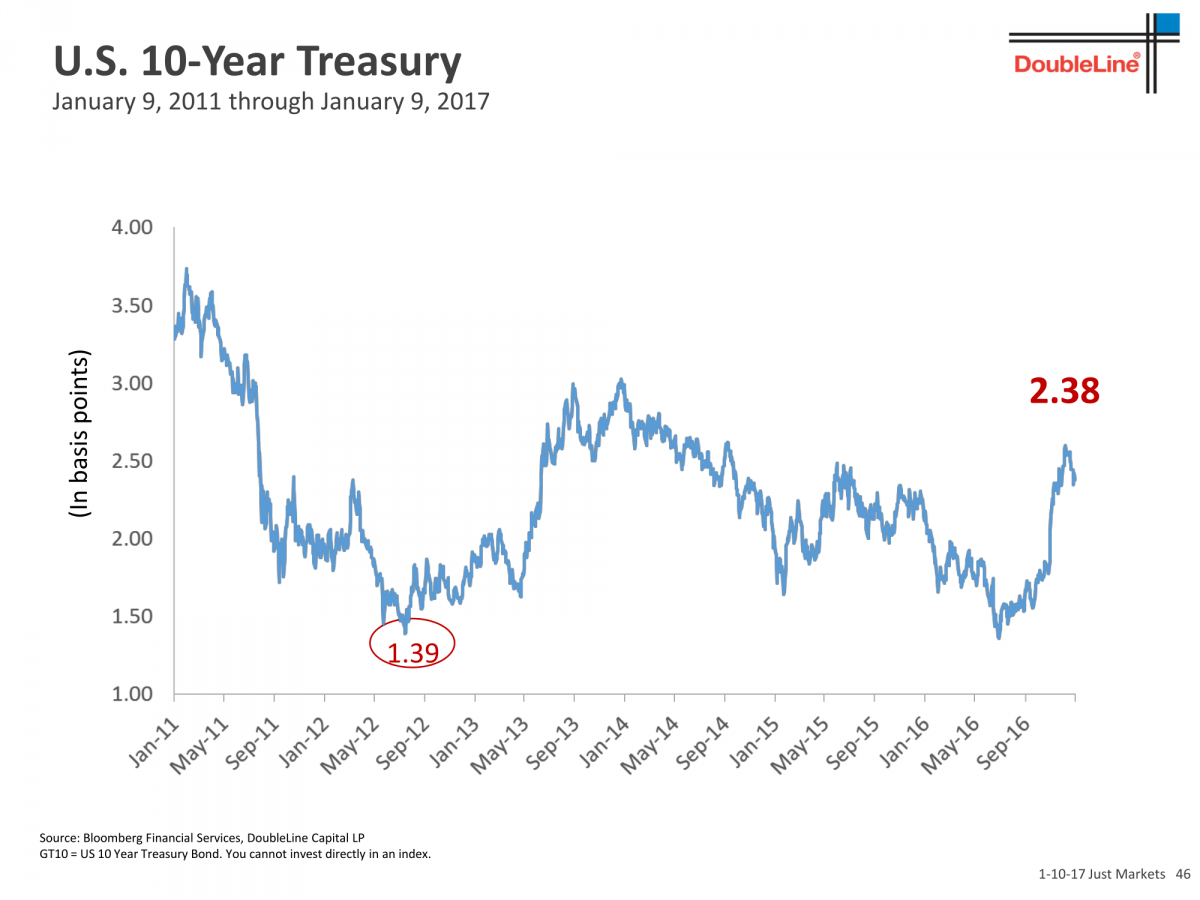
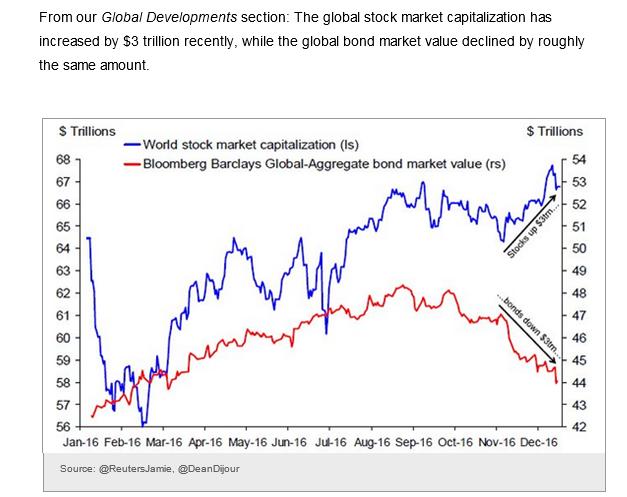
“Almost for sure we’re going to take out 3% on the 10-year in 2017,” Gundlach said. If we exceed 3% (not 2.6%) in 2017, it’s goodbye to the bull market because you would no longer have declining peaks in yields.
A 10-year above 3%, with the 30-year yield approaching 4%, would also be trouble for the equity market because they would start to look like ‘real’ yields to investors.
Gundlach said it’s not radical to forecast a 6% yield on the 10-year by 2020.
View Full Deck
http://www.businessinsider.com/jeff-gundlach-webcast-2017-outlook-just-markets-2017-1
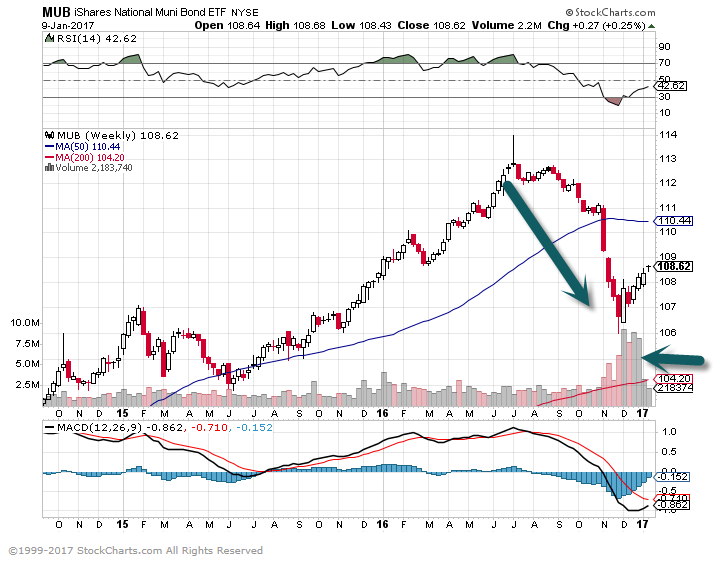
Credit: The muni market capital outflows have been substantial, resulting in a rare loss for intermediate-maturity bonds.
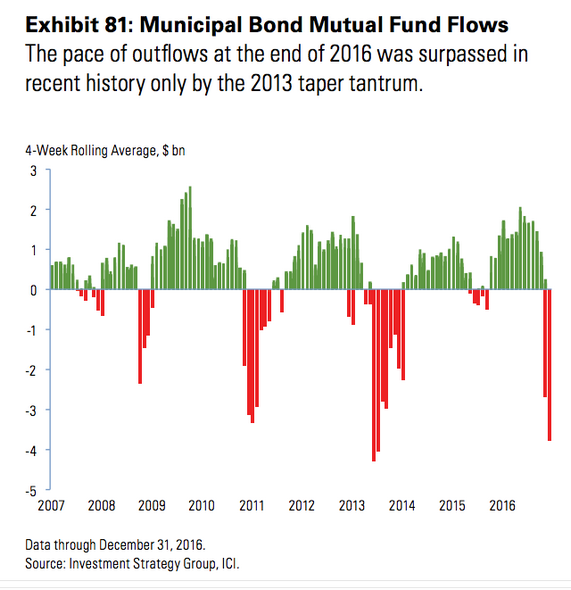
Source: Barclays, @NickatFP, @joshdigga
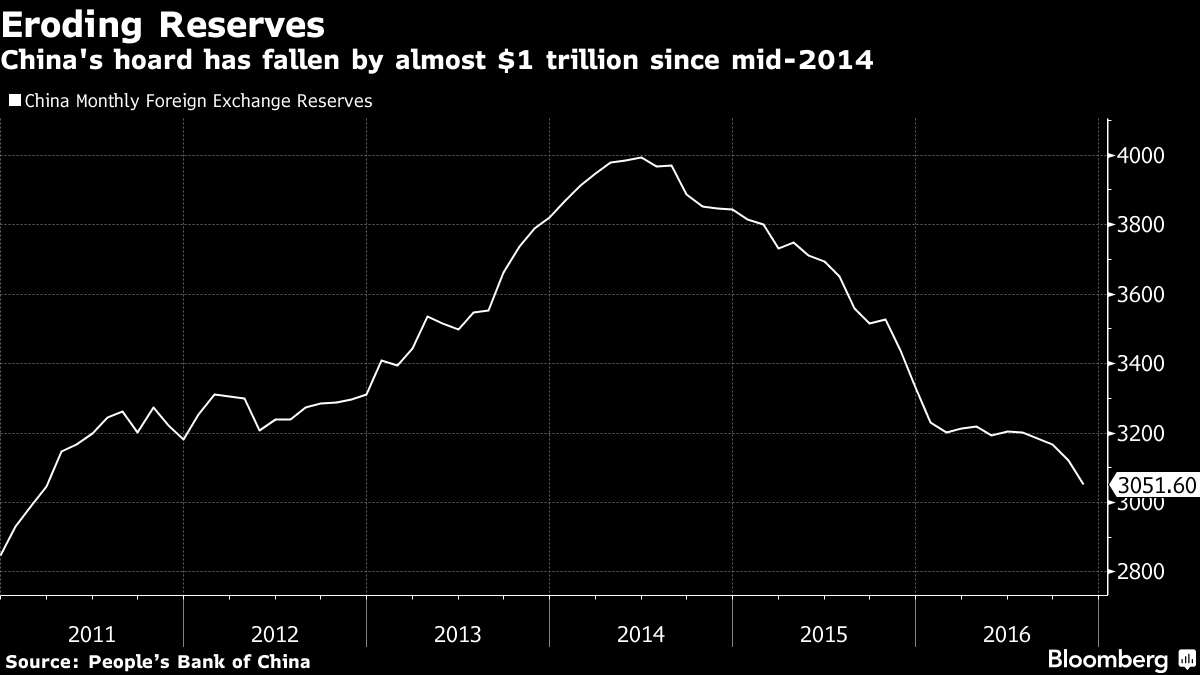
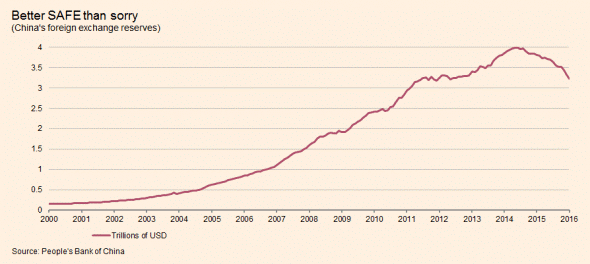
China is making it harder to short the Yuan and more difficult to take money out of the country, but time will tell if they can protect the currency forever. …If not, a free floating Yuan will be a new ball game for all currencies.http://www.barrons.com/articles/the-growing-threat-to-global-trade-a-currency-war-1483767171
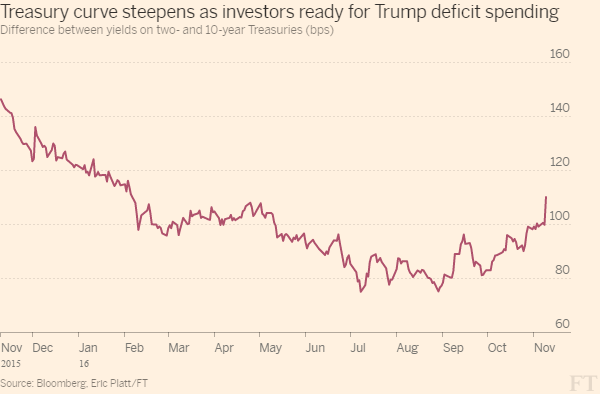
I find more reason for optimism in the yield curve – the plot of the yields on 3-month through 30-year Treasury securities. The yield curve has steepened since the election, and this is good news.
The slope of the yield curve has borne a consistent relationship with economic activity. The yield curve has predicted all U.S. recessions except one since 1950. Recessions, as you would expect, correlate positively with bear markets. When the yield curve flattens, or inverts, a recession usually looms and so does a bear market.
That’s not the case today. The yield curve is just the way we should like it – progressively higher with each maturity and upward sloping to the right. When the yield curve steepens, economic growth usually follows.
Yield Curve Slope

http://etfdailynews.com/2017/01/04/dow-20k-is-just-the-beginning-of-a-massive-rally-in-2017/
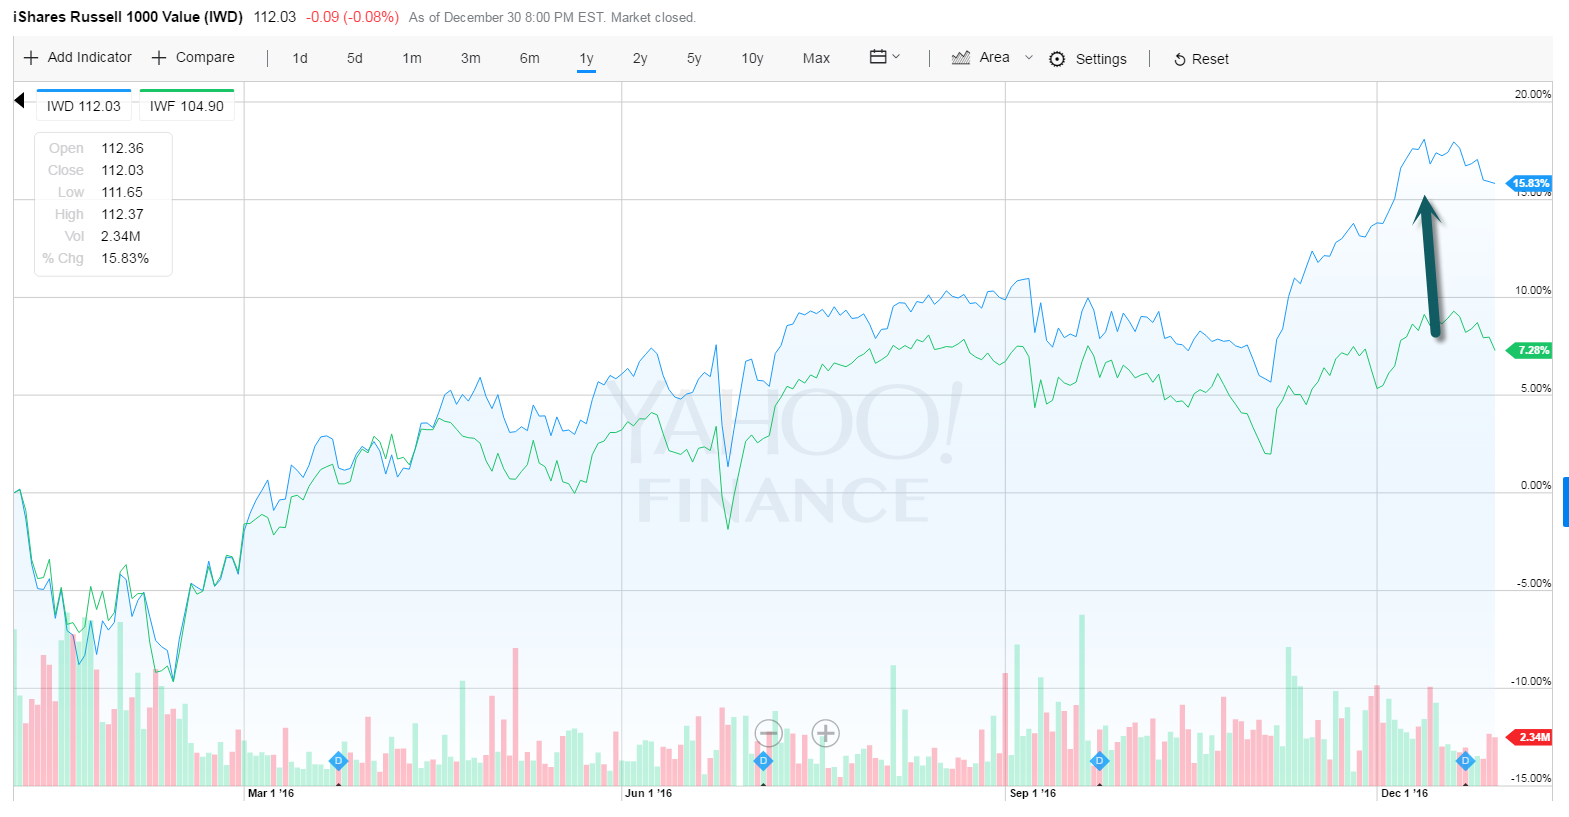
Since then, the iShares Russell 1000 Value ETF (ticker: IWD) has returned 17%, versus 9.1% for the iShares Russell 1000 Growth (IWF). The last stretch of significant outperformance for value ended in 2006, and it was a whopper. Value beat growth by double-digit percentages in five out of seven years, starting with the 2000 dot-com stock bust.
http://www.barrons.com/articles/will-2017-be-the-year-of-the-trump-rooster-1483169072
The one thing you need to understand about stock market valuation
Published on December 19, 2016CEO at Ritholtz Wealth Management
Last week, we held our quarterly conference call for Ritholtz Wealth Management, in which Chairman and CIO Barry Ritholtz tackled a host of topics – from presidents’ impact on stock markets to interest rates to annual returns. The call was accompanied by our regular quarterly letter.
One section I found to be very helpful for clients had to do with the CAPE ratio and the concern that valuations on US stocks are elevated relative to history right now. Here’s what Barry and our director of research, Michael Batnick, had to say on the subject:
Let’s start with CAPE – the Cyclically Adjusted Price to Earnings ratio. Think of it as the 10-year P/E. It is high for US equities by historical averages, elevated for Japan, moderate for Europe, and low for emerging markets. If we wanted to scare people, we would selectively pull data out showing at present we have the highest reading outside of 2000 (43.2), 1929 (32.5) and 2007 (27.6). But we don’t cherry pick dates to scare people, instead we use data to look for evidence.
Since 1990, the S&P 500 has been trading above the average CAPE ratio during 307 out of 324 months – that’s a total of 95% of the time. If you exited US equities when the CAPE ratio was overvalued, you would have missed gains of more than a 1000% over that time. In fact, had you only invested when the CAPE was 25% overvalued – i.e. when stocks were “very expensive” – your total returns since 1990 would have been 650%. This is one of the many reasons why it is ill advised to use valuation as a timing mechanism.
The most we can really say about a higher than average CAPE is that when it is significantly above its long-term average, we should lower our expectations for future returns. When we look around the world, we see the United States is more expensive than Europe, or emerging markets, or Japan on nearly every single valuation metric. This should not be surprising, given how much the United States has outperformed other countries since the financial crisis ended in 2009. The good news is that our portfolio is exposed to global equities, and as the equity leadership shifts – whenever that might be – our portfolios will benefit from it.
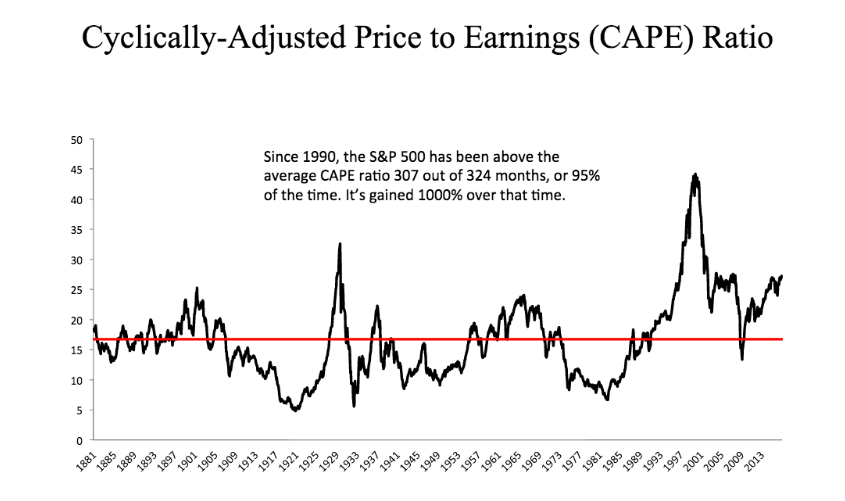
Josh here – one interesting thing to keep in mind is that, while the CAPE for US stocks is currently 25.5, the CAPE for Europe is a more reasonable 15.6 and just 14.4 for Emerging Markets stocks. Additionally, the massive profit wipeouts from 2009, which are obviously biasing the ratio higher, will be rolling off in 2020. Finally, as Professor Jeremy Siegel has pointed out, we’re comparing apples to oranges to some extent, given the fact that the accounting treatment of earnings and losses has changed from one era to the next, which changes the composition of as-reported numbers.
Rather than dismissing valuation concerns out of hand, we prefer to think about them in the context of an overall asset allocation plan. For as long as you will be an investor, there will always be valuation concerns for one asset class or another.
If you’re interested in learning more about how we work with clients on their financial plans and investment portfolios, talk to us here:
From Dorsey Wright
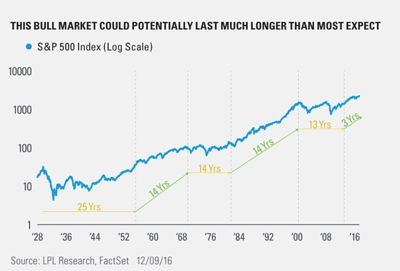
While the S&P 500 SPX, -0.11% has been in a bull market since the bottom of the financial crisis in 2009, it only broke out of a 13-year consolidation period in 2013, according to Ryan Detrick, senior market strategist at LPL Financial. In the past, when such lengthy periods of essentially flat returns came to a close, the result was an equally long advance. (While markets were extremely volatile between 2000 and 2013, an era marked by both the dot-com bubble and the financial crisis, it failed to make decisive new highs for an extended period in that timeframe.)
Italy is preparing to take a €2B controlling stake in Monte dei Paschi di Siena (OTCPK:BMDPY), which the bank hopes will attract private investors to fill the gap in rescue funding. According to Reuters, the government plans to buy junior bonds to boost its stake to 40%, making it the biggest shareholder by far. Questions whether this amounts to state aid will surely arise in Brussels.
www.seekingalpha.com
|
Reach out to Eric Boucher for more information on Renmac
EBoucher@renmac.com www.renmac.com
The people that use all-time highs to scare you are the same people who told you that the 27% selloff in the Russell 2000 earlier this year was the canary in the coalmine. Small-cap stocks are now at all-time highs and 40% off their February lows.
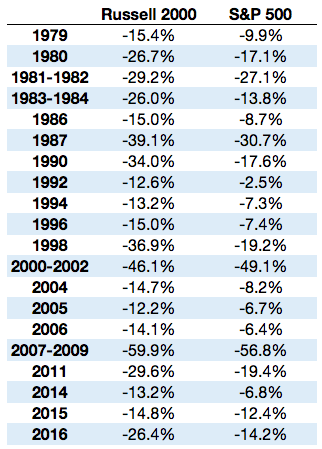
You can see that the Russell 2000 has shown a history of more frequent and deeper losses than the S&P 500. Here are the numbers behind this chart which shows the various Russell 2000 corrections and bear markets since 1979 along with the corresponding S&P 500 losses during those times:
There have been plenty of large losses in small caps that didn’t really seem to affect what was going on with large caps. Going again by the trivial definition I used from above on bear markets (20% loss or worse) the Russell 2000 has experienced ten in this time while the S&P 500 has only seen four (with two or three close calls).
Some takeaways:
Volatility in small caps is a double-edged sword. It can be painful to stick with them, but they also provide more frequent and better entry points for investing. If you’re dollar cost averaging into your retirement savings, small caps are great asset class because you have had more chances to buy in at lower prices. This is a good thing, but it requires discipline and the ability to buy when others are selling.
Read Full Story http://awealthofcommonsense.com/2016/11/the-agony-of-investing-in-small-cap-stocks/
 The relatively small fund—it only has $232.7 million in assets, according to FactSet, and it trades under 40,000 shares a day, on average—focuses on small and microcap stocks, while its value tilt gives it a lower price-to-book ratio than other ETFs tracking small-cap indexes. Another Guggenheim value fund, the Guggenheim S&P 500 Pure Value ETF RPV, -0.37% is the second-best performer, boasting a 634.88% since the 2009 bottom.
The gain of the S&P 500 ETF places it as the 180th best performer of the 563, putting it in the top third of funds. That a heavy majority underperformed the benchmark speaks to one of the biggest investing trends of the past seven years: the growing adoption of passive investing. Research has shown that very few active or “smart beta” funds can beat the broader market over the long term.
Don’t miss: New rule may create a $10 trillion ETF juggernaut by 2020
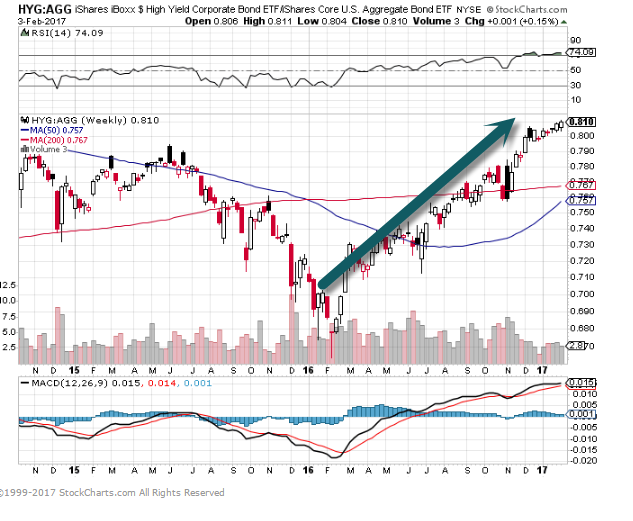
Among other widely-followed funds, the iShares Core U.S. Aggregate Bond ETFAGG, +0.11% is up 35.31% since the stock market bottom (454th best), the iShares iBoxx $ Investment Grade Corporate Bond ETF LQD, +0.14% has gained 74.4% (405th best), and the iShares iBoxx $ High Yield Corporate Bond ETF HYG, -0.13% is up 128.19% (334th best). The SPDR Gold Trust GLD, -0.62% is up 24.68% over the period (471st best) while the Vanguard FTSE Emerging Markets ETF VWO, +0.06% has gained 116.78% (354th best).
In a sign of how broadly the economy has recovered, 510 funds—or 90.5%—are at least somewhat positive since the market bottom, not including fees. The smallest gainer of the applicable universe, the SPDR Bloomberg Barclays Short Term International Treasury Bond ETF BWZ, +0.47% is up a mere 0.3% over the period. The narrowest loser, the SPDR Bloomberg Barclays 1-3 Month T-Bill ETF BIL, +0.00%is down 0.2%, for an annualized loss of 0.04%.
In addition to the Guggenheim funds, specific sectors also numbered among the top 10 ETFs. Two internet funds charted, underlining the explosion in technology usage and businesses over the past seven years. Since the market bottom, major companies like Facebook Inc. FB, +0.38% and Twitter Inc. TWTR, -0.60% have gone public, while names like Netflix Inc. NFLX, +0.50% have become major businesses.
Here are the 10 best-performing funds since the market bottom:
| Rank | Security | Return |
| 1. | Guggenheim S&P Smallcap 600 Pure Value ETF RPV, -0.37% | 675.97% |
| 2. | Guggenheim S&P 500 Pure Value ETF RPV, -0.37% | 634.88% |
| 3. | PowerShares Nasdaq Internet Portfolio PNQI, +0.25% | 566.7% |
| 4. | Guggenheim S&P Midcap 400 Pure Value ETF RFV, -0.86% | 560.06% |
| 5. | SPDR S&P Insurance ETF KIE, +0.07% | 536.29% |
| 6. | First Trust Dow Jones Internet Index Fund FDN, +0.01% | 535.66% |
| 7. | Guggenheim S&P 500 Equal Weight Consumer Discretionary ETFRCD, -0.22% | 532.36% |
| 8. | Guggenheim S&P 500 Equal Weight Financials ETF RYF, +0.24% | 505.45% |
| 9. | First Trust NYSE Arca Biotechnology Index Fund FBT, +0.08% | 504.56% |
| 10. | Oppenheimer Small-Cap Revenue ETF RWJ, +0.03% | 504.22%
|
Read Full Story
http://www.marketwatch.com/story/this-etf-has-jumped-sevenfold-since-the-start-of-the-bull-market-2016-11-29
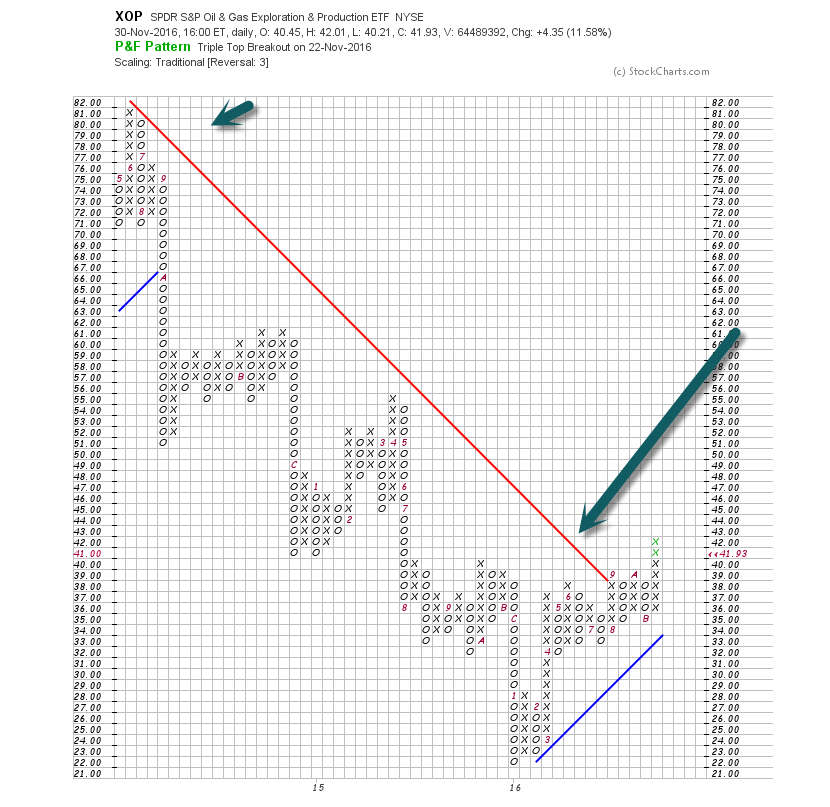
The oil club is dizzy with its own success after a harmonious meeting in Vienna, where it surprised the world by agreeing to its first production cut in eight years. Crude prices up 12%? Check. Saudi Arabia and Iran in agreement? Check. OPEC and Russia working together? Check. The big question now is whether all these cuts will be implemented. Meanwhile, crude is up over $50 a barrel, lifting energy shares in its slipstream.
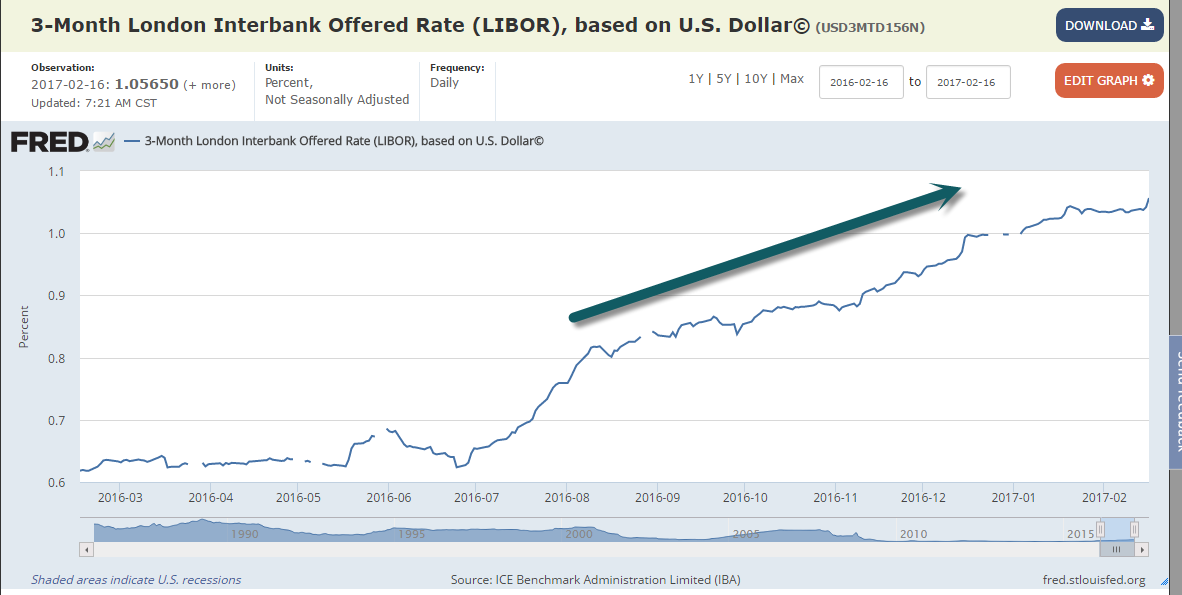
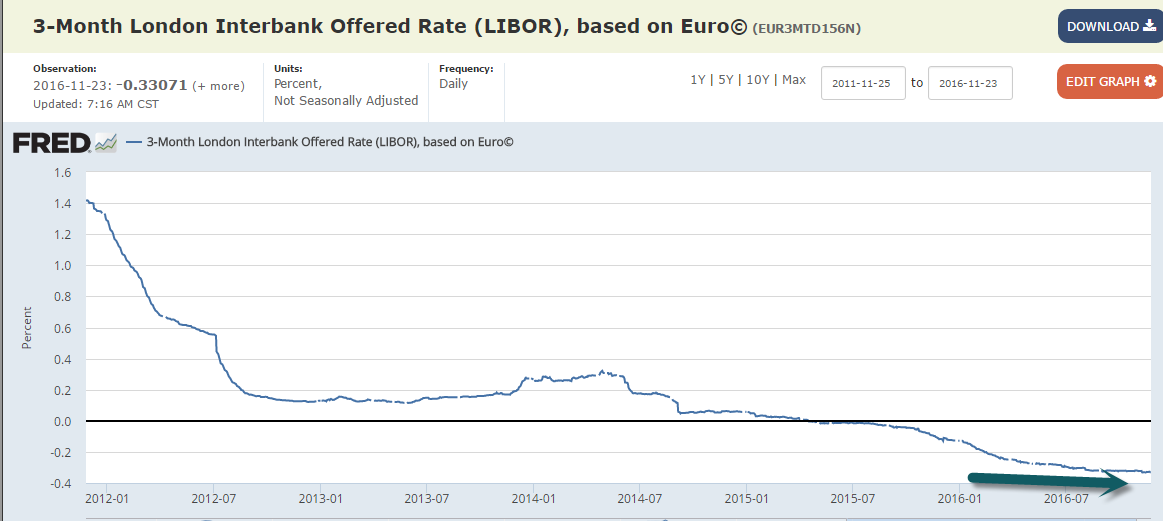
LIBOR or ICE LIBOR (previously BBA LIBOR) is a benchmark rate that some of the world’s leading banks charge each other for short-term loans. It stands for IntercontinentalExchange London Interbank Offered Rate and serves as the first step to calculating interest rates on various loans throughout the world.
LIBOR Definition | Investopedia
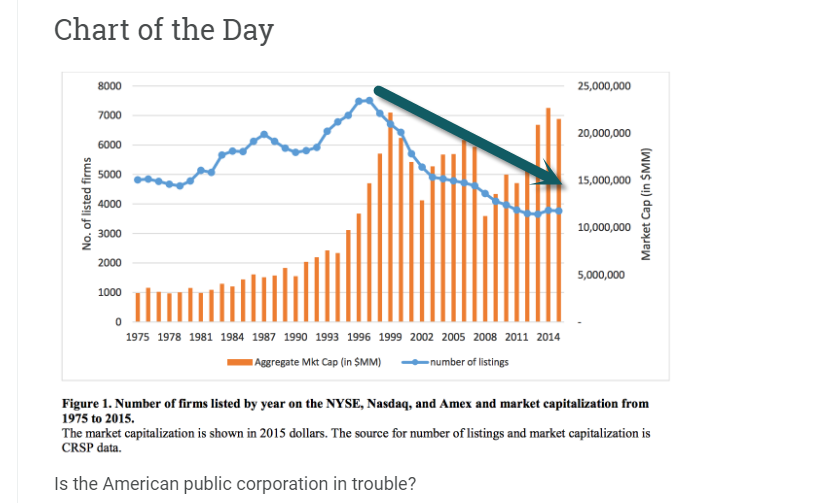
Read Full Academic Paper
https://papers.ssrn.com/sol3/papers.cfm?abstract_id=2869301
From Abnormal Returns Blog
http://abnormalreturns.com/2016/11/30/wednesday-links-emotional-strengths/
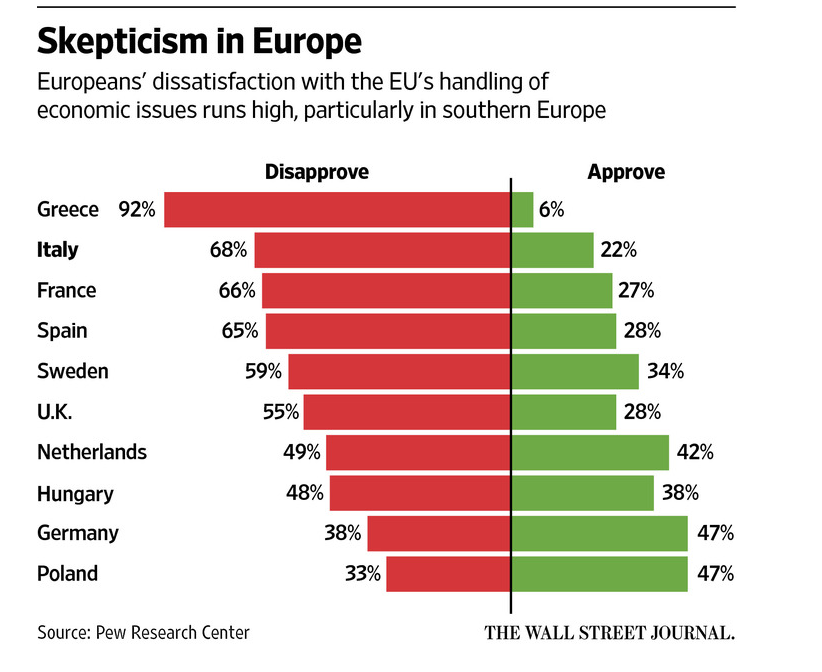
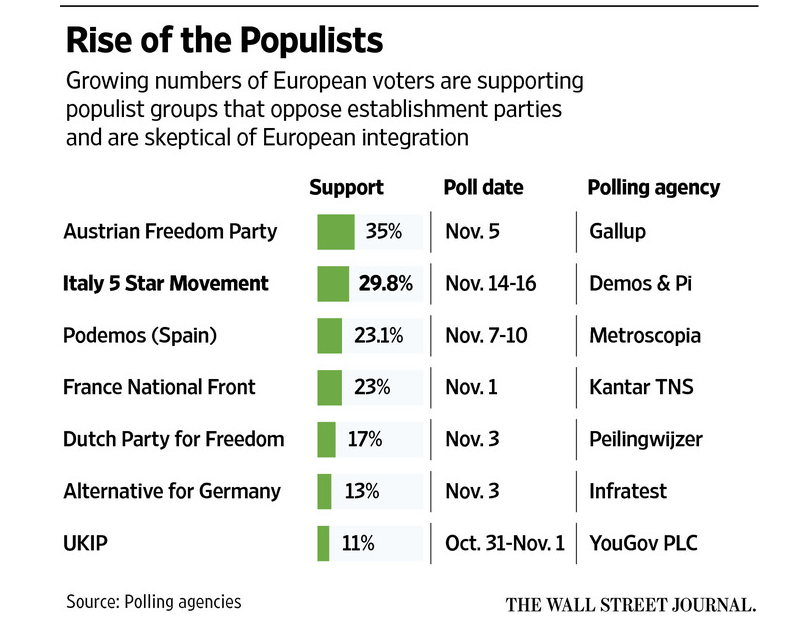
Read full story on Italians losing jobs in furniture manufacturing and car production.
http://www.wsj.com/articles/italy-the-next-stop-on-populisms-global-march-1480436049
Having a great idea, and assembling a team to bring that concept to life is the first step in creating a successful business venture. While finding a new and unique idea is rare enough; the ability to successfully execute this idea is what separates the dreamers from the entrepreneurs. However you see yourself, whatever your age may be, as soon as you make that exciting first hire, you have taken the first steps in becoming a powerful leader. When money is tight and startup fundraisingis required, stress levels are high, and the visions of instant success don’t happen like you thought, it’s easy to let those emotions get to you, and thereby your team. Take a breath, calm yourself down, and remind yourself of the leader you are and would like to become. Here are some key qualities that every good leader should possess, and learn to emphasize.
Honesty
Whatever ethical plane you hold yourself to, when you are responsible for a team of people, its important to raise the bar even higher. Your business and its employees are a reflection of yourself, and if you make honest and ethical behavior a key value, your team will follow suit.
As we do at CoFoundersLab, one of the largest networks for entrepreneurs online, we try to make a list of values and core beliefs that both you and your brand represent, and post this in your office. Promote a healthy interoffice lifestyle, and encourage your team to live up to these standards. By emphasizing these standards, and displaying them yourself, you will hopefully influence the office environment into a friendly and helpful workspace.
Finessing your brand vision is essential to creating an organized and efficient business, but if you don’t learn to trust your team with that vision, you might never progress to the next stage. Its important to remember that trusting your team with your idea is a sign of strength, not weakness. Delegating tasks to the appropriate departments is one of the most important skills you can develop as your business grows. The emails and tasks will begin to pile up, and the more you stretch yourself thin, the lower the quality of your work will become, and the less you will produce.
The key to delegation is identifying the strengths of your team, and capitalizing on them. Find out what each team member enjoys doing most. Chances are if they find that task more enjoyable, they will likely put more thought and effort behind it. This will not only prove to your team that you trust and believe in them, but will also free up your time to focus on the higher level tasks, that should not be delegated. It’s a fine balance, but one that will have a huge impact on the productivity of your business.
Communication
Knowing what you want accomplished may seem clear in your head, but if you try to explain it to someone else and are met with a blank expression, you know there is a problem. If this has been your experience, then you may want to focus on honing your communication skills. Being able to clearly and succinctly describe what you want done is extremely important. If you can’t relate your vision to your team, you won’t all be working towards the same goal.
Training new members and creating a productive work environment all depend on healthy lines of communication. Whether that stems from an open door policy to your office, or making it a point to talk to your staff on a daily basis, making yourself available to discuss interoffice issues is vital. Your team will learn to trust and depend on you, and will be less hesitant to work harder.
If your website crashes, you lose that major client, or your funding dries up, guiding your team through the process without panicking is as challenging as it is important. Morale is linked to productivity, and it’s your job as the team leader to instill a positive energy. That’s where your sense of humor will finally pay off. Encourage your team to laugh at the mistakes instead of crying. If you are constantly learning to find the humor in the struggles, your work environment will become a happy and healthy space, where your employees look forward to working in, rather than dreading it. Make it a point to crack jokes with your team and encourage personal discussions of weekend plans and trips. It’s these short breaks from the task at hand that help keep productivity levels high and morale even higher.
At Onevest, we place a huge emphasis on humor and a light atmosphere. Our office is dog friendly, and we really believe it is the small, light hearted moments in the day that help keep our work creative and fresh. One tradition that we like to do and brings the team closer is we plan a fun prank on all new employees, on their first day. It breaks the ice and immediately creates that sense of familiarity.
Confidence
There may be days where the future of your brand is worrisome and things aren’t going according to plan. This is true with any business, large or small, and the most important thing is not to panic. Part of your job as a leader is to put out fires and maintain the team morale. Keep up your confidence level, and assure everyone that setbacks are natural and the important thing is to focus on the larger goal. As the leader, by staying calm and confident, you will help keep the team feeling the same. Remember, your team will take cues from you, so if you exude a level of calm damage control, your team will pick up on that feeling. The key objective is to keep everyone working and moving ahead.
Commitment
If you expect your team to work hard and produce quality content, you’re going to need to lead by example. There is no greater motivation than seeing the boss down in the trenches working alongside everyone else, showing that hard work is being done on every level. By proving your commitment to the brand and your role, you will not only earn the respect of your team, but will also instill that same hardworking energy among your staff. It’s important to show your commitment not only to the work at hand, but also to your promises. If you pledged to host a holiday party, or uphold summer Fridays, keep your word. You want to create a reputation for not just working hard, but also be known as a fair leader. Once you have gained the respect of your team, they are more likely to deliver the peak amount of quality work possible.
You want to keep your team motivated towards the continued success of the company, and keep the energy levels up. Whether that means providing snacks, coffee, relationship advice, or even just an occasional beer in the office, remember that everyone on your team is a person. Keep the office mood a fine balance between productivity and playfulness.
If your team is feeling happy and upbeat, chances are they won’t mind staying that extra hour to finish a report, or devoting their best work to the brand.
Creativity
Some decisions will not always be so clear-cut. You may be forced at times to deviate from your set course and make an on the fly decision. This is where your creativity will prove to be vital. It is during these critical situations that your team will look to you for guidance and you may be forced to make a quick decision. As a leader, its important to learn to think outside the box and to choose which of two bad choices is the best option. Don’t immediately choose the first or easiest possibility; sometimes its best to give these issues some thought, and even turn to your team for guidance. By utilizing all possible options before making a rash decision, you can typically reach the end conclusion you were aiming for.
Intuition
When leading a team through uncharted waters, there is no roadmap on what to do. Everything is uncertain, and the higher the risk, the higher the pressure. That is where your natural intuition has to kick in. Guiding your team through the process of your day-to-day tasks can be honed down to a science. But when something unexpected occurs, or you are thrown into a new scenario, your team will look to you for guidance. Drawing on past experience is a good reflex, as is reaching out to your mentors for support. Eventually though, the tough decisions will be up to you to decide and you will need to depend on your gut instinct for answers. Learning to trust yourself is as important as your team learning to trust you.
Inspire
Creating a business often involves a bit of forecasting. Especially in the beginning stages of a startup, inspiring your team to see the vision of the successes to come is vital. Make your team feel invested in the accomplishments of the company. Whether everyone owns a piece of equity, or you operate on a bonus system, generating enthusiasm for the hard work you are all putting in is so important. Being able to inspire your team is great for focusing on the future goals, but it is also important for the current issues. When you are all mired deep in work, morale is low, and energy levels are fading, recognize that everyone needs a break now and then. Acknowledge the work that everyone has dedicated and commend the team on each of their efforts. It is your job to keep spirits up, and that begins with an appreciation for the hard work.
Approach
Not all human beings are the same. A basic concept, but something that is often overlooked. You have cultural perspectives, language barriers, different educational backgrounds, personality traits and varying value systems with which individuals come pre-conditioned that greatly affects how information is processed and interpreted. Some people work well under pressure, others don’t. Some respond best to tough love, others take it personally and shut down. In order to optimize your effectiveness as a leader, you must have the ability to customize your approach on a person by person basis, based on the situation at hand. Your capacity to execute this concept will play a huge role in your ability to get the best work out of your team and other partners along he journey.
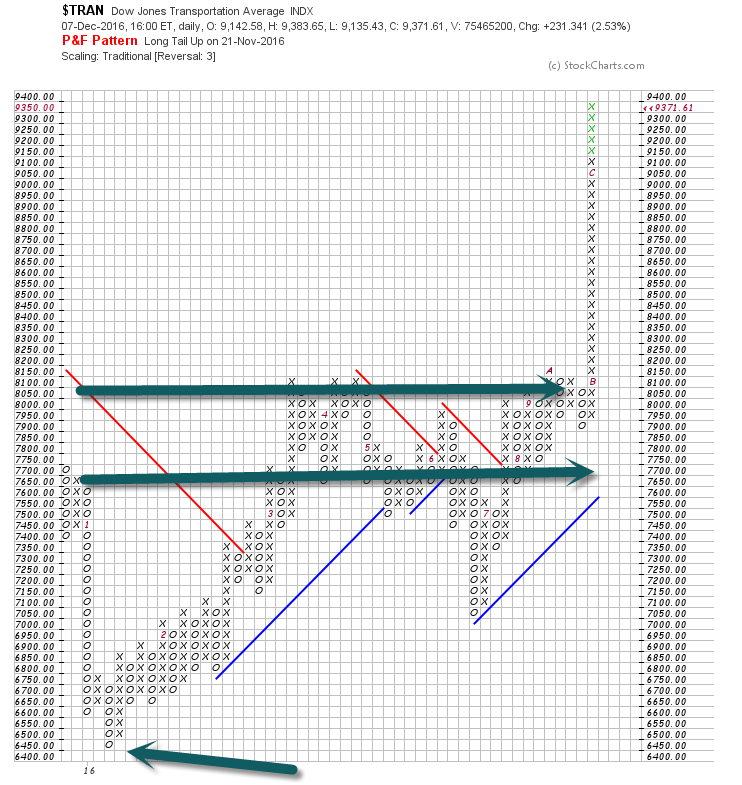
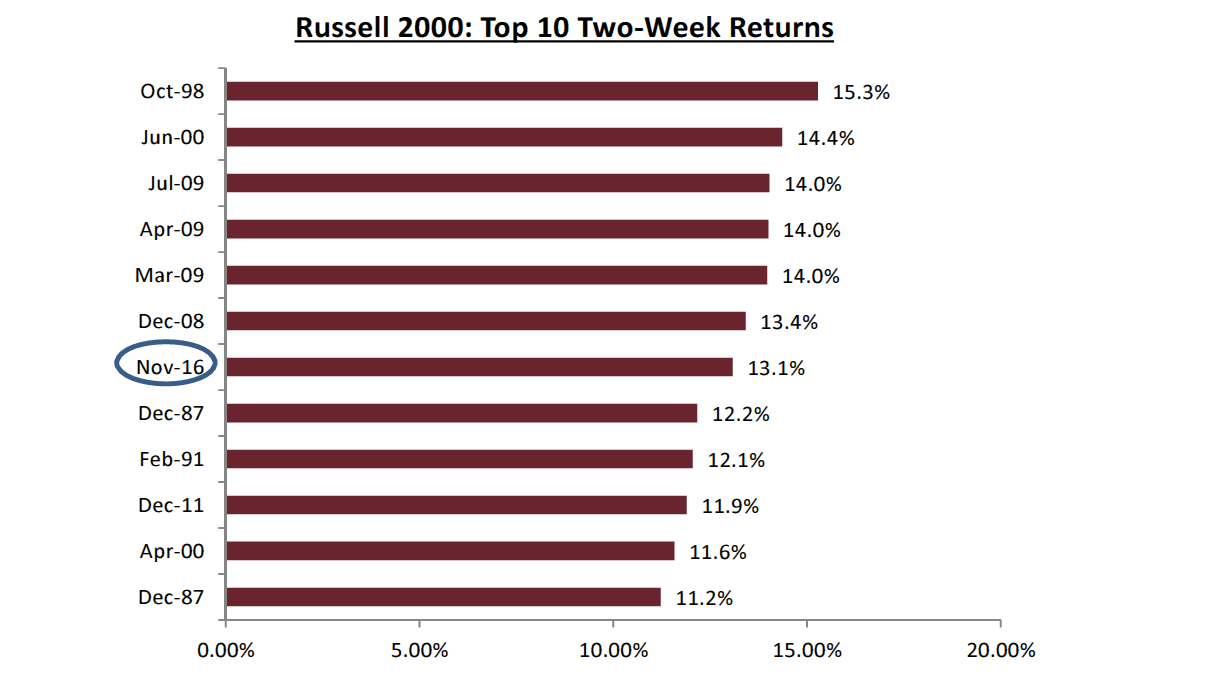
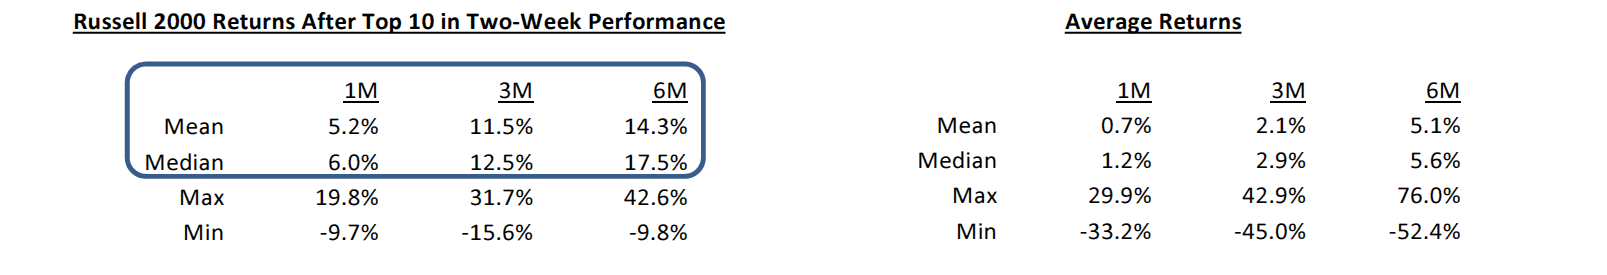
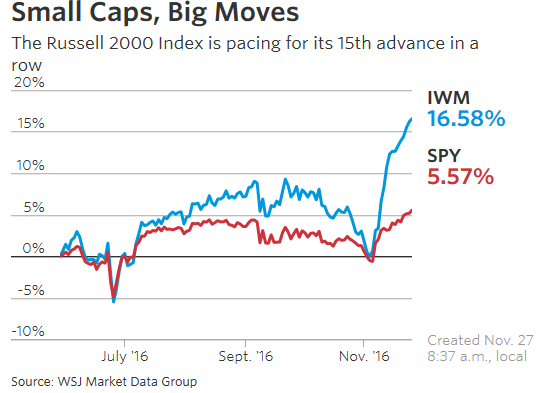
Small company shares on Friday notch their longest winning streak in 20 years on a shortened Black Friday trading session. The Russell 2000 Index rose 0.4% in in the shortened session to book its 15th advance in row. This streak ties a run last seen in February 1996. The longest ever streak, 21, was hit back in 1988. Investors are betting that President-elect Donald Trump will relax regulations, lower taxes and pump money into infrastructure projects. Such policies should benefit small caps more than there larger brethren.
So far, the Russell 2000 has climbed 12.7% since Election Day, compared with an advance of 3.5% for the S&P 500. History suggests that long streaks of gains tend to keep going. On the heels of the 1996 streak of gains, the Russell 2000 was 2.2% higher after the first month and 8.4% higher over the next three
 Thanks to Dave Lutz at Jones for Chart
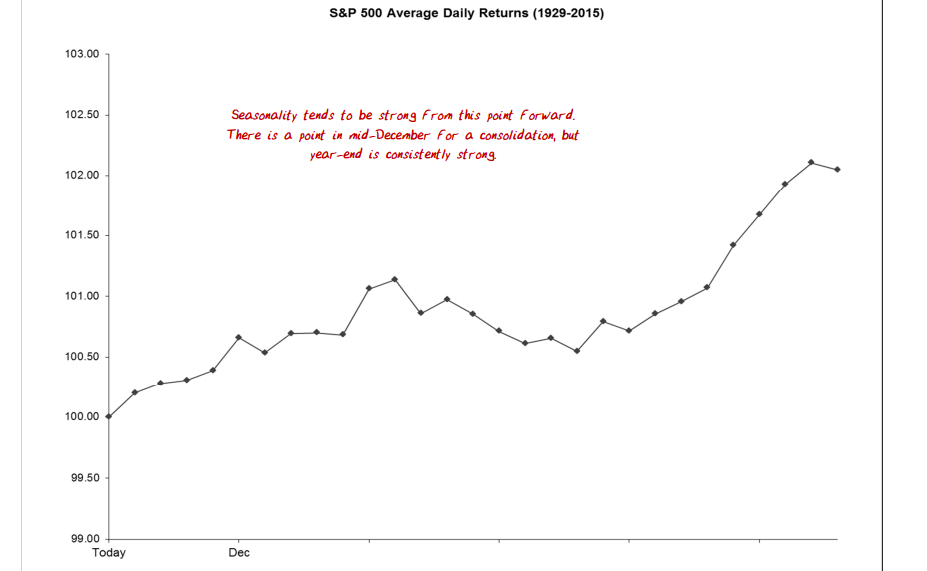
FINANCIALS, TECH AND STAPLES EXCEEDING STREET ESTIMATES:As of last Friday, 474 of the S&P 500 Index companies have reported Q3 earnings, of which 337 have beaten earnings (71.10%) and 100 have missed (21.10%), albeit on lowered estimates. Furthermore, 70 out of 108 companies beat on sales. Thus far, 54 out of the 64 Financials that reported earnings and 54 of the 61 Tech firms that reported earnings have beaten estimates.
Rich Farr, Chief Market Strategist Jim McGovern, Market Strategist info@bluestonecm.com

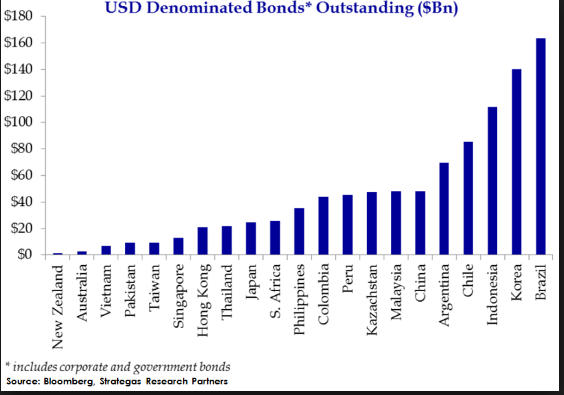
Foreign holdings of U.S. Treasury securities fell for a third straight month in September as China and Japan, the two biggest foreign owners of Treasury debt, both trimmed their portfolios – The Treasury Department says total foreign holdings dropped 0.7 percent to $6.15 trillion in September – China, the top foreign holder of Treasury debt, reduced its holdings 2.4 percent to $1.16 trillion in September – It marked the fourth straight month that China has cut back.
And IWM (small cap) also keeps going, another 83 million shares traded. In the last 4 sessions this fund has traded about 350 million shares and is up 8.9% in the past 5 sessions and the fund has also hit an all-time price high. SPY is up only 1.6% over the same 5 sessions
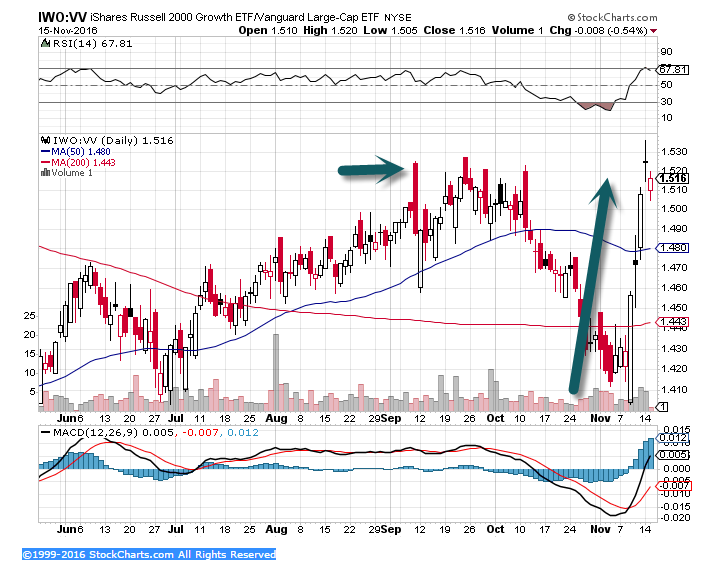
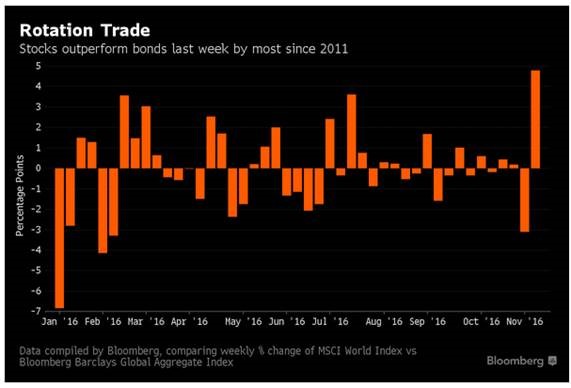
Thanks to Dave Lutz at Jones for chart.
“Indeed it has been said that democracy is the worst form of Government except all those other forms that have been tried from time to time”
– Churchill.
VOTE
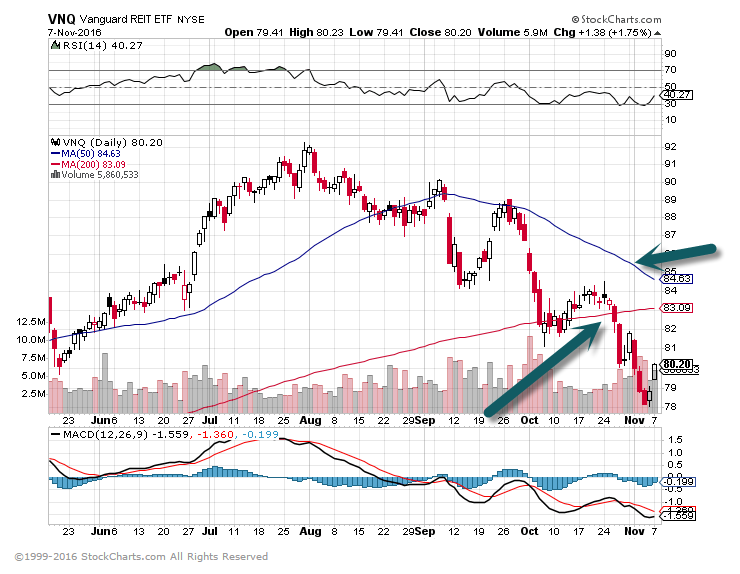
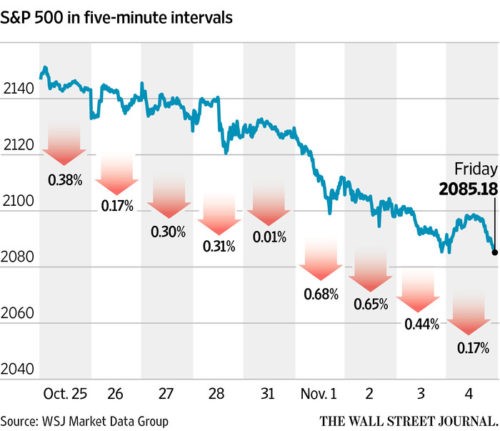
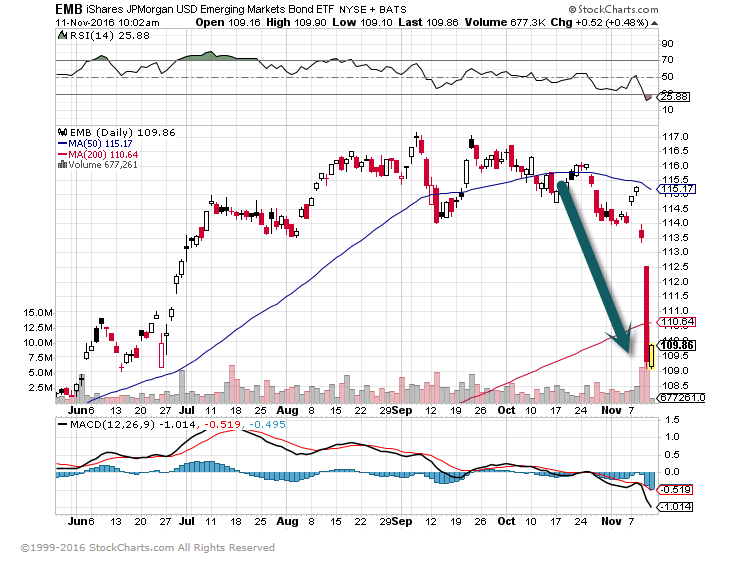
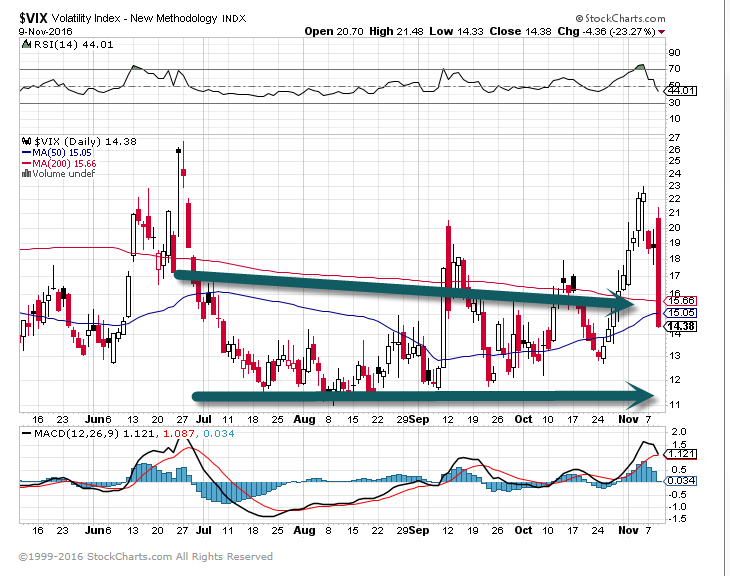
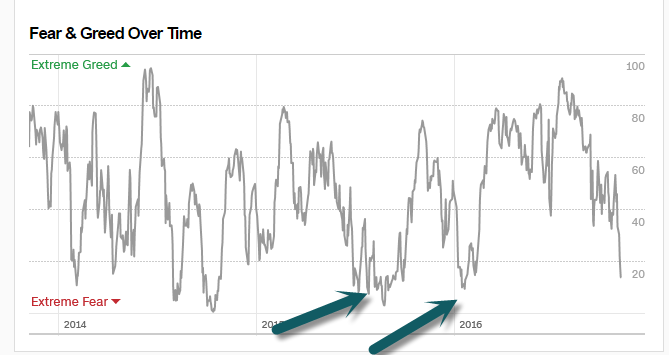
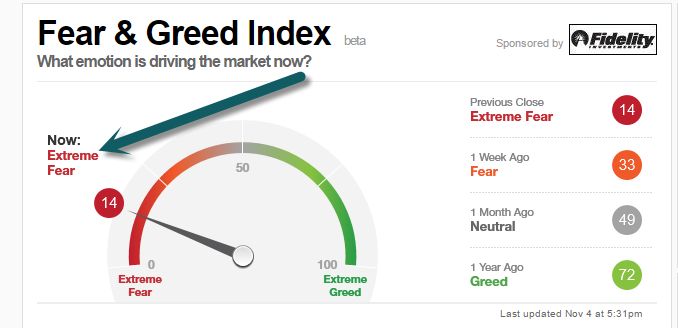 Our last Fear and Greed Lows were Market Bottoms in 2015 and 2016.
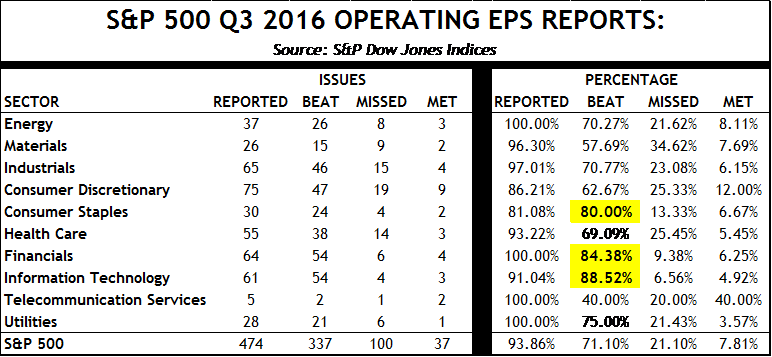
Market Seasonality Notes:
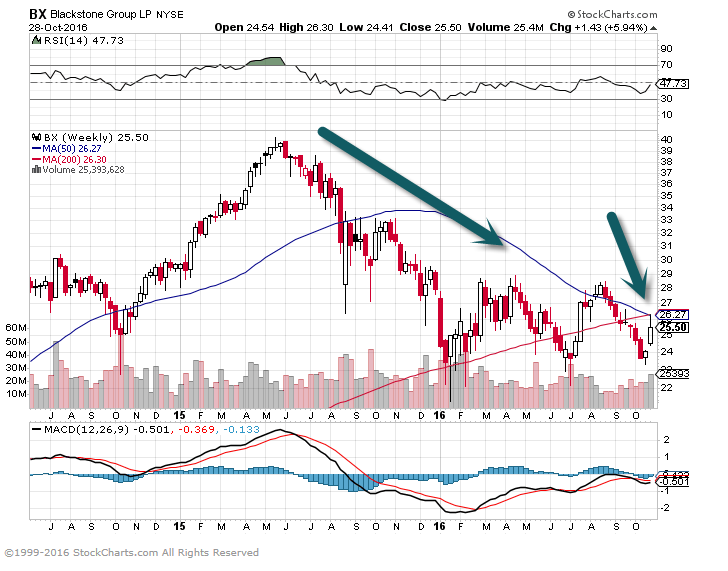
BX-36% off highs…50day thru 200day to Downside on Weekly Chart.
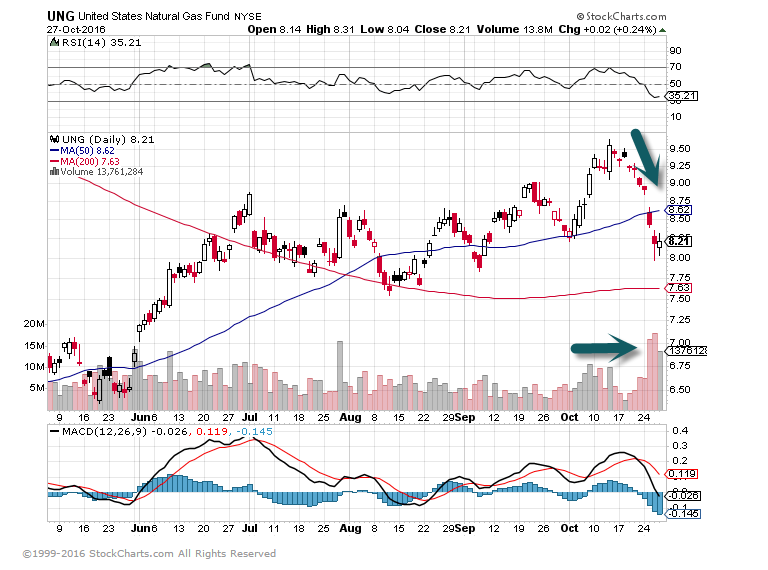
UNG Natural Gas ETF…See High Volume on Second Arrow.
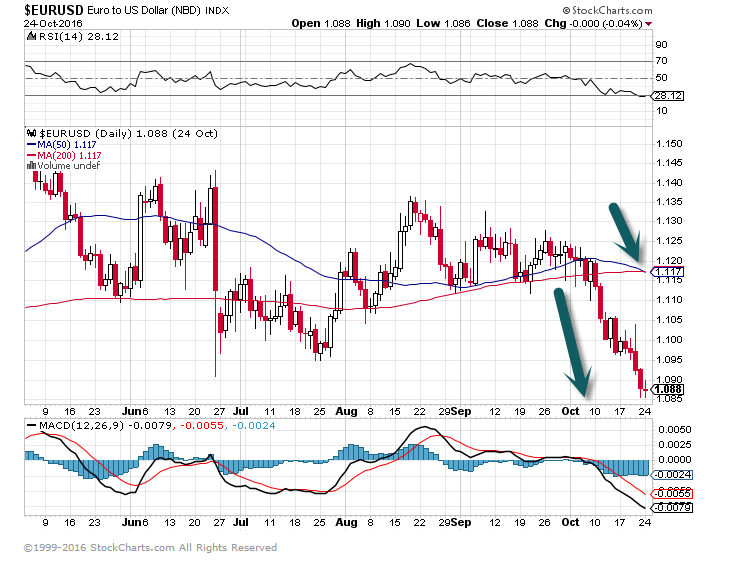
Euro to USD Chart….Breaks Summer Lows…50day thru 200day to downside.
Fund Summary
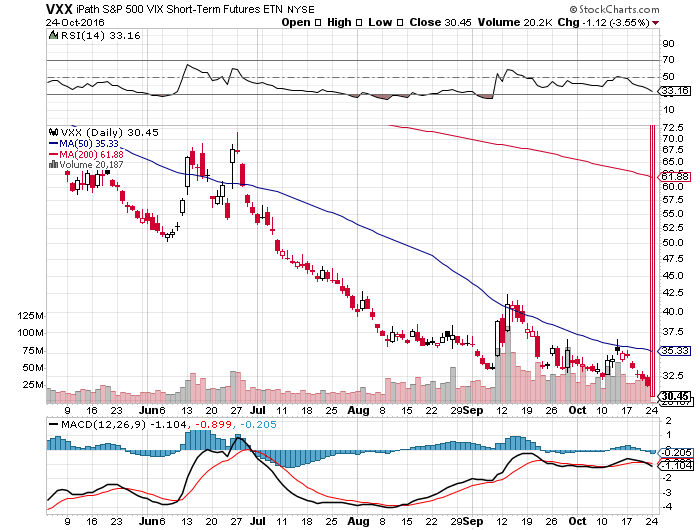
The iPath® S&P 500 VIX Short-Term Futures™ ETN is designed to provide investors with exposure to the S&P 500 VIX Short-Term Futures™ Index Total Return. The S&P 500 VIX Short-Term Futures™ Index Total Return (the “Index”) is designed to provide access to equity market volatility through CBOE Volatility Index® futures. The Index offers exposure to a daily rolling long position in the first and second month VIX futures contracts and reflects the implied volatility of the S&P 500® at various points along the volatility forward curve.
The Good News is that the Rest of the World wants to Spend Like Americans.
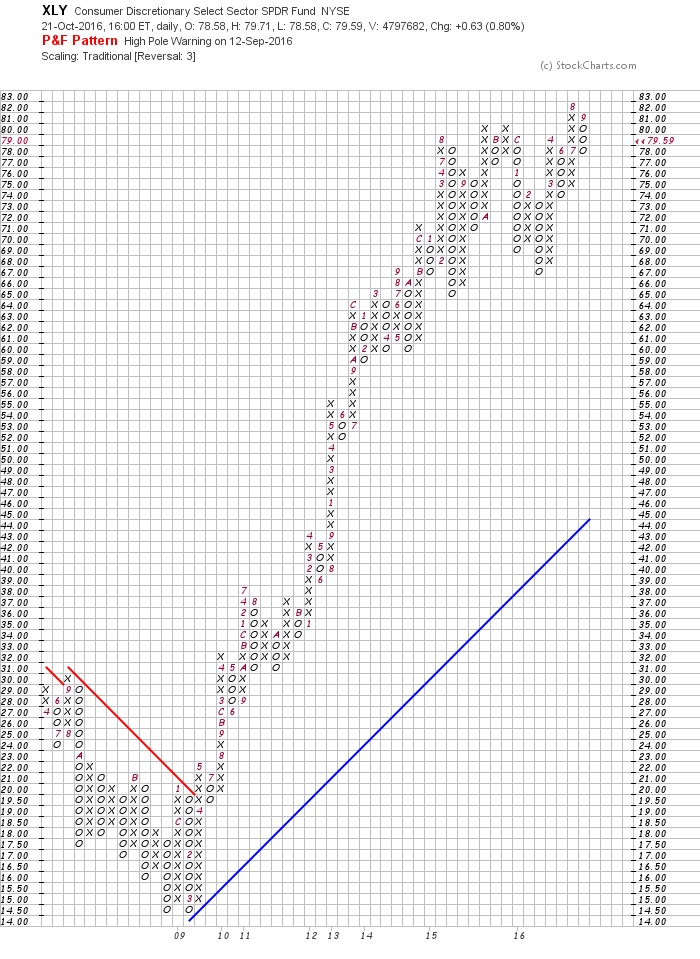
Yes, it’s true that if you’d bought the Consumer Discretionary Select Sector SPDRexchange-traded fund (ticker: XLY) eight years ago, you would have more than tripled your money—and earned more than twice the Standard & Poor’s 500 index’s roughly 150% gain.
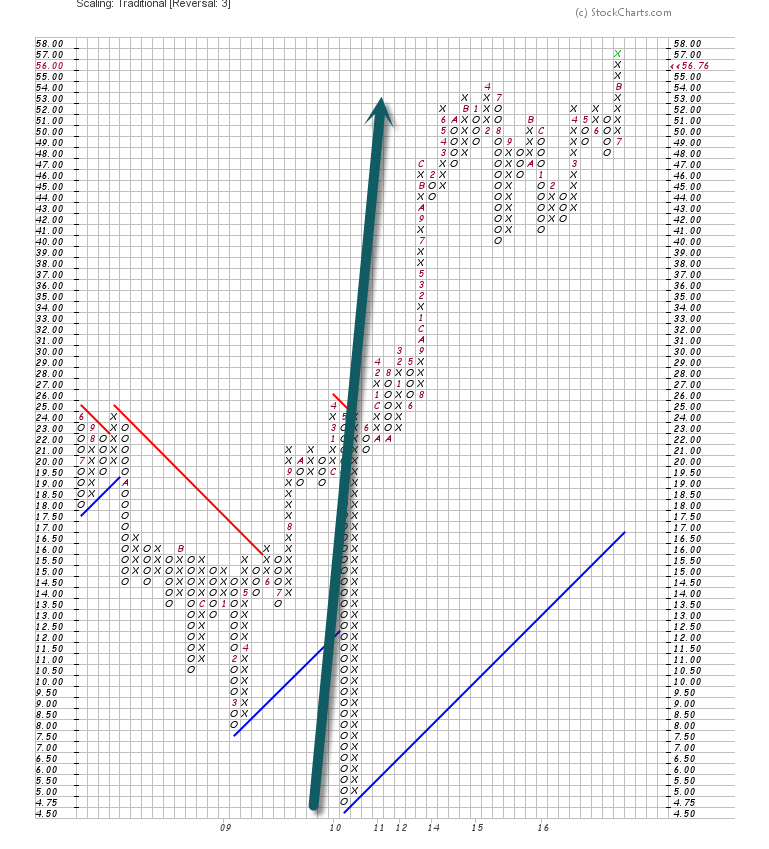
XLY Consumer Discretionary ETF Rally from 2009 Vivid on Point and Figure Chart.
 http://www.renmac.com/
Reach out to Eric for more information on Renmac research
EBoucher@renmac.com
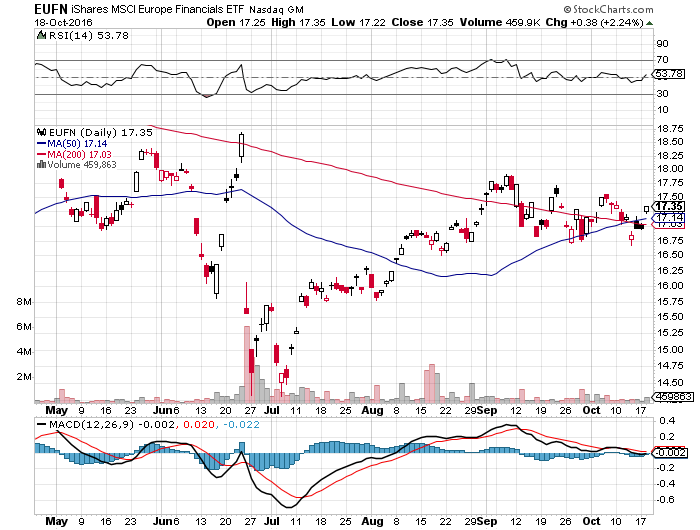
EUFN-Euro Financials ETF—50day thru 200day to upside.
Heading Higher
While most benchmarks have remained low this year, Libor has climbed because of new money-market rules
Source: Bloomberg
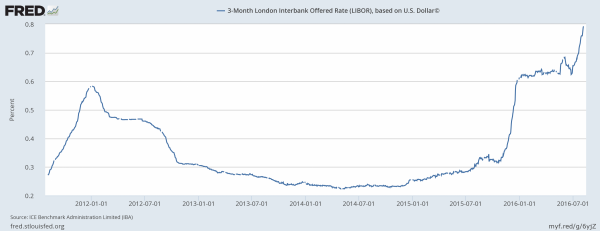
Libor has risen to the highest level since 2009, even though the Fed’s benchmark has stayed constant. Given this discrepancy, it would be logical for companies to rely less on markets that are pegged to Libor and instead issue debt in fixed-rate markets that are more influenced by the fed funds rate.
THREE-MONTH LIBOR0.881%
But that’s not happening. In fact, companies have only accelerated their issuance of floating-rate debt. For example, new U.S. leveraged-loan sales have steadily ticked up in recent months.
Source: Barclays, @joshdigga, @NickatFP
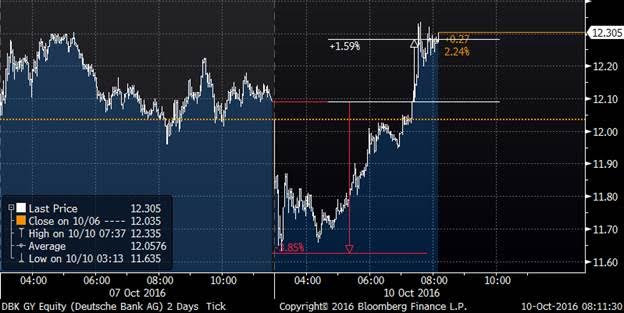
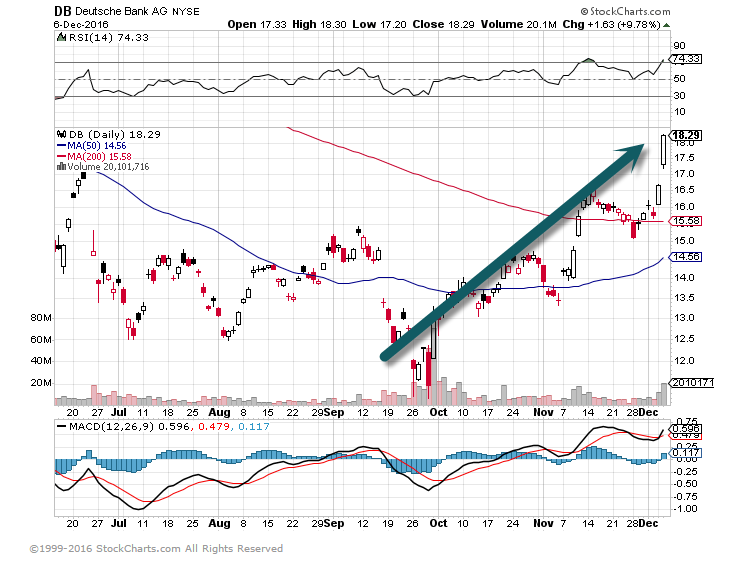
Deutsche Bank AG Chief Executive Officer John Cryan failed to reach an agreement with the U.S. Justice Department to resolve a years-long investigation into its mortgage-bond dealings during a meeting in Washington Friday, Germany’s Bild newspaper reported. “The risks in our derivatives book are massively overestimated,” DB Chief Risk Officer Stuart Lewis said. He said 46 trillion euros in derivatives exposure at Deutsche appeared large but reflected only the notional value of the contracts, while the bank’s net exposure to derivatives was far lower, at around 41 billion euros – DB opened DOWN 4% in Frankfurt, and is now UP 1.6% on the day…
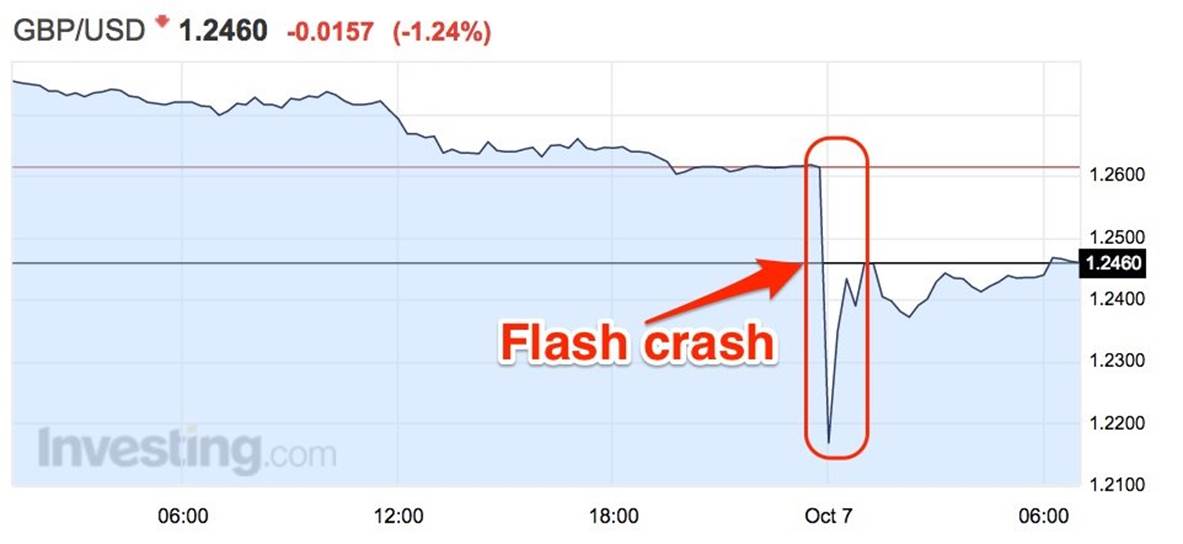
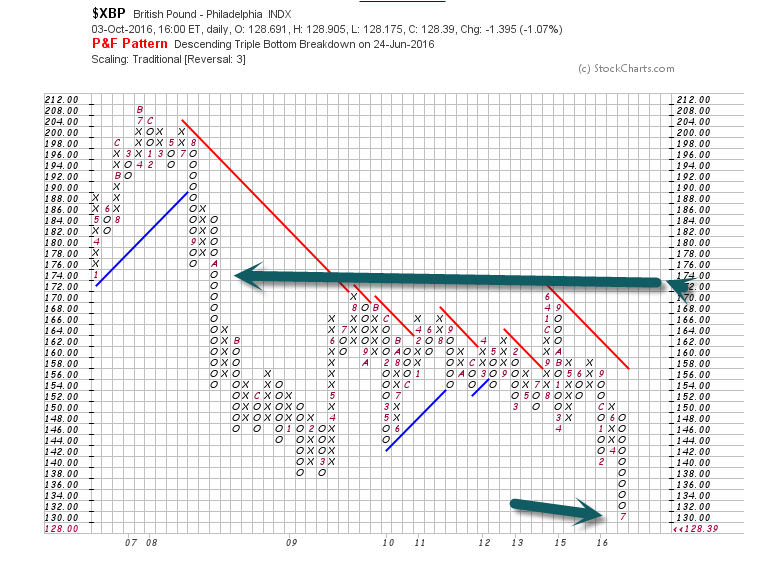
The crash was reportedly triggered by a Financial Times articles stating French President Francois Hollande wanted to be hard on Britain in Brexit negotiations. That pushed the pound lower, triggering some algos to automatically sell. Thin trading volumes meant the impact of this was outsized and created a downward spiral as the slump triggered more algos to sell.
Kathleen Brooks, Research Director at City Index, says in an email on Friday morning: “Apparently it was a rogue algorithm that triggered the sell off after it picked up comments made by the French President Francois Hollande, who said if Theresa May and co. want hard Brexit, they will get hard Brexit.
“These days some algos trade on the back of news sites, and even what is trending on social media sites such as Twitter, so a deluge of negative Brexit headlines could have led to an algo taking that as a major sell signal for GBP. Once the pound started moving lower then more technical algos could have followed suit, compounding the short, sharp, selling pressure.”
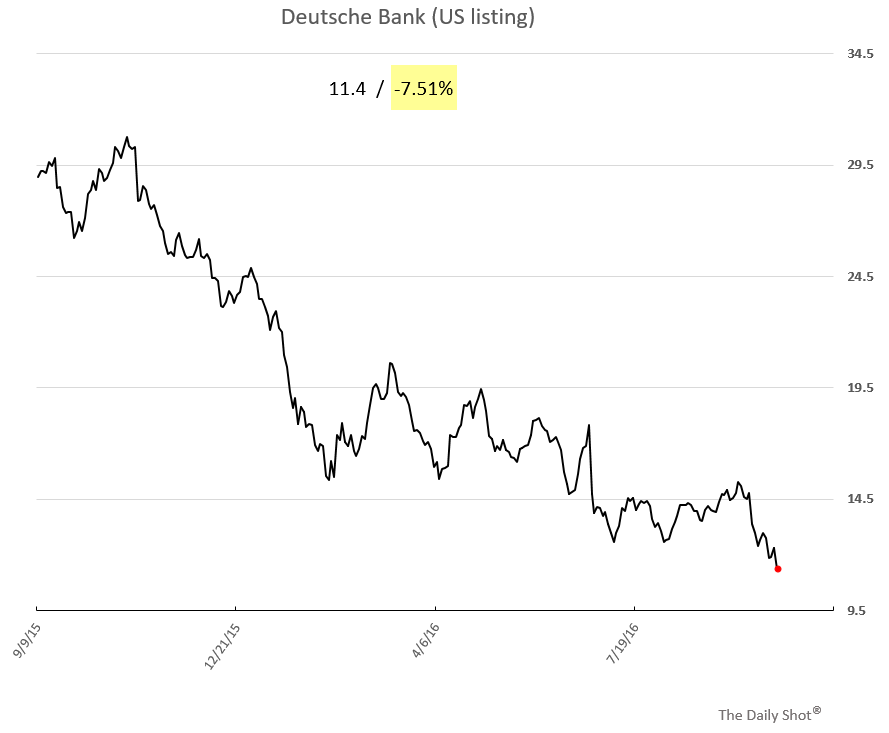
Deutsche shares sold off sharply in US trading.
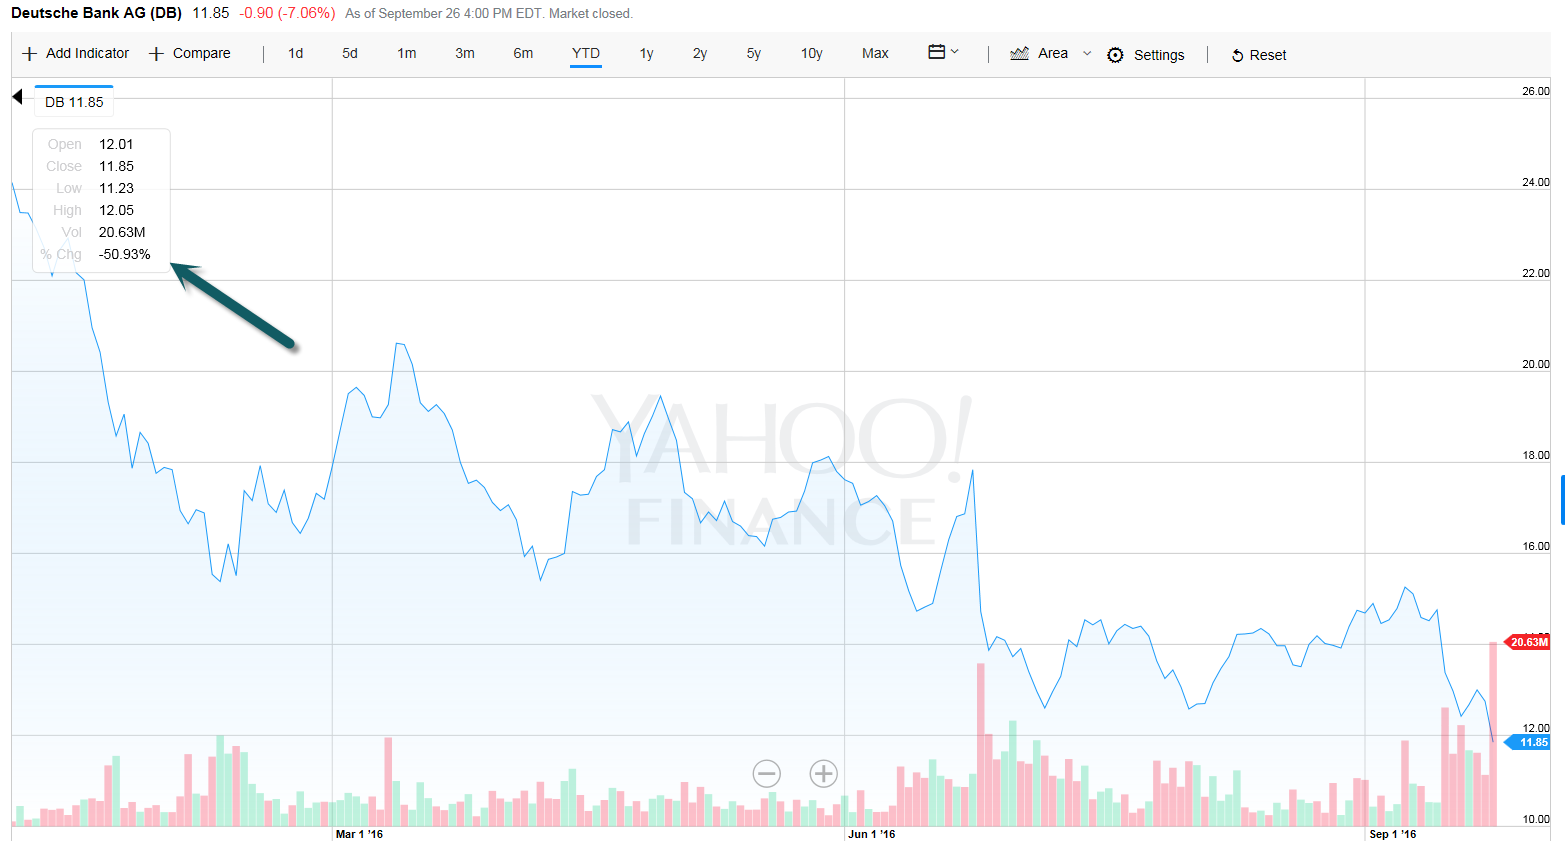
Moreover, the implied volatility on US-listed DB shares spiked to multi-year highs.
It may have been the world’s largest IPO in two years, but shares of Postal Savings Bank of China hit the Hong Kong market like a wet firecracker after the lender raised $7.4B, but priced the deal near the bottom of its marketing range. The lukewarm start comes as investors remain cautious on the outlook for the Chinese banking industry, battling with mounting bad debts amid a slowing economy.

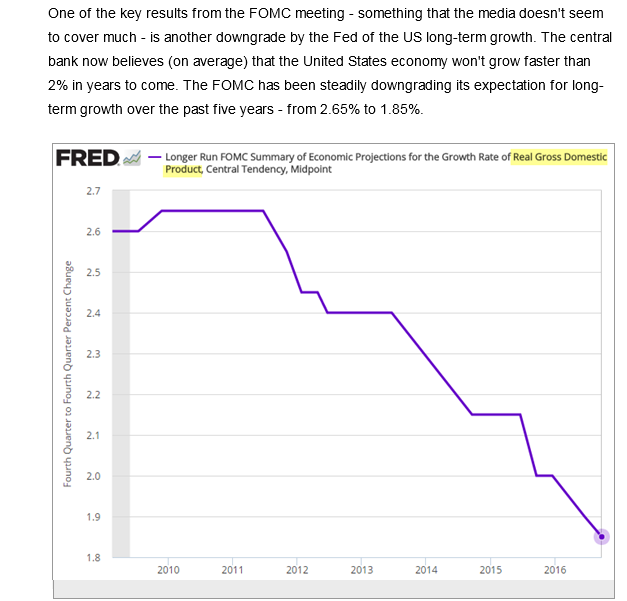
Indeed, LIBOR rates continue grinding higher and the TED Spread has widened sharply…3 month Libor up 145% off low base.
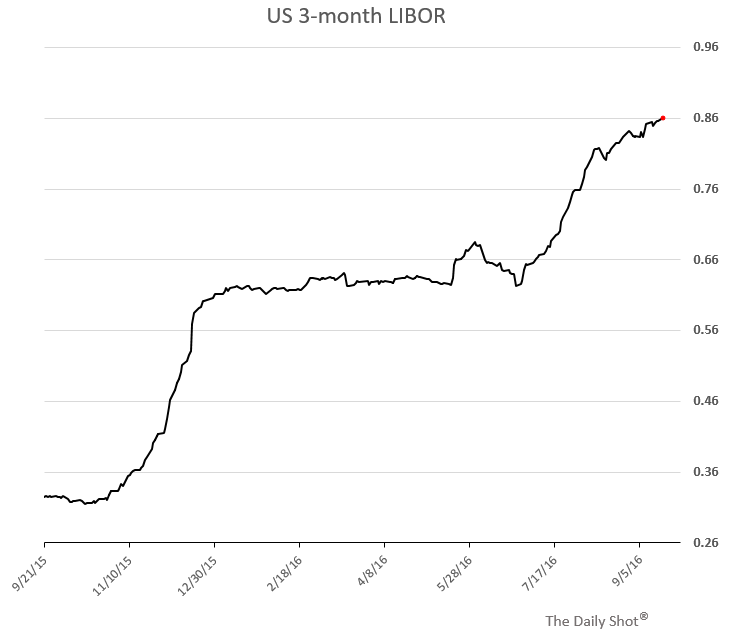
EEM Stopped at 200day …Red Line on Weekly Chart.
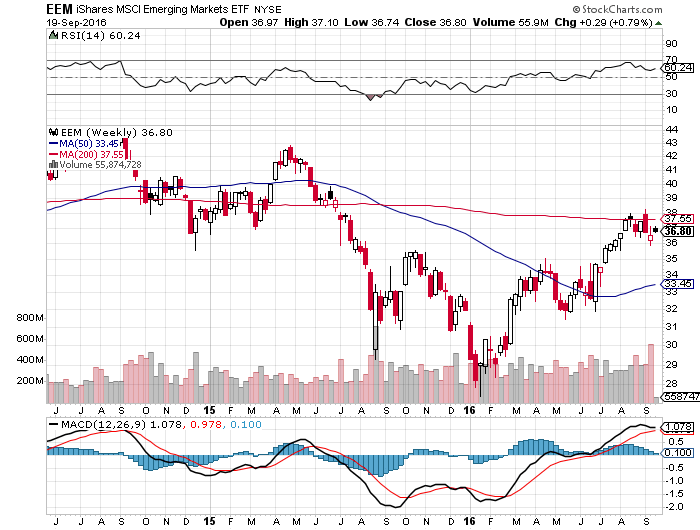
TNX-10yr. Yield Chart.
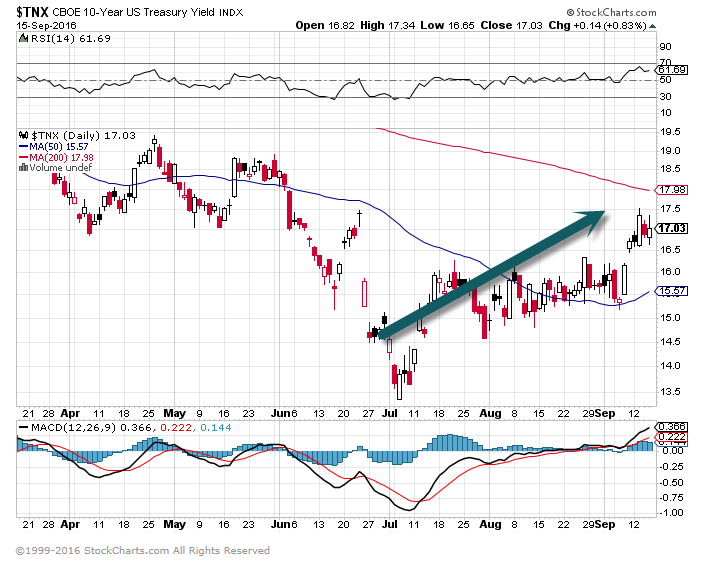
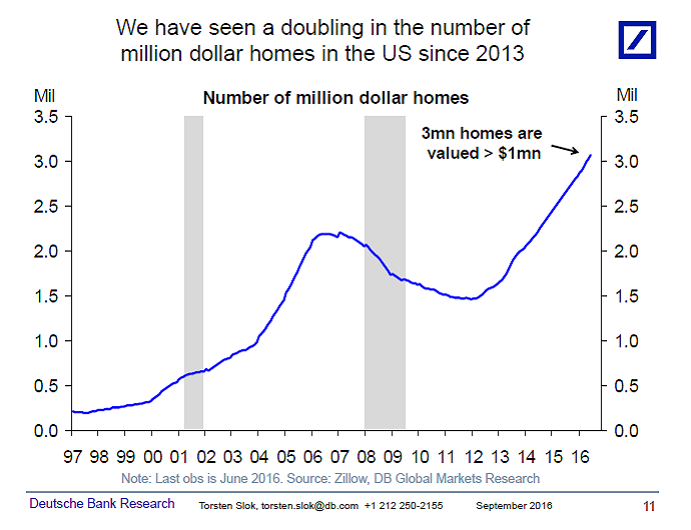
The outlook for consumer spending is significantly supported by the increase in home prices seen over the past three years, see chart below.
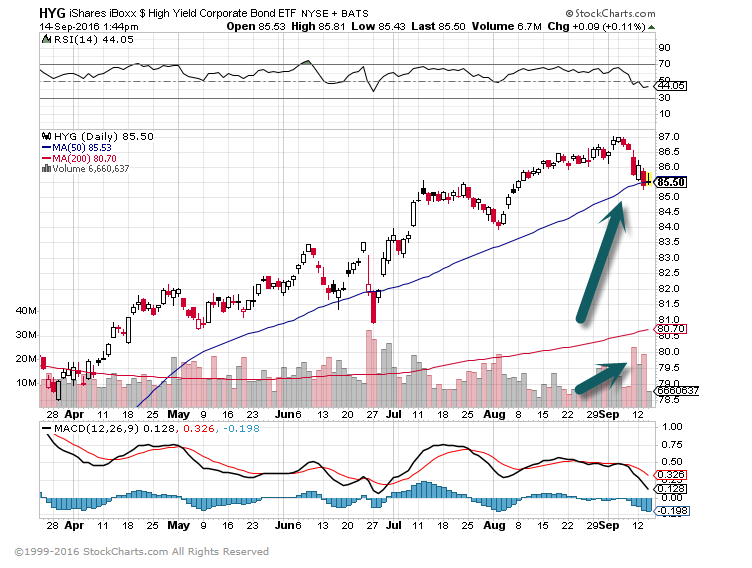
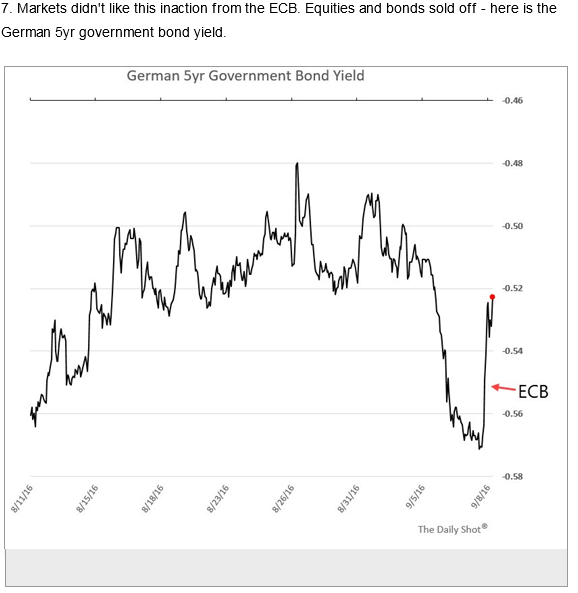
Global equities are also lower after the European Central Bank held interest rates at record lows and refrained from adding new stimulus. While President Mario Draghi said the ECB was looking at options to continue its money-printing program, investors were looking for more immediate action, including an extension or expansion of the current plan, or at least clearer hints of future actions.