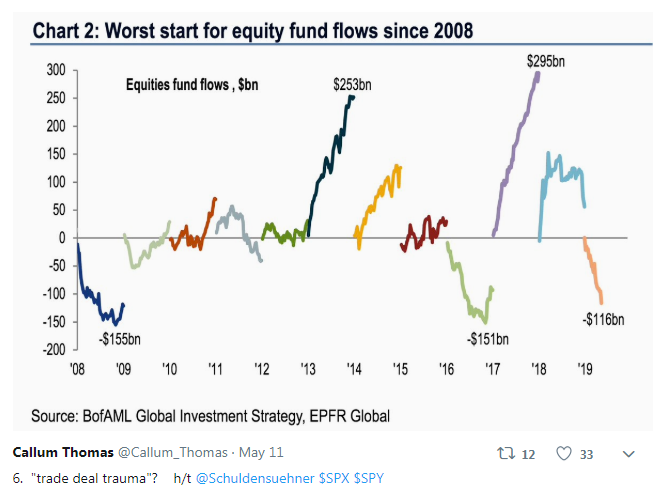
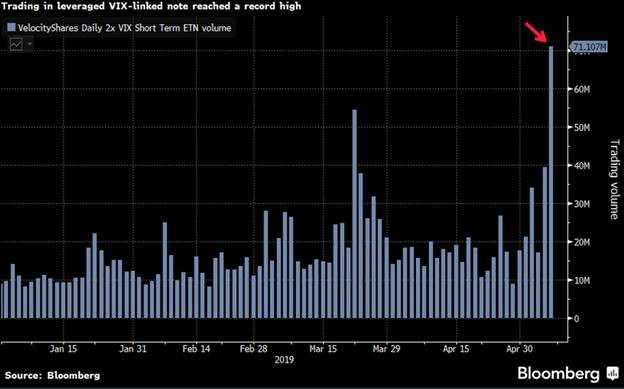
Shares
outstanding in long-volatility ETPs are at record highs
Sheer size
of VIX short contracts still shy of 2019 peak
Bearish bets on stock volatility are close to a record
high, raising investor concern that the market is ripe for turmoil. There’s a more
benign explanation.
Futures linked to the measure of S&P 500’s implied
volatility, known as the “fear gauge”, tend to move inversely to equities. The
net non-commercial position — long contracts outstanding less short positions
— sank to minus 187,948 last week, its lowest level ever.
That valuation still seems bubblicious; a 1% yield on a bond is
analogous to a stock with a price/earnings multiple of 100. With a high P/E
stock, you’re betting on big growth down the road. A bond returns only face
value at maturity, assuming it’s paid off as promised.
The drop in Austria’s century bond’s price to 168 from 210 still
qualifies as a bona fide bear-market decline of 20%. Brigden’s price target is
for a further fall, to 143.50. Such price swings typically are associated with
tech stocks, not stodgy government bonds.
None of the negative bond yields (still totaling $12.8 trillion)
would be possible without European Central Bank policies, Brigden points out.
“The ECB brought European yields down by two policies; quantitative easing (a
pseudo fiscal policy) and negative rates (punishing thrift to boost asset
prices).” Those policies may be reaching their limits, however.
Not only is the ECB close to running out of bonds to buy, in the
case of German and Dutch debt, he writes, but other European monetary
authorities are beginning to question the usefulness of negative policy
rates, notably Sweden’s Riksbank. An
article published earlier this year by
the Federal Reserve Bank of San Francisco also questioned the effectiveness of
the Bank of Japan’s negative interest rates.
As earnings continue to roll in this earnings season, one interesting dynamic has been the contrast between the beat rates of companies based upon the share of revenues that come from abroad versus the US. Using data from our International Revenues Database to gauge international exposure and our Earnings Explorerto get third-quarter earnings results, so far this earnings season, the beat rates for companies with more than half of their revenues generated within US borders have held up much better than those with a majority of revenues coming from abroad. Heading into this week, 74.3% of companies with a greater domestic focus have reported EPS above analyst forecasts while only two-thirds of those with a more international focus have beaten estimates. That is a shift from what has typically happened so far in 2019 and illustrates the impact that the strong dollar has had on results.
As shown in the chart below, the current picture is nearly the exact opposite of where things stood a year ago when more than 74% of internationals were reporting EPS above analyst estimates. In regards to sales, although companies with domestic heavy revenues have generally seen higher beat rates, the spread between domestics and internationals has widened to more than 5 percentage points this quarter.
While this could be a result of multiple factors ranging from analysts potentially overestimating global demand to trade, the dollar is also likely a key factor. For large-cap US companies which often have multi-national exposure, movements in the currency markets often have large impacts on corporate results. For that reason, it’s extremely important for investors to know where the companies they own have the greatest exposure. One great tool to track revenue exposure is our International Revenues Database. If you don’t already have access, start a two-week free trial to Bespoke Institutional to unlock access to all of our interactive tools today!
BIG SPLASH– Earnings are making their biggest
splash in the stock market in years – Investors are sharply bidding up
the shares of companies that beat expectations—and appear more willing to
overlook some of the misses—helping to pull the stock market out of its recent
lull. More than three-quarters of the 358 companies in the index that
reported through Friday have beaten estimates. And 66% have risen in subsequent
trading sessions, a five-year high.
Shares of companies that topped
forecasts rose an average of 2% in the two days after reporting results,
beating the five-year average of 1%, according to data compiled by FactSet. Those that
fell short have averaged a 2.1% pullback, below the half-decade average of 2.6%, WSJ reports
1.Venture Capital Raised for Firms That Are Not Profitable
Second Highest Ever.
• Venture
capital and private equity funds have been selling. Of the $42 billion raised
via offerings, $29 billion of it was for firms that were not profitable. This
is the second-highest in at least 25 years. The only year that showed a greater
percentage was 86% in 2000. If they are unloading losing companies, that tells
us that they do not want to hold such companies during tough times. Cycles Research Early Warning
Serviceby Cycles Research
1. Amazon Stock..Cost of Shipping Jumps 46% Year Over Year….Stock Never Made New Highs From 2018
Amazon earnings fall for first time in more
than two years, stock drops in late trading
Amazon’s spending on
one-day delivery and other initiatives sends profit down year-over-year for
first time since 2017, forecast calls for even more spending in holiday quarter
Johannes Eisele/AFP/Getty Images
Amazon.com Inc. has
spent more than $1 billion this year to reduce the amount of time it takes to
deliver packages to Prime customers, and expects a $1.5 billion hit in the
holiday season.
Olsavsky
said in the call that the fourth quarter will see even larger costs from
one-day delivery efforts.
“So, as
we head into Q4 we’ve added what’s just nearly $1.5 billion penalty in Q4
year-over-year for the cost of shipping, which essentially is transportation
costs, the cost of expanding our transportation capacity, things like adding
additional roles and shifts in our warehouses,” the Amazon CFO said.
Amazon’s worldwide
spending on shipping jumped 46% year-over-year in the third quarter to a record
$9.6 billion, more than a half-billion dollars over what Amazon spent in the
busier holiday season a year ago. The company, which cut back on hiring a year
ago after absorbing the Whole Foods workforce and hiring quickly in 2017, also
increased its total employee count by 22% to 750,000 people. Amazon added
nearly 100,000 employees just in the third quarter, according to Thursday’s
release, which Baird analyst Sebastian deemed the “most surprising metric” in
the report.
The earnings outlook in the U.S. is
darkening, but the view from developing markets is perking up. The ratio of
earnings estimates between the S&P 500 and the MSCI Emerging Markets is at
the lowest since early August. Optimism of an end to the trade war
is sending EM stocks and currencies toward their second monthly advance.
Now that new
home sales have reached a new cycle high (in June), I’d like to update a couple
of graphs in a previous post (most of this from an earlier post).
For the economy, what we should be focused on are single family starts
and new home sales. As I noted in Investment and Recessions “New Home
Sales appears to be an excellent leading indicator, and currently new home
sales (and housing starts) are up solidly year-over-year, and this suggests
there is no recession in sight.”
For the bottoms and troughs for key housing activity, here is a graph of Single
family housing starts, New Home Sales, and Residential Investment (RI) as a
percent of GDP.
1.3Q
Earnings Preview….Energy and Tech Biggest Projected Declines.uu
Higher input and labour costs are
expected to have further crimped profit margins. The average net profit margin
is expected to fall to 11.3 per cent in the third quarter from 12.1 per cent in
the same quarter last year, according to FT – Energy is poised for the
biggest drop in earnings after a fall in US crude prices in the third quarter.
The tech sector, caught up in the US-China trade war, is next with EPS
projected to fall by more than one-tenth, according to FactSet. Revenues are
estimated to increase an anaemic 0.3 per cent.
This week’s fund flow numbers from the Investment Company Institute showed that the long, steady rotation from equity mutual funds and exchange traded funds to fixed income funds has continued. As shown below, the spread between equity fund flows and fixed income fund flows has reached a net reading of -$165.9bn over the last three months; that’s among the largest net flow out of equities and into bonds since the data starts.
Fixed income isn’t the only place that retail has been moving allocations to. As shown in the chart below, 13 week commodity fund flows have been among the largest of the periods since the data for ETF and mutual funds combined begins.
Investors are loading up on cash. That’s not a good
sign.-By Andrea Riquier
An analysis from research firm
DataTrek, drawing on fund flow data from the Investment Company Institute,
shows that there was $3.4 trillion in U.S. money market funds as of October 2.
That’s about 14% higher than at the end of 2018, and has risen nearly every
week since May.
“What’s strange about this recent influx of capital is that
short-term rates have been declining all year,” DataTrek founder Nicholas Colas
wrote. Money market funds “are seeing strong inflows in 2019 even as 2-year
yields have been cut in half,” he added.
The paranoia around
presidential elections is hitting record levels, we better stop and listen to
what’s going down. We spend a big portion of our life listening to
storytelling. As kids, parents and teachers tell us stories. As
adults the news media is about storytelling, investing is about storytelling,
and nothing paints a better story than politics. I may be early with this
letter as the presidential election is more than a year away but it’s possibly
shaping up to be the ultimate scary story for investors.
As I write this letter, it is
increasingly looking like a Trump vs. Warren election and a Trump impeachment
investigation, which may be the ultimate binary event for American
voters. Never in history has an election been so important except for
every other election in history. Most of my conservative friends thought
the world would end if Obama got elected and most of my liberal friends thought
the world would end if Trump got elected.
If you made either of those
investing bets based on politics, your wallet is probably lighter. The
chart below shows that Obama obviously did a better job with the economy.
Actually this would be a false assumption, as Obama took office when the
S&P was trading at generational low valuations. The single best
predictor of future returns is where valuations are today, the next President will
not have the luxury of beginning his or her term with low valuations.
The
U.S. labor market keeps chugging along, despite signs of weakness in other
pockets of the U.S. economy.
Nonfarm
payrolls rose 136,000 in September, and July and August payrolls growth were
revised up by 45,000. The 12-month average payrolls change climbed to 179,000
including Friday’s data, still slightly higher than the expansion average.
Overall,
the September jobs report showed hiring has been steady, defying recent worries
of economic weakness after surprisingly weak manufacturing and services surveys
were released earlier this week. Other labor-market measures also look healthy.
The unemployment rate fell to 3.5% in September, a new cycle low, and initial
jobless claims are still subdued.
Wage
growth slowed notably last month, though, hinting that inflationary pressures
could be moderating. As shown in the LPL Chart of the Day, average hourly
earnings growth fell to 2.9% year over year, the slowest pace since July 2018.
5.First
Sign of Peak Jobs? Job Openings Rolling Over.
There was no movement in average hourly
earnings (AHE) relative to the prior month; while the year-over-year growth
rate slowed from 3.2% to 2.9%. The weakness was concentrated in managers’ pay;
while production/non-supervisory wages, although softer for the month, are up
3.5% year-over-year. Wages historically follow corporate earnings, with about a
one-year lag; so the significant deterioration in profits growth this year
suggests further downward pressure on wages. Indeed, although still high in
absolute terms, job openings have rolled over.
In sum
Employment
releases are generally the most influential economic indicators for
economists—and the stock market—as they guide expectations for consumer
spending, consumer confidence, inflation, and income growth. But they have
taken on even greater importance lately for two reasons:
To gauge whether the weakness
in manufacturing is beginning to bleed into the services/consumer segments
of the economy.
The Fed has moved from a
predetermined path for interest rates to a data dependent path, with “full
employment” representing half of the Fed’s dual mandate (the other being
“price stability”).
Welcome to the Working Week: A Look at the State(s) of Employment
Hong Kong
is in the middle of a political crisis. Millions of citizens have been
protesting since June, sparked by an extradition bill that would have allowed
for criminal suspects in Hong Kong to be extradited to mainland China.
Opponents argued that the bill would put Hong Kong citizens at risk of unfair
and violent treatment by Chinese officials. And they worried the bill would
give China greater control over Hong Kong, which China has wanted for a long time.
Vanguard Group, the investment advisor with assets under
management (AUM) in excess of $5 trillion and the largest provider of mutual
funds in the world, is testing a new currency trading platform, reports Bloomberg
citing a person familiar with the matter. Based on blockchain technology, the
peer-to-peer (P2P) platform will enable asset managers to trade currencies with
one another directly, bypassing the need for investment banks.
Business Insider Intelligence
-The FX platform would mark one of the most significant
deployments of blockchain in financial services. Amid considerable hype around
blockchain’s potential to upend existing processes across the financial
services value chain, major players have invested billions on the technology.
Yet, despite those investments, firms have struggled by and large to move their
early experiments to large-scale enterprise operations. If Vanguard can
successfully navigate some of the challenges that have stymied this promise —
from scalability to interoperability — it would act as a litmus test for the
wider industry’s stumbling blockchain ambitions.
-And while success isn’t guaranteed, Vanguard’s pioneering
legacy gives it a considerable advantage. The company has been a major
driver of change within the investment space since it launched in 1975. And
it’s continued this streak in recent years: For instance, while a number of
banks have struggled to take
advantage of the hype around robo advisors, Vanguard’s bucked that trend
significantly. As of this year, the $115 billion AUM it’s amassed via its robo
platform makes it the largest robo advisor, per Robo-Advisor
pro. This ability to leverage emerging technology and trends within the
industry to increase its share of the market makes Vanguard’s efforts to upend
currency trading markets a serious threat to incumbent banks.
8.Blackstone
CEO Stephen Schwarzman: Even billionaires have problems
The chief executive of the world’s largest private equity
company on Trump, bubbles and whether he is on a farewell tour
Danilo Agutoli
By Chris Newlands and Selin Bucak
Even billionaires have problems that money cannot solve. Today,
Stephen Schwarzman’s is traffic.
The chairman, chief
executive and co-founder of Blackstone arrives 15 minutes late for our meeting
at the private equity giant’s London headquarters in Mayfair.
“So many cars on the road,” says
the 72-year-old, whose personal wealth is north of $18bn, according to Forbes.
“It’s a real problem, sorry.”
Schwarzman, who set up Blackstone with Peter Peterson, the
former chairman of now-defunct US bank Lehman Brothers, is in town to promote
his new book What It Takes: Lessons in the Pursuit of Excellence.
One of the lessons cited in
the book — essentially a how-to guide to being rich and successful — is
punctuality. Page 55 reads: “Be on time. Punctuality is the first indicator of
how much thought and preparation you have put into an interview.”
Schwarzman apologises again,
adding: “Have you read the book?”
Lots of people have.
The great and the good have lined up to provide endorsements,
including Jack Welch, the former chief executive of General Electric; Ray
Dalio, the co-chairman of investment company Bridgewater Associates; and
Henry Kissinger, the former US secretary of state.
Even Mark Carney, the
governor of the Bank of England, has taken the time to provide a quote for the
front cover (“This story literally has what it takes”) — a striking move
for the head of an independent British institution, which further illustrates
Schwarzman’s pull.
“Mark told me he has never
ever endorsed a book in his career,” says the American businessman, who hails
from Philadelphia. “I have known him for some time. I sent him the book and he
said: ‘This is terrific, I’m very happy to say what I think.’ You saw what he
wrote. I was very happy about that.”
Schwarzman is used to
rubbing shoulders with the most influential people in politics and finance.
After Donald Trump was elected president in 2016, Schwarzman became head of his
short-lived advisory council, which included Larry Fink, the chief
executive of BlackRock, and Jamie Dimon, the chairman of JPMorgan. The group
was disbanded in 2017 in the wake of the president’s controversial remarks
about a white supremacist rally in Charlottesville, Virginia.
Reports suggest Schwarzman’s
relationship with Trump, who he has known for more than 40 years, has become
frayed. Schwarzman had to distance himself last week from comments made by
the president about the son of former vice-president Joe Biden. Trump is facing
an impeachment inquiry after urging Ukraine to investigate a family member of
the veteran Democrat, who is running for president.
Would Schwarzman like to see
Trump get another term in the White House? “It isn’t relevant what I
think,” he says, sidestepping the question. “We have now, much like you in the
UK, real divided politics. It looks today, on the Democratic side, that we have
Joe Biden and then Elizabeth Warren and Bernie Sanders. And on the Republican
side, there is really only Donald Trump.
“Like any election outcome,
it all depends on who somebody is running against. The Democrats will be running
against Trump, but they as a group are going further and further left. The
further they go left, the more difficult it will be for the Democrats to win.”
We return to safer ground:
the nuts and bolts of the private equity market. Schwarzman and Peterson
launched Blackstone in 1985 following daily breakfasts at New York’s Mayfair
Hotel, where he and the former Lehman Brothers chief executive hashed out
their plan to create a business that would eventually become the biggest and
most influential private equity firm in the world.
In 1987 they raised their
first fund at $800m. Today, Blackstone has $545bn in assets, with its
biggest vehicle, Blackstone Capital Partners VIII, raising an eye-watering
$26bn, making it the largest buyout fund ever.
“When we started the firm we
had $400,000 — $200,000 from me, $200,000 from my partner, Pete, and last
week the company was [valued at] $60bn,” he says.
It raises the question of
whether there is too much money sloshing around the market and whether that
cash can be put to good use. “I’ve been asked that since 1992,” he says. “The
returns have stayed pretty good over the last 25-30 years regardless of peaks
of markets and real collapses.
“When you are managing more
money, the way historically we’ve always dealt with that is you just do bigger
deals. We have never found, despite that question over the decades, that the
amount of capital per se is the issue.
“The nice thing about our
industry is that you don’t have to invest the money for six years. If you think
things are high, you don’t have to play, you can wait. For those of us who have
been doing this for most of our careers, we are used to cycles, it doesn’t
bother us.”
This is not a bubble
compared with 2006/07, he adds. “That was a bubble. I said it was a bubble
then, and it was. Prices now are relatively high, but there is not that frenzy
that happens, because the people who manage the capital have been through the
global financial crisis, and once you’ve lived through that you are not anxious
for a repeat.”
In the book Schwarzman
writes that he does not “feel a day over 38”, the age he was when he launched
Blackstone. It is true that sitting across the table, Schwarzman has a youthful
energy about him for a man born in 1947 but the book, which was two years in
the making, certainly has the feel of a farewell tour.
“No, not at all,” he says
flatly, and we are ushered out of the room ahead of his next meeting.
Envestnet
CEO Jud Bergman could hold court on any of the technological disruptions
affecting financial planners, having co-founded the technological services
giant for the wealth management industry.
But few things could animate him
more than the mere mention of chess.
“I recently had the privilege of
moderating an event panel that included Jud, and I’ll never forget someone
pulling me aside and saying, ‘I’ll bet you anything Jud finds a way to talk
about the game of chess no matter what question you ask him,’” said Riskalyze
CEO Aaron Klein.
“Sure enough, it wasn’t more than
an answer or two into the panel that he started talking about how chess
strategy could teach us something about where financial services was
headed.”
Bergman, 62, and his wife, Mary
Miller-Bergman, 57, were killed in a car collision in San Francisco on Oct. 3,
the company said in a statement. The couple were in a taxi that was hit head-on
by a Volkswagen Cabrio going the wrong way on northbound Highway 101, according
to The Associated Press. The woman driving the other vehicle was intoxicated,
the AP said.
“Today, our entire industry
mourns this devastating loss. Jud’s vision and innovation forever changed the
face of the financial services industry, and will continue to do so for years
to come,” Klein said.
“Looking back, I’m not sure
there’s anyone who has made quite as many chess moves in financial technology
as Jud has, and each move has driven the industry forward and elevated the
profession of financial advice.”
Envestnet’s board appointed Bill
Crager, president of Envestnet and chief executive of Envestnet Wealth
Solutions, as interim chief executive officer. It also appointed Ross Chapin,
the lead independent director of Envestnet’s board, as interim chairman of
Envestnet’s board.
“On behalf of our board of
directors, management team and employees, we extend our deepest sympathies to
Jud and Mary’s family. As Envestnet’s founder, Jud was a remarkable leader whose
vision, brilliance and drive built the foundation for Envestnet’s success.”
Miller was the founder of Hanover
Hill Wealth Advisors in Chicago.
Under Bergman, Envestnet
underwent a remarkable trajectory of growth, from startup in 1999 to a tech
provider able to repeatedly execute multimillion-dollar acquisitions, many
leading brands themselves. The stack of technology Bergman assembled has become
so formidable some predict the company will become a custodian.
Financial planning software firm
MoneyGuidePro was among the latest. Envestnet purchased the Silicon Valley data
aggregator Yodlee in 2015 for $660 million.
At the time, industry leaders
questioned the strategy behind the acquisition, says Joe Duran, CEO of United
Capital. Envestnet stock fell after the announcement, but Bergman was willing
to endure short-term pain to improve his company and the advisors it supports,
Duran says.
“He knew what advisors
needed and was determined to shift the company to support a really complete
suite of services,” he said.
Duran too recalled Bergman’s love
for the game of strategy.
“We both play chess, but never
got the chance to play together,” Duran says. “I suspect he would have beaten
me.”
Industry leaders were stunned by
the news and many sought to convey just how much Bergman did for them on a
personal and professional level.
“I have watched him grow
Envestnet from a startup to one of the leading firms in the industry,” said
Joel Bruckenstein, founder of the Technology Tools for Today conference series.
“Despite his many achievements,
he always had time for others. He was extremely kind to me. He was an industry
visionary and leader. His intellect was impressive as was the breadth of his knowledge.
I will miss him as an industry leader, but more importantly as a friend.”
Orion CEO Eric Clarke expressed a
similar sentiment. “Jud and I had dinner on several occasions and I always had
great respect for the business he built and the way that he built it,” Clarke
says. “Jud had an unprecedented ability to see things that others just didn’t.
“Envestnet is in great hands with
Bill [Crager], but the entire industry will miss Jud terribly,” Clarke says.
Bergman was leaving behind a
legacy of leadership in technology, says Craig Iskowitz, founder and CEO of
fintech consultancy Ezra Group.
“How many different ways can
you say innovator or visionary? How can you explain how one person changed our
industry in ways that we’re just coming to understand? How can you talk about
one CEO who changed how every wealthtech firm approaches the market? There are
no words.”
Many took to Twitter to share
their thoughts.
“This quaint, intimate community
in which we work is never more evident than times like this; when we suffer the
unfortunate loss of one of our own, and this one is profound,” wrote Brian
Hamburger, founder of the Hamburger Law Firm and consulting firm MarketCounsel.
Earlier this year, Bergman
acknowledged in an interview with Financial Planning that
his chess analogies probably needed an update, reflecting on the challenge that
chess champion Gary Kasparov undertook when he played against IBM’s supercomputer
Deep Blue.
With the technological changes
happening on multiple fronts, the best advisors were now engaging in a game of
3-D chess, Bergman said.
“Experts plus machines deliver
better outcomes than experts or machines alone,” he said. “This is a framework
from which advisors, we think, ought to look at how they render advice, how
they manage portfolios and manage client relationships going forward.
“What are
the areas that computer software can do better and what are the areas that the
human expert can do better? This is what Gary Kasparov understood and what the
best advisors understand. There are some things that humans do better than
computers and vice versa.”
Most
of us grew up hearing the mantra “Don’t be a quitter,” and we’ve
internalized it to the point where we feel guilty if we don’t finish a book
that’s boring us to death. Our parents weren’t entirely wrong in saying
that persistence is necessary for success, but
sometimes quitting is the most effective course of action. Whether it’s a
failed project, a thankless job, or a doomed relationship, quitting can be a virtue.
“Quitting is leading too.” –Nelson Mandela
As
it turns out, some of us are really good at knowing when to quit, while others
have a hard time getting “unstuck.” Research from the University of
Rochester found that people are motivated by either “approach goals” or
“avoidance goals.”
Those
who fall into the approach camp are motivated by challenges and don’t waste
time trying to solve problems that simply don’t have a feasible solution. In
other words, they know when to quit.
People
motivated by avoidance goals, however, worry a lot more about failing. They
want to avoid failure at all costs, so they keep plugging away at things, long
after logic suggests it’s time to move on. This is typically a much less
productive way to work.
Knowing
when to quit is a skill that can be learned. If you tend to be stuck on things
long after it’s obvious that what you’re doing isn’t working, you can train
yourself to do better. You just need to practice quitting. Thankfully, life
provides plenty of opportunities to do this. Here are some things we should all
quit doing.
1. Quit doubting yourself. Confidence plays a huge role in
success. Hewlett-Packard conducted an interesting study of the process through
which people applied for promotions at the company. Women, it turned out, only
applied when they met 100 percent of the criteria for the job they wanted,
while men applied when they met 60 percent of the criteria. The researchers
postulated that one of the (many) reasons men dominated the upper echelons of
the company is that they were willing to try for more positions than females
were. Sometimes confidence is all it takes to reach that next level. The trick
is, you have to believe you can. If you doubt yourself, it won’t work. Faking
confidence just doesn’t produce the same results.
2. Quit putting things off. Change is hard. Self-improvement
is hard. Scrounging up the guts to go for what you want is hard, and so is the
work to make it happen. When things are hard, it’s always easier to decide to
tackle them tomorrow. The problem is that tomorrow never comes. Saying you’ll
do it tomorrow is just an excuse, and it means that either you don’t really
want to do it or you want the results without the hard work that comes along
with it.
3. Quit thinking you have no choice. There’s always
a choice. Sure, sometimes it’s a choice between two things that seem equally
bad, but there’s still a choice. Pretending that there isn’t one makes you a
victim who is voluntarily taking on a mantle of helplessness. To play the
victim, you have to give up your power, and you can’t put a price on that. To
succeed at the highest level, you have to quit giving your power away.
4. Quit doing the same thing over and over again and expecting a
different result. Albert Einstein said that insanity is doing the same thing
and expecting a different result. Despite his popularity and cutting insight,
there are a lot of people who seem determined that two plus two will eventually
equal five. The fact is simple: If you keep the same approach, you’ll keep
getting the same results, no matter how much you hope for the opposite. If you
want different results, you need to change your approach, even when it’s
painful to do so.
5. Quit thinking everything is going to work out on its own. It’s tempting
to think that it’s all going to work out in the end, but the truth is that you
have to make it work. This has many implications. Don’t expect your boss to
notice when you’re ready for a promotion, don’t expect your colleague to stop
sloughing work off on you if you’re always willing to do it, and don’t think
that anyone is going to stop walking all over you as long as you allow it.
Everything is not going to magically work out on its own; you
have to be proactive and take responsibility for yourself.
6. Quit saying yes. Every yes you utter is a tradeoff. By
saying yes to one thing, you’re saying no to something else. Saying yes to
staying late at work, for example, might mean saying no to the gym or to time
spent with your family. Research conducted at the University of California, San
Francisco, showed that the more difficulty you have saying no, the more likely
you are to experience stress, burnout, and even depression. Saying no is indeed
a major challenge for many people. No is a powerful word that
you should not be afraid to wield. When it’s time to say no, avoid phrases such
as I don’t think I can or I’m not certain. Saying
no to a new commitment honors your existing commitments and gives you the
opportunity to successfully fulfill them. When you learn to say no, you free
yourself from unnecessary constraints and free up your time and energy for the
important things in life.
Bringing It All Together
There
are dozens of ways we get in the way of achieving our full potential. We doubt
ourselves, we decide that something is just too hard, or we tell ourselves that
we’ll worry about it tomorrow. If you really want to succeed–and I mean really
succeed–stop focusing so much on what you should be doing and, instead,
take a really good look at the things you should quit doing.
What other things should people quit doing? Please share your
thoughts in the comments section, as I learn just as much from you as you do
from me.
1.You Call This A Bull Market?-Bespoke Investment Group
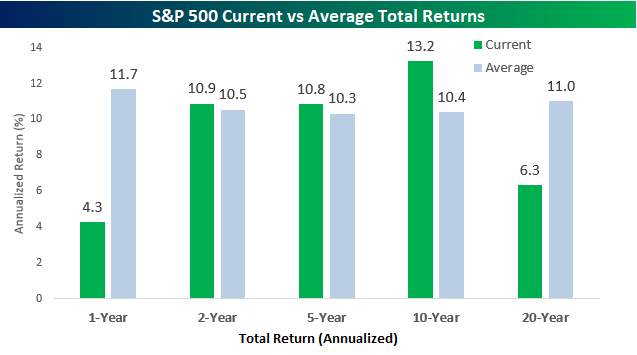
By just about all accounts, investors have been spoiled over the last ten years as the S&P 500 has rallied more than 13% on an annualized basis. However, when you compare returns for the market over the last one, two, five, ten, and twenty years, current returns are hardly at any sort of historical extreme. The chart below compares the S&P 500’s annualized performance on a total return basis to the average annualized return for all similar time frames. Looking just at the last year (through 9/30), the S&P 500’s total return is 4.3%, which is less than half of the historical average one year total return of 11.7%. Looking at two and five-year annualized performance figures, current returns are just modestly above their historical average. While the ten-year annualized return is almost three percentage points above the historical average, the current 20-year annualized gain of 6.3% is well below the S&P 500’s historical average of 11.0%.
1.IPO’s
2019-114 U.S. IPO Pricings-63 Positive Returns.
Follow up to my IPO
comments from last week
Barrons
Amid
the headlines about IPO disappointments, there is a broader takeaway: Investors
have become more discriminating, and that’s good for everyone. “Everything has
changed, and nothing has changed,” says Lise Buyer, founder of Class V Group,
an IPO consulting firm. “Lately, there’s been lots of noise and fireworks, and
hullabaloo about direct listings. But the No. 1 thing is that fundamentals have
not changed. Institutional investors are pretty darned smart when looking at
IPOs, regardless of structure and buzz. Investors will analyze the company, the
prospects for the future, and the price at which they’re being offered the
chance to invest. That has not changed as long as I’ve been in the business.”
S&P 500 sector weightings are important to
monitor. Over the years when weightings have gotten extremely lopsided
for one or two sectors, it hasn’t ended well. Below is a table showing
S&P 500 sector weightings from the mid-1990s through 2016. In the
early 1990s before the Dot Com bubble, the US economy was much more evenly
weighted between manufacturing sectors and service sectors. Sector
weightings were bunched together between 6% and 14% across the board. In
1990, Tech was tied for the smallest sector of the market at 6.3%, while
Industrials was the largest at 14.7%. The spread between the largest and
smallest sectors back then was just over 8 percentage points.
The Dot Com bubble completely blew up the balanced economy, and looking back
you can clearly see how lopsided things had become. Once the Tech bubble
burst, it was the Financial sector that began its charge towards
dominance. The Financial sector’s sole purpose is to service the economy,
so in our view you never want to see the Financial sector make up the largest
portion of the economy. That was the case from 2002 to 2007, though, and
we all know how that ended.
Unfortunately we’ve begun to see sector weightings get extremely out of
whack once again.
Is the market too complacent about the risk of higher oil
prices?
After all, rising prices can limit consumers’ ability to spend
on everything other than gasoline, natural gas, and heating fuel. All those
products become more expensive as oil prices rise. That can be bad for the
economy.
Rising oil prices can also increase headline inflation numbers.
And higher inflation makes it harder for the Federal Reserve to cut interest
rates to keep the economy chugging ahead. That also sounds bad.
Still, crude’s impact on the economy is far less than it used to
be.
Why Oil Prices Don’t Matter for Stocks Anymore-By Al Root
1.Long-Term
Treasury ETF (TLT) Has 2nd Biggest Weekly Drop Ever
Outside of equities, we saw a
massive move higher in Treasury yields this week and a massive drop in Treasury
bond prices. For the 20+ year Treasury ETF (TLT),
this week’s 6.34% drop was its second worst week on record since it began
trading back in 2002.
Below is a look at TLT’s historical weekly
percentage change, and we also show how TLT has performed in the weeks and
months following one-week drops of more than 5% like we saw this week. As
shown in the table, TLT has normally continued lower for a while following big
down weeks. Start a two-week
free trial to one of our three membership levelsto
receive Bespoke’s most actionable ideas.
Prior forays into negative
territory during this cycle (in 2011, 2012, 2013, and 2016) have accompanied
signs of slowing, but have also reflected the broader interest rate
environment. Slower global growth, increasingly accommodative central banks,
and some flight to safety due to trade uncertainty have all conspired to push
rates lower.
The
expected inflation rate implied by 10-year TIPS sits at about 1.5%, low
historically but still higher than the cycle low and well above the near 0% hit
in the heart of the last recession. Slower growth has minimized inflationary
pressure, but over the last three months we have seen a modest pickup in
inflation and wages.
The table below
details SPLV’s portfolio characteristics on a year-by-year basis versus SPY.
Values in red denote underperformance by the low-vol portfolio. The fund’s
lifetime numbers, shown in the gray row at the bottom of the table, are indeed
impressive: a higher average annual return, lower volatility and a resultant
higher Sharpe ratio, along with a positive alpha coefficient and information
ratio.
Within that time
span, however, there’s a lot of, um, volatility in the numbers. In those years
when SPLV’s standard deviation was higher than SPY’s, there was a cascading and
deleterious effect on returns and other portfolio metrics.
So, what’s the
point of all this? Simply put, capture of the low-volatility anomaly is path
dependent. Just because there’s a low-vol product available doesn’t mean you’ll
always derive immediate benefit from its use. Look at the back-to-back
underperformance in the 2012-2013 and 2013-2014 spans. Would you have been
disappointed by SPLV back then? Would you have bailed from the low-vol
strategy?
Many investors,
in fact, did just that. Net outflows mounted in the 2013-2014 period and even
spilled over into the subsequent period, just ahead of a couple of banner
years. And in the 2016-2017 span, SPLV’s net outflows totaled $1.4 billion as
the low-vol ETF significantly lagged SPY.
Good Full Read
When Low-Vol Is Not-Strategy may require some time to pay off. Brad Zigler
| Sep 09, 2019
1.Min
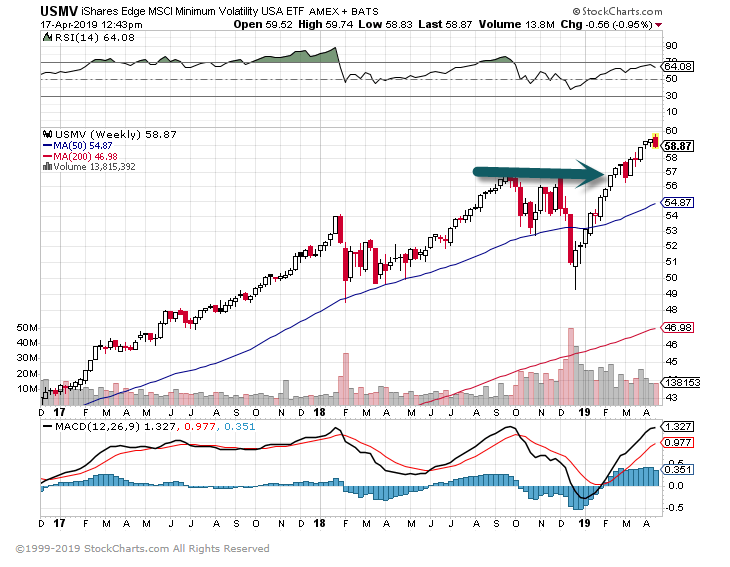
Volatility ETF USMV Second in Flows to S&P….
Barrons
The iShares Edge MSCI Min Vol U.S.A. ETF
(ticker: USMV) has attracted nearly $9.5 billion this year, second only to the
broader and much better known Vanguard
S&P 500(VOO). The iShares ETF has swelled 42% in the past eight months
to $32 billion
The average stock in the iShares ETF trades for 24 times
trailing 12-month earnings, versus 19 for the S&P 500; the ETF overall
trades at a 17% premium to its MSCI benchmark. A recent study from Leuthold
Group found that low volatility stocks, relative to their higher volatility
peers, are 99% more expensive than they have been over time, going back to
1990.
2 Big Volatility ETFs Have Very Different Approaches By Stephen Gandel
1.Stock dividends offer more yield than 30-year Treasury
bond for first time since 2009
Published: Aug 28, 2019 1:41 p.m. ET Occurred only once before in last 40-plus years: Bespoke
By William Watts
Here’s another consequence of the rally in government bonds
that’s sent yields crashing around the globe — U.S. stocks now offer more yield
than the 30-year U.S. Treasury bond.
As the
chart below, going back to 1977, from Bespoke Investment Group highlights, the
Tuesday move marked the first time since the financial crisis that the dividend
yield on S&P 500 index companies SPX, +0.57% has
topped the yield on the long bond TMUBMUSD30Y, -1.14%.
“The only other time in the last 40+ years where we have seen a
similar inversion was for a few months in late 2008 through March 2009 (the low
point of the Financial Crisis),“ Bespoke analysts wrote. “In July 2016 right
after the Brexit vote, the S&P 500 dividend yield came within 0.01% of the 30-year’s
yield, but it couldn’t quite make it higher.”
All in all, the higher dividend yield should make stocks more
attractive.
Bespoke said it was “pretty amazing” to see how many stocks in
the S&P 500 now yield more than the 5-, 10- and 30-year Treasurys. As of
Tuesday, 333 stocks were yielding more than the 5-year at 1.38%; 313 more than
the 10-year at 1.48%; and 256 more than the 30-year at 1.97%.
But for now, falling yields for Treasurys seems to be a negative
for stocks as the yield on the 10-year note falls further below the 2-year
yield, after slipping below the yield on the 3-month bill earlier this year.
Investors appear to be piling into government bonds, pushing
yields down, in part out of fears of a global economic slowdown and the
potential for recession as worries over an intensifying U.S.-China trade war
mount. An inverted yield curve in particular is seen as a warning signal for a
potential U.S. recession, albeit with a lag. Meanwhile, the yield on the
30-year bond has fallen to an all-time low below 2%, while the yield on the
10-year note ended Tuesday at its lowest since 2016, and is within hailing
distance of its all-time low below 1.4%.
The
S&P 500 and the Dow Jones Industrial Average DJIA, +0.83% have
both pulled back more than 3% in August.
1.NFL Games Make Up 60% of the Top 100 Most Watched Telecasts in
a Typical Year.
In the U.S., the NFL rules sports—and television. Its games make
up 60% of the top 100 most-watched telecasts in a typical year, and over 70% in
years when there are no Olympic Games.
Football Season Is Here and It’s a
Key Moment for the Future of TV
1.LIBOR-The Most Widely Used Global Benchmark for Short-Term Interest Rates….Rolling Over But Above Lows.
1 Year LIBOR Rate – Historical Chart
Interactive chart of
the 12 month LIBOR rate back to 1986. The London Interbank Offered Rate is the
average interest rate at which leading banks borrow funds from other banks in
the London market. LIBOR is the most widely used global “benchmark” or
reference rate for short term interest rates. The current 1 year LIBOR rate as
of August 09, 2019 is 1.99%.
The STOXX Sector indices are available for global markets as
well as for Europe, the Eurozone and Eastern Europe. Using the market
standard ICB Industry Classification Benchmark, companies
are categorised according to their primary source of revenue. This
categorisation guarantees a professional and accurate classification of
companies in their respective business environments. There are four levels of
classification ranging from broad to very detailed: 10 industries are broken
down into 19 supersectors, 41 sectors and 114 subsectors.
1.Bottom-Line
Earnings Beat Rates Down This Season
Mon, Aug 12, 2019
The unofficial Q2 earnings reporting period comes to an end on Thursday when Wal Mart (WMT) releases its numbers. More than 2,000 companies have reported earnings since the season began in early July, and 57.2% of them have beaten consensus analyst EPS estimates. As shown in the chart below, this quarter’s earnings beat rate is down significantly from recent quarters where 60%+ was pretty much a guarantee. If the current reading holds through Thursday, it will be the lowest beat rate since the Q1 2014 reporting period (April and May 2014).
Below is a look at earnings beat rates by sector this season. Technology has the strongest beat rate at 66.1%, followed by Financials at 63.3%. Utilities and Energy have the weakest beat rates at 33.3% and 38.8%, respectively.
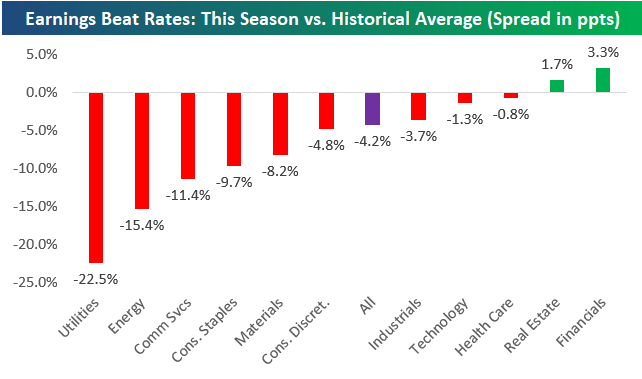
Below we show this season’s earnings beat rates by sector versus the sector’s historical earnings beat rate going back to 2001. All but two sectors have beat rates this season that are below their historical average. The Financial and Real Estate sectors are the only two that have seen stronger-than-normal beat rates. Start a two-week free trial to Bespoke Institutional to access our Trend Analyzer, Chart Scanner, Earnings Explorer and much more.
1. Microsoft, Apple, Amazon, Alphabet, and Facebook Make Up Half of Tech’s Market Cap.
In late 2018, shares of Silicon
Valley’s finest tanked some 16% in three months. Since then, Big Tech has been
busy climbing back near record highs. And, as The Economist points out,
listed tech firms now make up more than 25% of the value of U.S. stock
markets.
The last time tech was this
important was 2000, when the sector briefly made up one-third of the value of
all U.S.-listed equities. Back then, the concern was that tech firms were “too
flimsy” for their valuations. We all know how the dotcom bubble ended, but…
Today’s a different story—tech’s
big five (Microsoft, Apple, Amazon, Alphabet, and Facebook) account for 12% of
pre-tax profits among the U.S.’ non-finance firms, up from 4% in 2010.
Zoom out: Those big
five make up half the tech industry’s market value, meaning new worries
for the new millennium. Today, the concern is less
about financials and more about the idea that Big Tech has accumulated too much
power.
WASHINGTON
— The trade war between the United States and China entered a more dangerous
phase on Monday, as Beijing allowed its currency to weaken, Chinese enterprises
stopped making new purchases of American farm goods and President Trump
indicated he would look for ways to retaliate.
The
escalation shook world markets on Monday, as nervous investors looked for safe
places to park their money. Wall Street suffered its worst day of the year,
with the S&P 500 closing down nearly 3 percent. Selling was especially
heavy in the trade-sensitive technology, consumer discretionary and industrial
sectors. Yields on United States Treasuries, which fall as prices rise, dropped
as investors sought safety in government-backed bonds. Benchmark indexes in
Asia and Europe also fell.
On
Sunday, the People’s Bank of China, the country’s central bank, allowed its
currency to weaken past the psychologically important point of 7 to the
American dollar for the first time in more than a decade. In an unusually blunt
statement, the bank blamed the currency fall on Mr. Trump’s “unilateralism and
trade protectionism measures and the imposition of increased tariffs on China.”
Mr. Trump’s decision to impose additional tariffs
on Chinese goods also prompted Chinese enterprises to halt purchases of
American agricultural goods, according to China’s state-run Xinhua News Agency,
which called the president’s proposed tariffs a “serious violation” of an agreement
reached in June with Chinese President Xi Jinping.
1.Software ETF a Double in 3 Years with Many Names Trading at
20x Sales vs. S&P 2x Sales.
The exchange-traded fund (ticker: IGV) is up 32% this year and
100% over the past three years. Many software companies are now valued at
more than 20 times projected 2019 sales—and without any earnings. No major
industry has a higher valuation. The S&P 500 index is valued at about two
times sales
Sky-High Software Stocks Are
Beginning to Look Like They’re Forming a Bubble–Andrew Bary
And Tech shorts have capitulated. Usually
sign of top, says the always negative Zero Hedge – Growth Tech was shredded yesterday
From Dave Lutz at Jones Trading
3.Rate Cuts
Near Equity Highs…Historically Positive.
While they are not an explicit component of its mandate, changes in the
Fed’s monetary policy often have an observable effect on US securities markets.
Rate decisions are often discussed as they relate to fixed income markets, as
rate movements have a direct and inverse relationship to bond prices. However,
as we saw earlier this year when dovish comments from Chair Powell led to an
equity rally, fed rate policy can have also have important implications for the
US stocks. So, what’s in store for the US equity market should the Fed cut
rates next week as anticipated?
The expected rate reduction from the Fed comes against the backdrop of a
US equity market that has seen each of the major large cap benchmarks hit new
all-time highs within the last week. Based on research by John Lewis, Senior
Portfolio Manager at Nasdaq Dorsey Wright, since 1990, when the Fed has
initiated a rate cut when the S&P 500 SPX was
within 5% of its high, on average, the index has posted positive returns over
the next one-, three-, six-, nine-, and 12-month period; with an average
12-month gain of almost 11%. In fact, the only two occasions when we saw
negative 12-month returns following a rate cut when SPX was within 5% of its
high were the two successive cuts in September and October 2007, which preceded
the global financial crisis. On the other hand, when a rate cut has been initiated
when the S&P 500 is more than 15% below its high, on average, the index has
posted negative returns over the next one-, three-, six-, nine-, and 12-month
period.
4.As Tech
Explodes in U.S. ….China Sets Up New Market to Compete with Nasdaq for
IPOs.
China Star
Market.
What is China’s
STAR Market?BY MARK
KOLAKOWSKIThe Shanghai Stock Exchange has created a hot
new market showcasing some of China’s most promising tech companies, all with
the goal of catching up to America’s Nasdaq, the birthplace of many of the
world’s legendary and pathbreaking tech giants. The Shanghai Stock Exchange
Science and Technology Innovation Board is being called the STAR Market for
short by Chinese authorities, and began trading on Monday with 25 listed
companies. These stocks ended the opening day with sizzling gains ranging from
84% to 400%, The Wall Street Journalreports.
“It’s a
bit crazy, but I think the situation will calm down a bit in the next few
days,” Jack Zhang, an analyst at BOC International, a securities brokerage and investment banking subsidiary of the Bank
of China, told the Journal. He believes that individual investors with an
appetite for risky speculation drove most of the first-day
action.
“Gains
were much stronger than expected, either due to unreasonable IPO pricing or
speculative trading,” Zhu Junchun, a Shanghai-based analyst with Lianxun
Securities Co., told Bloomberg. “It’s going
to be a liquidity game in the first half year or
one year of trading. Judging by the trading activity and gains on the board,
it’s definitely a success,” he added.
KEY
TAKEAWAYS
The STAR Market is China’s latest challenge to Nasdaq.
Its initial listings are IPOs, mainly from tech
startups.
It allows wider price swings than other Chinese
markets.
It is the only market in China where loss-making firms
can go public.
Share buybacks are expected to approach $1 trillion this year, according to Goldman Sachs.
Funding is coming from a record drawdown in cash as well as a rise in gross debt and leverage.
Buybacks have exceeded free cash flow for the first time since the financial crisis.
U.S. companies are on pace to break another record for share repurchases in
2019, using a combination of cash and debt to push the total to close to $1
trillion.
For the first time since the financial crisis, companies have given back
more to shareholders than they are making in cash net of capital expenditures
and interest payments, or free cash flow, according to Goldman Sachs
calculations.
The level of buybacks to free cash flow hit 104% for the 12 months ending
in the first quarter of 2019, the first time that number has topped 100% during
the economic recovery that started in 2009. In 2017, the level was 82%.
The
Baltic Dry Index (BDI) is a shipping and trade index created by the
London-based Baltic Exchange. It measures changes in the
cost of transporting various raw materials, such as coal and steel.
Members
of the exchange directly contact shipping brokers to assess price levelsfor given shipping paths, a
product to transport, and time to delivery or speed. The Baltic Dry Index is a
composite of three sub-indices that measure different sizes of dry bulk
carriers or merchant ships: Capesize, Panamax, and Supramax.
How the Baltic Dry Index – BDI
Works
The
Baltic Exchange calculates the index by assessing multiple shipping rates
across more than 20 routes for each of the BDI component vessels. Analyzing
multiple geographic shipping paths for each index gives depth to the index’s
composite measurement. Members contact dry bulk shippers worldwide to gather
their prices and they then calculate an average. The Baltic Exchange issues the
BDI daily.
KEY
TAKEAWAYS
The Baltic Exchange calculates the index by assessing
multiple shipping rates across more than 20 routes for each of the BDI
component ships.
Members contact dry bulk shippers worldwide to gather
their prices and they then calculate an average.
Many investors consider a rising or
contracting index to be a leading indicator of future economic
growth.
The index can experience high levels of volatility
because the supply of large carriers tends to be small with long lead
times and high production costs.
The Dutch company Port-Liner is building two giant all-electric
barges dubbed the ‘Tesla ships‘. The company announced that the vessels will be
ready by this autumn and will be inaugurated by sailing the Wilhelmina
canal in the Netherlands.
The 100 million-euro project supported by a €7m subsidy from
the European Union is expected to have a significant impact on local
transport between the ports of Amsterdam, Antwerp, and Rotterdam.
Chief executive of Port-Liner Ton van Meegen told The Loadstar:
“There are some 7,300 inland
vessels across Europe and more than 5,000 of those are owned by entrepreneurs
in Belgium and the Netherlands. We can build upwards of 500 a year, but at
that rate it would take some 50 years to get the industry operating on green
energy.”
The battery-powered barges – pictured above – are capable of
carrying 280 containers.
The first 6 barges are expected to remove 23,000 trucks from the
roads annually in the Netherlands and replace them with zero-emission
transport.
Port-Liner is developing its own vessels, but they developed a
battery pack technology that houses the batteries inside a container.
Meegen says that it could allow them to retrofit existing barges:
“This allows us to retrofit barges
already in operation, which is a big boost for the industry’s green energy
credentials.The containers are charged onshore by carbon-free energy provider
Eneco, which sources solar power, windmills and renewables.”
The first vessels will complete their maiden voyage later
this year.
As we have often discussed in the past, all modes of
transportation are gradually being converted to electric propulsion and
that includes maritime transport.
It’s also an important mode of transportation to convert since it
produces a lot of pollution. Some of the world’s largest cargo ships emit
pollution comparable to millions of passenger cars put together.
Debt
is the cumulative effect of running budget deficits
It’s amazing
to me how often I hear folks (including our politicians…on both side of the
aisle) conflate the terms deficit and debt. The latter is the cumulative effect
of running the former. As you can see in the chart below, per Congressional
Budget Office (CBO) projections, the U.S. budget deficit is expected to exceed
$1 trillion each year starting in 2022; with deficits likely to be well above
the 50-year average. Outlays are expected to jump to 23% of GDP by 2029, from
20.8% this year due to demographics and rising health care costs.
Federal
Budget Looking Ahead
Net Interest
Payments to Swamp Everything Else
Source:
Charles Schwab, CBO (Congressional Budget Office) May 2, 2019 Report: Updated
Budget Projections: 2019 to 2029.
There are few things as American as a classic rags to riches story, and Chobani founder Hamdi Ulukaya seems
to fit this classic narrative to a T. Born into a family of nomadic sheep
herders in Turkey, he came to America with
just $3,000 in his pocket and, through hard work, vision, and a
bit of luck, managed to build a billion-dollar yogurt business.
But while Ulukaya might seem like the perfect example of
old-fashioned business success, from the TED stage in April (hat tip to Swiss Miss) he explained that his views on what it means to be
successful are wildly different from the traditional business playbook.
In fact, rather than seeing himself as the usual
pull-yourself-up-by-your-bootstraps capitalist hero, he thinks of himself as an
“anti-CEO” calling the shots at his company from the “anti-CEO
playbook.” The typical rules of business success, he
flatly declares, are stupid. Here’s what he’s replaced them with.
1. Businesses exist to maximize shareholder value? Nope.
“Today’s business books say businesses exist to maximize
profit for the shareholders. I think that’s the dumbest idea I’ve ever heard in
my life,” Ulukaya says. If businesses shouldn’t try first and foremost to
make money for their owners, what should they aim for? “Businesses should
take care of their employees first,” he insists.
In 2016 Ulukaya took the unusual step of giving his 2,000
employees shares in the company. “Some people said it’s PR. Some said it’s
a gift. I said, ‘It’s not a gift’… They earned it with their talent and their
hard work,” he explains.
2. Ask not what your community can do for you; ask what you can
do for your community.
In a veiled swipe at Amazon’s recent HQ2 beauty contest, where cities competed to
show how many tax breaks and incentives they could offer the online behemoth,
Ulukaya believes companies shouldn’t approach communities with their hand out.
Instead, businesses should go to struggling communities and ask, “How can
I help you?”
“Go search for communities that you can be part of. Ask for
permission and succeed together,” Ulukaya advises, citing the resurgence
of the community around his company’s second factory in rural Idaho to show how
this can work out for the benefit of everyone.
3. Your boss isn’t the board. It’s the consumer.
“Today’s playbook says the CEO reports to the board. In my
opinion the CEO reports to the consumer,” says Ulukaya. He takes this
point so seriously that, in the early days of Chobani, the telephone number on
each pot of yogurt was his own personal line. Customers could literally phone
up the CEO to chat.
“The consumer is in power. That’s the reason business
exists,” he reminds leaders.
All of which sounds idealistic. And it is. But Ulukaya insists
it is also a recipe for a deeper, more meaningful (and clearly still very
remunerative) kind of success.
“If you’re right with your people, if you’re right with
your community, if you’re right with your product, you’ll be more profitable,
more innovative, and you will have more passionate people working for you and a
community that supports you,” he concludes.
U.S.
stocks have powered back to record highs, and they could benefit more from a
relatively expensive fixed income market.
As shown in the LPL
Chart of the Day, Stocks Appear
Historically Cheap Relative to Bonds, S&P 500 Index stocks
are at their most attractive valuations relative to Treasuries in nearly three
years. This data is based on a metric we track called the equity risk
premium (ERP), which compares the earnings yield on equities (or company
profitability as a percent of share price) to the 10-year Treasury yield.
There
are several different ways to view stock and bond valuations, so the ERP is
only one piece of the puzzle. However, the ERP’s recent ascent shows how much
global buying pressure has crimped U.S. yields this year.
There are several different ways to view
stock and bond valuations, so the ERP is only one piece of the puzzle. However,
the ERP’s recent ascent shows how much global buying pressure has crimped U.S.
yields this year.
1. Private equity firms
poised to sign record number of deals
The Bain & Company data showed multiples
for companies being bought in the US and Europe are close to 11 times earnings
before interest, tax, depreciation and amortisation.
Among tech companies, SAP, ASML and
Ericsson are scheduled to report this week, which might signal what’s next for
the shares of Europe’s best-performing industry this year – The
region’s technology sector is up 26% in 2019, keeping up with the Nasdaq 100, while the Philadelphia Semiconductor Index SOX
has soared more than 30%
Dave Lutz at Jones Trading.
2.P/B and P/E Spreads Touch 1999 Levels for S&P 500 vs.
Value.
Value stocks are trading at the steepest discount in
history
7.Dividends
and Buybacks Have Exceeded Free Cash Flow Since 2013
The Capital Group
source: Capital Group. Universe is made up of
2,902 non-financial U.S.-based companies that represent more than 98% of the
U.S. public equity market. As of 12/31/18.
While Wall Street is still
drooling over Beyond Meat, researchers are looking one step ahead to the next
generation of meat cultivation: cellular agriculture.
What it is: Cellular
agriculture uses cultures to build cell-based products outside of an organism.
This can include animal-derived products, such as meat, eggs, and dairy, as
well as byproducts like silk, leather, and fur.
The foundations—biotechnology and tissue engineering—have
already been established in clinical settings (think regenerative
medicine). But unlike a “lab-grown” kidney, you don’t have to
worry about putting the lab-grown filet mignon into the cow. Just
don’t overcook it.
The first hamburger grown in a
lab burned the roofs of taste-testers’ mouths in 2013. But it cost $330,000, and that
was before guac. Researchers are betting that in a few years, similar meat
products will 1) be affordable and 2) taste and feel even more like the
“real” thing.
The warm reception of plant-based
meat alternatives (like Beyond Meat) is a good indicator of future demand for
cellular agriculture products. Consumers want clean, ethical, and sustainable
food, and meat farmed in a lab setting could change what it means to be
“vegetarian” or “vegan.”
Prepare to debate what counts as
meat. Plant-based products have already received pushback from the
meat and dairy industries over labeling. Even cauliflower rice has not
emerged unscathed.
Actually, let’s debate it right
now. Should cell-based, lab-developed meat count as real meat? Vote here.
Boil it down
The promise: Clean,
sustainable, safe meat products, without any of the ethical or environmental
problems that plague today’s livestock and aquaculture industries.
The roadblocks: Cellular
agriculture has never been conducted on a commercial scale or with price
constraints. Customers also have to get on board.
The projected timeline:
Researchers are betting that in a few years, cellular agriculture-derived meat
products will be affordable and taste and feel even more like the
“real” thing.
The major players: Meat
(Aleph Farms, Mosa Meat, Memphis Meats), seafood (Finless Foods, BlueNalu), and
animal-derived products (Clara Foods, Perfect Day Foods, Modern Meadow).
Workplace
stress, while commonplace, is incredibly damaging — which means we shouldn’t
just accept it.
Addressing
stress will make both your quality of life and your workplace better.
Ironically,
things like too much free time can add to your stress. Dealing with stress is
often about focusing on results and planning well.
Last year, my
company, Skylum, experienced some tough times. We grew
sizably, but we were also navigating new markets and facing unexpected
challenges. Ultimately, we had to ask — and answer — some hard questions of
ourselves. Today, the company is more successful than it’s ever been. But our
year of growth and adjustment also had another side effect: Everyone in the
company — myself very much included — struggled with new and
difficult levels of stress.
This doesn’t make us
unique. According to The American Institute of Stress,
80 percent of employees today experience stress at their job. CEOs and company
leaders suffer the most, with a majority reporting feeling regularly overworked, exhausted,
and anxious. The problem is so pervasive that it now feels
commonplace and almostrequired of working and keeping a good job.
The truth, however, is
that workplace stress is remarkably damaging — both to our health and to our general
effectiveness in the office.
It’s the ultimate
distraction. It tires your brain and prevents you from applying 100 percent of
your mental energy to whatever task is at hand.
So if you’re attempting to
achieve any kind of goal, stress is something you need to combat
rather than accept. Here are the four primary types of stress — and how to manage them.
Stressor 1: Having too much work
Focus on results, and prioritize from there. Nattakorn_Maneerat/Shutterstock
Problem: Company
leaders and managers constantly have things to
do, along with people who rightfully need our attention and time. Trying to
complete all these tasks runs us down and drains our focus and happiness.
Solution: Focus on
results, not the workload itself. Many of us — CEOs included — tend to focus on the amount of work we have, as if
the number of nights we spend at the office is indicative of our success. Guess
what? It’s not. So instead, prioritize your individual responsibilities in
accordance with your short-term and long-term goals. This will help you
determine what you actually need to do today in order to achieve your
most pressing goals. If you have a new product you’re launching in two months,
for example, ensuring that launch is successful is likely your most important
goal. You should make sure that everything you do furthers your progress in
achieving that end. To help you make such determinations, use metrics and data.
Then eliminate, delegate, or ignore processes and tasks which won’t contribute
to your growth.
Stressor 2: Having too little work
It may seem paradoxical, but more free time can add to
stress.funkyfrogstock/Shutterstock
Problem: One of the
ways CEOs manage major influxes of work is by delegating tasks. But with
delegation comes more free time. I experienced this first hand. As Skylum grew,
suddenly I had roughly 70% more free time, and I had to figure out how to best
spend it. As I discovered, this can be even more stressful than having too much
work; I felt like I wasn’t adding as much value as before, and I feared
employees might get frustrated.
Solution: Focus your
energy on new and specific goals. One of those goals in my case was building
and managing highly effective teams. Sure, I wasn’t running PR and marketing by
myself anymore, but I could help ensure those who were now in charge had
everything they needed to be successful. Once you’ve identified your new areas
of focus, apply yourself to add as much value in those verticals as you can. As
you grow, this is what your role as a CEO or manager will always look like:
identifying areas of weakness at your company, and then applying yourself to
address those as best you can.
Problem: You always
want to stay connected with your team, but as a company leader, this isn’t
always possible. I’m reminded of this whenever I’m on the road for long
periods. You worry about whether your team will suffer without direct access to
their leader. You also worry that without you managing or directing things,
productivity, engagement, or happiness might dip.
Solution: It’s
threefold:
Utilize a variety of
channels to maintain communication — Slack, email, Skype.
Identify “opinion
leaders” and “influencers” within the company you can partner
with to relay your messages and help you manage morale from afar.
Get feedback from outside
sources, such as your family or other founders. Your situation is not unique,
so solve it by talking with folks who’ve gone through it before.
Stressor 4: Things not happening as fast as you’d like
It can take time to see progress on big projects. Shutterstock
Problem: This one,
again, is especially hard for company leaders; you want things to grow and move
along quickly, but often, they don’t. And you won’t always have control over
that.
Solution: Take time
to reflect and evaluate the effectiveness of each individual component of your
company. Determine whether disparate teams are putting in maximum effort toward
delivering the result you want. If they’re not, weigh potential solutions, and
decide whether those folks may need a bit of a nudge. If folks areworking
hard, recognize that sometimes, progress simply can’t be rushed. I find that
with big projects, you often don’t see results for more than six months or a
year after you start working. So in those moments, turn your attention to
something else — something
that is in your control and that you can have a tangible
impact on.
At the end of the day,
stress management is necessary. And the best way to go about doing it is
to look at your sources of stress objectively, and work smart to identify
solutions. Your solutions may look different than those which I ultimately
employed, but I’m confident the methodology will be the same.
Central
banks are back in easing mode, to the dismay of coupon-clipping fixed income
investors.
As shown in the LPL
Chart of the Day, Global Central Banks Back in Easing
Mode, central banks around the world are embarking
on a marked policy shift as trade tensions pressure the global economy and
government becomes more intertwined with policy decisions.
Two of the world’s most influential central
banks, the Federal Reserve (Fed) and the European Central Bank (ECB), are
eyeing looser policy in the months ahead. We expect the Fed to implement a 25
basis point (0.25%) “insurance” rate cut at its July meeting, and policymakers
have already announced plans to end balance sheet runoff in September. The ECB
has all but promised a new wave of accommodation, likely through asset
purchases.
Most S&P 500 sectors are expected to
show earnings declines; health care is an exception
Cigna’s quarterly sales per share are expected
nearly to double, even with significant dilution from issuing shares to help
pay for its acquisition of Express Scripts.
Despite all the good
economic news, earnings growth is expected to slow to a crawl this year for
large U.S. companies. It may also surprise you that the health-care sector is
seen as one of the exceptions.
During the first quarter of 2019, earnings per
share declined from a year earlier for six of the S&P 500’s SPX, +0.45% 11
sectors. These are the five that countered the trend, according to S&P
Global Market Intelligence:
S&P 500 sector
Increase in Q1 EPS
Health
Care
9.8%
Real
Estate
7.4%
Financials
6.2%
Industrials
5.9%
Information
Technology
4.0%
Source: S&P
Global Market Intelligence
For the second quarter,
consensus estimates among analysts polled by S&P Global Market Intelligence
are for the S&P 500’s weighted aggregate EPS to increase 2.2% from a year
earlier. Even so, all but these three sectors are expected to show declines:
S&P 500 sector
Expected increase in Q2 EPS
Financials
4.3%
Health
Care
2.0%
Industrials
0.2%
Source: S&P
Global Market Intelligence
Health
care is one of the stock market’s healthiest sectors right now
(Bloomberg) — Wall
Street hasn’t been this down on Apple Inc. in a long time.
Rosenblatt
Securities downgraded the company to sell on Monday, bringing the total number
of bearish analysts up to five, among the 57 ratings tracked by Bloomberg. Five
is the highest number of sell ratings the iPhone maker has had since at least
1997, according to historical data compiled by Bloomberg. To put that into
context, Apple wouldn’t release its iMac computer until August 1998, and the
iconic iPod wouldn’t debut until October 2001.
In another sign of
the growing caution around the company, Apple’s consensus rating — a proxy for
the company’s ratio of buy, hold, and sell ratings — is currently 3.76,
according to Bloomberg data. That’s the lowest since 2004.
Skepticism
surrounding the company has accelerated in 2019, with all five of the sell
ratings coming in this year. Both New Street Research and HSBC lowered their
ratings on the stock to sell in April, and in January, the number of firms with
buy ratings dropped below 50% for the first time since 2004.
The caution has
been largely driven by uncertainty surrounding demand for the company’s
critical iPhone line, with the U.S.-China trade war seen as a particular
headwind. In January, Apple cut its revenue outlook for the first time in
almost two decades, in large part because of iPhone weakness. Apple’s
third-quarter results are currently expected to come out on July 30.
According to data
compiled by Bloomberg, more than 60% of Apple’s 2018 revenue was related to the
iPhone, while roughly 20% came from China, which is also a critical part of its
supply chain. Last week, Citi wrote that Apple’s China sales “could be cut in
half” due to “a less favorable brand image desire.”
Rosenblatt’s
downgrade came as analyst Jun Zhang expects the company “will face fundamental
deterioration over the next 6-12 months,” based on disappointing sales trends.
The downgrade pushed Apple stock lower by as much as 2.9% in Monday trading.
Still, the
sell-equivalent ratings hardly represent a consensus view. A plurality of 23
firms recommend buying the stock, while another 21 have hold ratings, according
to data compiled by Bloomberg.
The 2019 caution
hasn’t really been reflected in Apple’s stock performance. Shares are up more
than 40% from its January low, though they remain about 14% below record
levels.
The news was not
entirely negative for Apple on Monday, however, as Wedbush wrote it was
“incrementally more positive on global iPhone demand” following checks in Asia.
“We saw a ‘slight uptick’ out of Apple suppliers during our checks although
overall handset demand remains challenging,” analyst Daniel Ives wrote. He
affirmed his outperform rating and $235 price target.
(Adds context in second
paragraph, consensus rating in third, and stock performance in ninth.)
4.What
Factors are Cheap and Expensive Versus 10 Year and 35 Year History
Value and Small Cap Cheap?
5.The Median
Age of Tech Companies Going Public in 1999 was 4; Last Year it was 12
Barrons
Initial offerings could raise a record level of capital in
2019, potentially breaking the nearly $97 billion record set in 2000. But
Wainwright, and IPO investors, have returned wiser and more disciplined.
In a sense, the IPO market has simply grown up. For one thing,
the median age of tech companies going public in 1999 was four; last year, it
was 12. And having been burned in the bubble years by IPOs for wildly
speculative and ultimately failed businesses, such as theGlobe.com and eToys,
investors have tightened their standards. They now want established businesses
with substantial revenue and high growth.
The RealReal Is No Pets.com and
Today’s IPO Market Is Not the Next Dot-Com BubbleBy Eric J. Savitz
Passive investments control about 60% of the equity assets,
while quantitative funds — those relying on trend-following models instead of
fundamental research — now account for 20% of the market share, according to
estimates from J.P. Morgan.
Passive funds have attracted $39 billion of inflows so far this
year, whereas active funds lost a whopping $90 billion in 2019, the bank said.
It’s no secret that
machines are taking up a bigger and bigger share of investing, but the extent
of their influence is approaching shocking proportions. It is as high as 80%,
according to one major investing firm.
Passive investments such
as index funds and exchange-traded funds control about 60% of the equity
assets, while quantitative funds, those which rely on trend-following models
instead of fundamental research from humans, now account for 20% of the market share,
according to estimates from J.P. Morgan.
This means so much of
stock trading is now in the hands of automated buyers and sellers that the
market is increasingly sensitive to headlines and more prone to sharp price
swings, many notable investors believe.
Omega Advisors founder
Leon Cooperman previously said computer trading is creating a “Wild West” with the
markets, calling for an investigation by the Securities and Exchange
Commission.
DoubleLine Capital CEO
Jeffrey Gundlach has taken a shot at passive investing, saying it is causing
widespread problems in global stock markets. He called it a “herding behavior.”
“I’m not at all a fan of
passive investing. In fact, I think passive investing … has reached mania
status as we went into the peak of the global stock market,” Gundlach said in December.
While algorithmic models
have gained popularity on Wall Street, low-cost passive vehicles keep raking in
assets from Main Street. Passive funds have attracted $39 billion of inflows so
far this year, whereas active funds lost a whopping $90 billion in 2019,
according to J.P. Morgan.
“The pace of outflows
from Active is at a cycle high while the pace of passive equity inflows has
bottomed and [is] beginning to reaccelerate,” Dubravko Lakos-Bujas, J.P.
Morgan’s chief U.S. equity strategist, said in a note on Friday.
The
Federal Reserve (Fed) will likely cut rates at its next meeting in late July.
This begs the question: Will the Fed really cut rates with stocks up so much
year to date and near all-time highs? “It might sound strange for the Fed to
cut rates with stocks up a lot for the year,” explained LPL Senior Market
Strategist Ryan Detrick. “But since 1975, the Fed has cut rates 26 times with
the S&P 500 Index up at least 15% for the year, most recently in 1995 and
1998.”
Here’s the catch: A
year after those cuts, the S&P 500 was higher 23 out of 26 times—with a
very solid average gain of 13.4%. So it would appear monetary policy could be a
continued tailwind.
SALEM,
Ore. — Oregon is awash in pot, glutted with so much legal weed that if growing
were to stop today, it could take more than six years by one estimate to smoke
or eat it all.
Now,
the state is looking to curb production.
Five
years after voters legalized recreational marijuana, lawmakers are moving to
give the Oregon Liquor Control Commission more leeway to deny new pot-growing
licenses based on supply and demand.
The
bill, which passed the Senate and is now before the House, is aimed not just at
reducing the huge surplus but at preventing diversion of unsold legal marijuana
into the black market and forestalling a crackdown by federal prosecutors.
“The
harsh reality is we have too much product on the market,” said Democratic Gov.
Kate Brown, who intends to sign the bill if it wins final passage as expected.
Supply
is running twice as high as demand, meaning that the surplus from last year’s
harvest alone could amount to roughly 2.3 million pounds of marijuana, by the
liquor commission’s figures. That’s the equivalent of over 1 billion joints.
One
massive plot of land out in the frigid wasteland of the northern Yukon and
build a vast complex of unnecessarily poorly-designed buildings. There will be
no roads that lead there. No utilities. No central heating. And insufficient
staff to maintain the structure. I’ll then call it, “The Hall of Fame of Bad
Decisions.”
It will be perfect. Because not only will
the hall itself be a bad decision, but anyone who ever attempts to visit it
will clearly be making a bad decision as well.
Inside the hall, we will have exhibits for
all of the worst decisions ever made. There’d be one for that time when Kodak,
despite owning 90% of the market share of the camera industry and inventing the
digital camera, decided not to sell them and went bankrupt as a result.
There will be another for the time when Decca Records passed on signing The Beatles because
they thought “guitar bands are on the way out.” There will be a whole wing for
stupid military leaders who tried to invade Russia. And we’ll have a special
“Tiger Woods” wing where we rotate in/out celebrities who wreck their own careers
by doing something exceedingly dumb.
It’ll be great.
And I guess, while people are there, we’ll
trot out a speaker or two and give seminars on how to not make such
awful choices. They’ll offer some principles on how to make better life
decisions.
Maybe that seminar would go something like
this:
1. UNDERSTAND
VALUE AND BIASES
All tough decisions are essentially
about weighing values. There’s financial value, emotional value, social value, intellectual value, and
so on. You have to consider all of them, weighing them appropriately. And not
just in the short-term, but in the long-term as well.
As a general rule, we are all heavily biased
towards the short-term rewards and towards emotional value. We are biased towards our
pre-existing beliefs and protecting our reputation. And we’re also bad at
seeing long-term rewards clearly because it’s difficult to look past our
immediate fears and anxieties. Our emotions color everything we see.
Our “default” decision-making also makes it
incredibly painful emotionally to give up on something we’ve worked a long time
on, or to consider that we may have been wrong for years.
The fact is, we’ve all been wrong for years. We’re all wrong about
our value estimates. And until we can be honest about how wrong we were in the
past, we won’t learn to make better value judgments moving into the future.
Our “default” decision-making also
encourages us to avoid short-term failures, even if that means missing out on
long-term successes.
No, the sweet spot in decision-making is to
find the short-term failures that enable the huge
long-term successes to happen in the first place. Because this is what most
people are bad at. And because people are bad at it, this is where most of the
opportunity lies…
2. LOSE ON
PURPOSE (SOMETIMES)
Ever hear those stories of wildly successful entrepreneurs and
how they had, like, 23 failed businesses before they made it big?
The lesson we’re all supposed to take from
this is that persistence and hard work is the key to extraordinary success.
And sure, whatever…
Usually, we can’t help but look at them and
think about how “lucky” they got.
I mean, Amazon! Who knew?!
What we don’t consider is that out of those
dozens of failed, half-baked business ideas were all wagers with limited
downside and extremely high upside. That is, if they lose, they lose a little.
But if they win, they win a lot.
Let’s say I gave you a pair of dice and I
told you that if you roll double ones, I’ll give you $10,000. But each roll costs
$100. How many times would you roll?
If you’re not bad at math, you would know
that you should spend all the money you have rolling those damn dice.
Most people look at each decision as a
single roll of the dice. They don’t think about the fact that life is a never-ending sequence of dice rolls. And a strategy
that loses a lot per roll can actually make you a big winner in the long run.
Yes, you will lose the dice game way more
than you win. But when you win, your winnings will far outstrip your losses,
making it a worthwhile wager.
You can apply the same “risky” behavior in
your life to achieve more optimal long-term results:
Propose “moonshot” ideas at work knowing that 90% of
them will get shot down, but also that if one of them gets accepted it
will be a huge boost to your career.
Expose your kids to difficult subjects at an early age,
knowing that most likely they won’t take to it. But if they do, it will
give them a huge advantage throughout their life.
Be
excessively bold in your dating life,
stating exactly who and what you want, knowing that the vast majority of
people will not be compatible.
Buy
a bunch of difficult books expecting
that most of them won’t be useful or comprehensible to you, but also that,
occasionally, one will completely change your life.
Say yes to every invitation knowing that most of the
events/people will be kind of dull and you’ll just go home early, but that
occasionally you’ll meet someone really important or interesting.
When you think purely in terms of the
immediate result, you cut yourself off from the biggest potential gains in
life. And the reason most of us do this is because of our pesky emotions. Our emotions are short-term biased.
They are obsessed with the present moment. And this prevents good
decision-making.
3. TREAT YOUR
EMOTIONS LIKE YOU’D TREAT A DOG
Here’s one thing I’ve noticed over the
years: shitty dogs almost always have shitty owners. The dog’s level of
discipline is reflected in the owner’s emotional maturity and self-discipline.
It’s very rare to see a dog that’s wrecking the house, eating all the toilet
paper and pooping all over the couch and the owner has
their own shit together.
This is because our connections with dogs
are purely emotional. And if we suck at dealing with our own emotions, then
we’ll suck at dealing with our dogs. It’s that simple. If you don’t know how to
limit yourself and tell yourself “no” when necessary, then, well, don’t get a
dog. And if you do, don’t fucking move into my building.
Our emotions are kind of like our dog that’s
living inside our head. We have this part of ourselves that just wants to eat,
sleep, fuck and play, but has no conception of future consequences or risks.
That’s the part of ourselves we need to
train.
Our emotions are important. But they’re also
kind of dumb. They’re not able to think through consequences or consider
multiple factors when acting.
Our emotions overreact to things by design.
They evolved to keep us alive when we were hunting water buffalo on the
savannah and shit like that. When we’re scared we want to run away or hide.
When we’re angry we want to break stuff.
Thankfully, our brains evolved logic and the
ability to consider the past and the future and all that great stuff. That’s
what makes us humans. And not dogs.
The problem is, our “dog brain” is actually
what controls our behavior. You can intellectually know that eating ice cream
for breakfast is a bad idea, but if your dog brain wants fucking ice cream for
breakfast, then that’s ultimately where your body is going to go.
It’s only by training your dog brain with
your people brain, “No, bad Mark, ice cream for breakfast is bad, go do
something else that feels good and is healthy,” that your dog brain
gradually learns.
Do that enough and you have a well-behaved
dog brain.
Emotions are great for giving you that umph
of passion and spirit, the same way a dog is great
for running and fetching stuff and being a great friend and barking when
someone weird is hanging out by your bedroom window.
But the dog is limited. It needs context and
direction to behave well and function. And that’s your job as the dog owner.
Similarly, your dog owner brain must train the dog brain to sit down and shut
up when necessary. You must give yourself context and direction. Train yourself
to adopt the correct habits and make better
decisions. Reward and punish yourself.
Love your dog brain (i.e., love yourself),
accept your dog brain (i.e., accept your emotions), but also discipline them.
And every once in a while, indulge yourself…
that’s a good boy. Yeah, who’s a good boy? Who’s a good boy? Yes, you’re a good boy.
4. OPTIMIZE YOUR
LIFE FOR FEWEST REGRETS
Regret is sometimes called a “rational
emotion” by psychologists. And not really because regret itself makes us more
rational—at least not directly—but rather the way we predictregret is often done
in a rational-looking way.1
In making decisions, we’ll often consider
the options available to us, imagine our future selves after choosing one of
these options, and then try to feel how much regret we experience in this
simulated future state. We then run this simulation again, choosing a different
option, and compare that simulated state of regret/non-regret to the others.
This ability is both a) fucking amazing when
you think about it and b) incredibly useful as long as we use the most accurate
and complete information available to us (by using all the ideas we’re covering
here, of course).
Most of us are afraid of failing or screwing something up. But we
rarely ask, “Would I regret that failure?” If the answer is “no,” then that is
absolutely a risk you should pursue.
Similarly, a lot of us love
envisioning massive success. But
if we ask, “Would I regret never having that success?” usually we find that the
answer is “no.” Only when it’s “yes” should we probably make the sacrifices to
achieve it.
Sometimes, the right decision becomes
crystal clear when put into these terms. Legend has it that Jeff Bezos left his
cushy, high-paying job to start Amazon because it was so obvious to him that
he’d regret it if he got old and didn’t at least try this whole
“internet thing.” Staying at his job, on the other hand, carried a lot of
future regret that was apparently quite palpable for Bezos.
I personally know a lot of people—myself
included—who ultimately made big life decisions largely based on the path of
least regret. These decisions are almost always described as the best decisions
they’ve ever made. Go figure.
Instead of basing your decisions around
success/failure, or happiness/pain, base them around regret avoidance. Our
regrets are usually the best measurement of what is actually valuable to us in
the long-run.
5. WRITE SHIT
DOWN
The best way to help you sort out all of
your emotional drivel from actual decision-making is to write things down.
Writing things down is a simple but powerful
way to clarify everything that’s swirling around in your head. I get emails
from readers all the time with long screeds about the issues in their lives
only to have them say at the end that they don’t need a reply because writing
it all out was so cathartic and revealing for them.
The act of writing forces you to organize
and make concrete all the emotional turbulence swirling around in your brain.
Vague feelings become structured and measured. Your self-contradictions
are laid bare. Rereading what you write reveals your own logic (or lack
thereof). And it often reveals new perspectives you hadn’t considered.
And when it comes to mulling over a
decision, there are a few specific things you can write about to help you if
you’re having difficulties:
What are the costs and benefits? First,
take some time and do a good old-fashioned cost-benefit analysis of your
decision. But don’t just do the old-fashioned “pros” and “cons” list. Add
a couple more columns. Separate your “pros” into both long-term and
short-term. Add a column for regrets associated with each decision. And
note if there is any long-shot potential for success (see Principle #2).
What is your motivation behind the decision and is that a
value you want to cultivate in yourself? All
the decisions we make, big or small, are motivated in some way or another
by our intentions. Sometimes this is very straightforward.
Last night, I was
motivated by hunger to eat something and there was a burrito in front of me, so
I shoveled it into my face hole.
Sometimes it’s not
so straightforward though. Problems arise when our intentions a) aren’t very
clear to us and/or b) conflict with our core values.
For example, are you
buying that car because you would genuinely benefit from owning it, or because
you’re trying to impress the people around you?
Or are you filing
for full custody of your kids because you think it’s truly in their best
interest, or are you trying to get revenge on your ex after finding out they
are dating someone new?
Are you trying
to start a business because
you enjoy the challenges and ups and downs of making your own way, or are you
jealous of your friends that have successful businesses and feel like you don’t quite measure up to them?
If you identify some
ulterior motives when weighing a decision, stop and ask yourself if your
intentions align with who you want to be.
And if you’re asking
yourself, “Well shit, I’ve never thought about who I want to be. What
should I do?” Then I think you should take out a fresh piece of paper and start
writing that down.
For instance, here’s my Horrible Decisions
Hall of Fame Table:
Pros
* It’s funny
* Oh, Canada!
* Get to research celebrities with hookers
Cons
* Expensive
* Lot of work
* Really, really far away
* Joke is only funny for so long
Long-Term
* Illiquid asset
* Seriously, when am I ever going to
travel to this thing?
* For the rest of my life, I’ll be the
“Dumb Hall of Fame” guy.
Potential Regrets
* DOING: Tons, lost time, money, etc.
* NOT DOING: Uhh… none, really.
Rep. Value
* Do I really want to dedicate a huge
portion of my life and legacy to being a clever smart ass? Probably not.
So there you have it. No “Horrible Decision
Hall of Fame.” Why? Because it’s a horrible decision.
HOW TO KNOW WHO YOU REALLY ARE
We all think we know ourselves well, but psychological studies
show otherwise. In fact, most of us are somewhat deluded about ourselves. I put
together a 22-page ebook explaining how we can come to know ourselves better,
just fill out your email in the form.
You’ll also receive updates on new articles, books and other
things I’m working on. You can opt out at any time. See my privacy
policy.
1.Inflation Rolls Back Over….$11 Trillion Globally in Negative Yielding Bonds and Still No Inflation.
The risk of too little inflation
Written by Russ Koesterich, CFA Low inflation may sound appealing, but as Russ explains, it has drawbacks for investors.
By any account the U.S. equity market is having a stellar year. Stocks have benefited from easier financial conditions, which have in turn pushed up market multiples. By a happy coincidence, gains in market multiples have exactly matched the 15% gain in the S&P 500 Index.
But while stocks have benefited from cheap money and higher multiples, they have more recently been constrained by concerns over growth. The challenge is that the same slowdown that led the Federal Reserve to pivot and stop raising rates also puts earnings at risk. Recent developments in the inflation-linked bond market (i.e., Treasury Inflation Protected Securities, or TIPS) suggest that investors are right to be a bit more cautious.
Inflation expectations embedded in the TIPS market are signaling that already low inflation will fall even lower. In late April, the 10-year TIPS breakeven (BE), i.e. the amount of inflation TIPS investors expect during the next decade, was about 1.95%. Today, the 10-year BE is below 1.70%. The outlook for the next five years is even softer, roughly 1.50%. And while inflation expectations are higher using different market measures, such as inflation swaps, the direction is still down (see Chart 1).
AAII Surveys show Investors still quite cautious on the market (WSJ), which is clearly bullish
Overwhelming Belief that Rates Will Be Lower.
The percentage of investors expecting lower long-term bond yields is the highest since late 2008, according to
the latest BofAML fund managers’ survey.
6.Percentage of Web Traffic Encrypted Jumps from 53% 2016 to 87% 2019
That messaging apps have increasingly become our go-to mode of communicating isn’t a revelation, but the idea that encryption is becoming the norm is striking.
Meeker’s numbers show that in the first quarter of this year, 87% of global web traffic was encrypted, up from 53% just three years ago.
7.Americans Now Spend More at Internet Stores Than Restaurants
BC-Americans-Now-Spend-More-at-Internet-Stores-Than-Restaurants , Alex Tanzi
(Bloomberg) — U.S. stores reported broad-based gains in activity last month as 10 of 13 major sectors increased sales from a year earlier.
But, just how concentrated are the gains? The dominance of online merchants is becoming increasingly clear. In the past year, Americans’ boosted spending to “nonstore retailers” while clothing, food & beverage and building-material stores felt the brunt of consumers’ changing habits.
Spending at nonstore retailers, mostly Internet merchants, increased by $6.4 billion from a year earlier to $62.04 billion on an annualized basis. The nonstore retailer category is now a larger spending category than restaurant and bars.
Given the pace of growth, nonstore spending will likely pass food and beverage — mainly grocery stores — spending soon and move to the second largest retail category behind vehicles and parts.
To contact the reporter on this story: Alex Tanzi in Washington at atanzi@bloomberg.net
To contact the editors responsible for this story: Alex Tanzi at atanzi@bloomberg.net, Wei Lu
In theory, an increased supply of government bonds—sold to raise funds when spending exceeds revenues—should increase government borrowing costs. Theory also says big deficits crowd out business borrowing and increase private borrowing costs, too.
The opposite has happened. While government debt soared after the 2007-09 financial crisis, 10-year Treasury yields have fallen to near 2% from more than 5% in 2006, holding down government interest payments. U.S. business debt rose to $15 trillion in 2018 from $9 trillion in 2006.
How Washington Learned to Love Debt and Deficits
Political support for taming federal debt has melted away, and the U.S. is testing just how much it can borrow
9.9 mind-blowing facts about the millennial housing market
For millennials, the housing market looks a lot different than it did for their parents and grandparents.
Rising housing costs and mounting student debt have ledmillennialsto buy different types of homes in different types of locations than their parents did.
Millennials are buying under different circumstances, too, often waiting longer, buying before marriage, or living with their parents to save cash so they don’t have to wait years for homeownership.
Below are nine surprising facts about the millennialhousing marketthat put it in perspective.
The housing market looks a lot different today than it did a couple generations ago.
That’s something that more and more millennials, the group between the ages of 23 and 38, are discovering firsthand every day, whether they’re renting their first apartment or already on to their second purchase of a house.
Why is the housing market so different for millennials compared to the one their parents and grandparents faced?
In large part it’s because of how much housing costs have risen, but it’s also because of the student debt with which many members of the generation are saddled. Some 70% of recent college graduates finish school with an average of $29,800 in debt to repay, plus the inevitable interest.
Faced with these financial challenges, it’s little wonder that millennials are buying different types of homes and in different types of locations than their parents did. And they are buying under different circumstances, too, often waiting longer, buying before marriage, or living with their parents to save cash so they don’t have to wait years for homeownership.
Here are nine surprising facts about the millennial housing market that put it in perspective.
Millennials face house prices 39% higher than their parents did in the 1980s
Housing prices have soared by nearly 40% in the past three-plus decades, far outpacing wage increases and making homeownership much more of a challenge for today’s buyers. The increase is even more dramatic the further back you look: Today’s average home price is more than 70% higher than what a buyer faced in the 1960s.
Rent prices are up nearly 50% over the last half century
While traditionally renting an apartment or house while saving up to buy your own residence was once a logical approach, since the 1960s, average rent rates have increased by 46%, meaning just affording a rental is harder than ever, let alone saving up to buy.
Many millennials turn to ‘super commuting’ to find homes they can afford
Super commuters are those who travel more than an hour in each direction to and from home and work. In order to find homes they can afford while sticking with a job, many millennials are buying residences in the exurbs and accepting a daily commute of two or more hours.
Birmingham, Alabama, has seen the biggest growth of millennial home ownership increases in recent years
In 2017, millennial homeowners accounted for an impressive 18% of total homeownership in Birmingham, Alabama. That was a dramatic increase over the 11.9% of the homes owned by millennials just one year before in 2016.
33 of the nation’s top 50 housing markets saw increases in millennial home buying
Contrary to the misconception that fewer and fewer millennials are buying homes in major metro areas, themajority of the nation’s top 50 housing markets have actually seen increases in millennial homeownership in recent years.
In some markets, homes built before 2012 are selling at close to 50% discounts because they’re too big and spacious for millennials
Most millennial homebuyers are looking for smaller, more manageable properties than the mini mansions so popular a generation before. And they like sleek, simple interiors. The result is a steep drop in the value of many of the homes baby boomers are now hoping to sell as they downsize after emptying the nest or retiring.
According to the Wall Street Journal, homes around Scottsdale, Arizona, that are worth millions of dollars are selling at discounts of close to 50% because younger buyers aren’t interested in all that space.
A quarter of home-buying millennials are buying homes before getting married
The traditional approach to life put marriage ahead of buying a home with a partner, but millennials aren’t overly concerned with tradition. As many as a quarter of all millennials who buy a house with a partner do so before marriage.
One in three millennial homebuyers tapped into a retirement account to get cash for the purchase
“How can I get my team to engage? I’m doing everything right, but they’re still just sitting there.”
I was talking with a frustrated leader at a healthcare facility. Her team meetings had always been lackluster, so she’d decided to fix them. She’d scoured the internet for best practices, then worked hard to get organized.
For the past month, she’d sent an agenda in advance of every meeting. She started precisely on time. She’d taken notes and ended on time too. And yet, after she talked through the agenda and they’d heard their first report, her requests for comments were met with crickets. No one had much to add. Many didn’t seem to be paying attention at all.
Unfortunately, while she’d diligently followed all those “best practices,” she’d missed the most important step.
If you want people to engage during a meeting, you have to make that clear up front. Great meetings get everyone engaged within the first five minutes.
Here are four ways to successfully open your meeting, and why it matters.
Bring everyone into the room
You can’t have a meeting of the minds if the minds aren’t in the meeting. Remember: Every person invited to your meeting was in the middle of doing something else right before it started. People arrive with minds full of tasks left undone and needs unfulfilled.
A successful opening should capture everyone’s attention. The phones will go dark, the typing stops, and eyes connect.
For example, some leaders welcome everyone at the door. A personal greeting and welcome works just as well in meetings as it does when hosting at home. Teams at Starbucks often pour each other coffee for a short tasting before the meeting begins. Even starting by clearly stating the meeting’s purpose, rather than the logistics, creates more energy.
Set expectations
There are many ways to command the attention of a room, but reading the agenda is not one of them. We do not meet in order to get through an agenda; we meet for a purpose. We meet to create shared understanding, to make decisions, and to set plans in motion.
We meet to make these decisions because we want everyone there to weigh in, to help find the best option, and then to commit to it. If we didn’t need that input or that commitment, we wouldn’t meet.
A successful opening makes the purpose of the meeting — why the meeting matters and why it’s relevant to everyone there — clear. The agenda is the how. Never start with how; start with why.
Then, to cement that purpose for each person, ask for their participation. If your team hasn’t engaged much in the past, don’t assume they know you care about that. After all, they didn’t have to engage before. I’m always surprised when a leader seeking more engagement admits that they’ve never asked for it.
Give everyone practice engaging
So you’ve captured their attention and worked to make your aspirations for the meeting clear. Now, should you go over the agenda?
No. Not yet. First, you have to prove that you welcome engagement by getting everyone engaged right then and there: Everyone in the meeting should directly engage within the first five minutes.
This is why many meetings begin by going around the room to answer a simple question; it’s neither feasible nor polite to continue texting when a room full of people turns to you for an answer.
Other teams might choose to begin with a few minutes of meditation. This helps clear the mind of lingering distractions, while making it impossible to continue fiddling about with a laptop.
Make it safe to engage
Fighting off distraction makes productivity possible, and that’s a worthy goal.
Take a look again at those first three steps, and consider the message you can send in these first five minutes of your meeting.
Attention: We want you here and care about having your focus.
Purpose: This meeting matters to us all and we need your contribution to get the best possible result.
Engagement: All voices matter here. We’re all in this together. We’re all stepping up to answer this call, and we want you with us.
There’s one more big one: A successful meeting opener should also tell people that it’s safe to speak up in this group. It tells each person that they matter, that they belong, and that the other people there care about what they have to bring to the table. Doing this sets the frame for everything that follows, and the right frame makes meetings more productive and more meaningful.
Knowing you’ll meet with your team once a week, consider the impact that investing in these first five minutes might have on your team’s culture. Then, start experimenting. Don’t worry about getting it perfect on your first try. If you’re clear about your purpose and ask your team to engage with you, you won’t have to get it right on your own. You’re meeting so that you can get it right together.
While we’ve seen the 5th best start to June on record, this is also the best start to any month through seven trading days since October 2011 when the S&P rallied 5.67%. Below we show all 4%+ starts to a month through seven trading days since 1980. The most notable takeaway from this data in our view is that the last nine times we’ve seen the S&P gain 4%+ in a month’s first seven trading days, the index has been up over the next week 8 out of 9 times, and it has been up 9 out of 9 times for the remainder of the month. To access our most actionable market research, start a two-week free trial to Bespoke Institutional.
US companies’ massive cash hoard is finally coming down Financial reserves dropped 10% in the first half of last year, Moody’s finds Share on Twitter (opens new window) Share on Facebook (opens new window) Share on LinkedIn (opens new window) The cash holdings of US companies fell nearly 10 per cent in the first half of this year, signalling a turning point in the historic financial reserves they amassed in past two decades. Corporate America’s cash mountain peaked at close to $2tn at the end of last year, according to rating agency Moody’s. Some 70 per cent of the money had piled up offshore, as companies hoarded their overseas profits rather than face tax charges by bringing them home and spending the money on things like acquisitions and stock buybacks. But US tax reforms enacted at the end of last year subjected all past profits to tax, though at a lower rate, ending the incentive to hoard. That released the cash that had been stranded offshore and by the middle of this year total cash reserves had fallen $190bn, or 9.5 per cent, according to a Moody’s calculation published on Tuesday.
Moody’s Investors Service said yesterday that the 928 U.S.-based, non-financial companies it covers claimed $1.7 trillionin cash and liquid investments at the end of 2018.
That’s an eye-popping number. But it’s also down 15.2% from a record $2 trillion in corporate cash a year earlier.
Driving the news: 2018’s drop in cash hoards serves as a master class in chain reactions.
Cash piles shrank because companies funneled record amounts toward share buybacks, M&A, dividends, and capital spending…
And all that happened because of the late-2017 Tax Cuts and Jobs Act. The tax overhaul dropped levies on foreign income so companies could put it to use instead of letting it collect dust in European banks like Gringotts.
And put it to use they did. Last year, capital expenditures leaped 12% to $851 billion, dividends climbed 6.7% to $412 billion, and net share buybacks almost doubled to $467 billion.
The top five cash-holders last year—Apple, Microsoft, Alphabet, Amazon, and Facebook (heard of ’em?)—held 33% of the total balance in 2018. Apple alone laid claim to 14.5%, a balance larger than the aggregate amount for every other non-tech U.S. sector.
Before the tax overhaul…
U.S.-based companies had slowly built up giant cash reserves in foreign countries, keeping profits at arm’s length from the frightful 35% corporate tax they faced when bringing it home.
Then in 2017, changes in the tax code opened the floodgates for what’s known as “repatriation.” The Commerce Department said companies sent $664.9 billion in foreign earnings back to the U.S. as dividend payments in 2018, up from $155.1 billion a year earlier.
Looking ahead…Moody’s Point is that companies will continue to put money to use paying down maturing debt, boosting buybacks, and upping dividends until there’s a reason not to. Look for those piles of to keep shrinking.
The municipal bond market has evolved significantly over the last decade. Historically, many municipal bonds were backed by insurance, which resulted in AAA credit ratings and a high correlation to US government bonds. Today, few municipal bonds are backed by insurance, increasing the diversity of municipal bond credit ratings while reducing their correlation to government bonds.
‘Disappointing’ jobs report pressures Fed to act, economists say
Interest-rate cut probabilities stay ‘high’ after report ByROBERTSCHROEDER
Economists said the May jobs report didn’t offer much in the way of good news but that it increased bets the Federal Reserve would cut interest rates before the year is over.
The U.S. created only 75,000 new jobs in May and employment gains in the prior two months were scaled back, offering more evidence that the economy is slowing. The unemployment rate was flat at 3.6%. The increase in new jobs was way below the 185,000 MarketWatch forecast
U.S. stock futures DJIA, +1.16% pivoted higher after the report was released.
Greg Daco, chief U.S. economist at Oxford Economics, called the overall report “disappointing.”
US #jobsreport: disappointing +75k jobs May:
– large downward net revisions -75k
– 12-mo avg still strong 196k
– 3-mo avg points to cooling labor market 151k
– #unemployment rate stable 3.6% (50yr low)
– labor force part 62.8%
– wages +0.2% & cools to 3.1% y/y (but still >3%)
Liz Ann Sonders, chief investment strategist at Charles Schwab & Co., said the report “keeps [interest] rate cut probabilities high.”
Weak jobs, consistent with @ADP: 75k nonfarm payrolls in May (retail biggest loser); both April & March revised down for total of 75k; UR steady at 3.6%; AHE +0.2% … keeps rate cut probabilities high
“NFP came in quite a bit weaker than expectations (we’re missing the 1-handle here), confirming what we saw in the ADP data earlier this week. A quick glance across the various industries shows that the weakness was widespread as well. AHE was also a bit soft, decelerating to 3.1% YoY. There were also downward revisions to last month as well. Unfortunately, there isn’t anything particularly encouraging in this survey.” — Thomas Simons, senior vice president, fixed income economics, Jefferies LLC.
Martha Gimbel, research director of Indeed.com, said it’s “frustrating” that wage growth isn’t continuing to pick up. The 12-month rate of hourly wage gains slowed to 3.1% from 3.2%.
Frustrating that wage growth is not continuing to pick up – one would expect it to continue to accelerate at this point in this cycle
“This report, combined with nerves around tariffs, will be enough to force a rate cut from the Fed in either June or July. Whether that is enough to satisfy markets will depend largely on how trade policies evolve.” — Curt Long, chief economist of the National Association of Federally Insured Credit Unions.
9.Read of the Weekend…What Happens if Yields Shot to 4%?
If the bulls have momentum, they lack a margin of safety. Even a 4% yield (never mind a 14% yield) would wreak havoc on a government-bond portfolio. As it is, Germany’s 10-year Bond yields minus 23 basis points and commands a price of almost 105. If yields shot to 4%, that safe haven would suffer a 33% loss of principal. Britain’s 10-year gilt yields 86 basis points and changes hands at a price of 107. Lift that yield to 4% (a future Prime Minister Jeremy Corbyn might do it all himself) and you are staring at a 24% drawdown in price. Here in America, the same hypothetical yield upsurge would cost you 15% of your principal.
Could it happen? Only consider what people of a certain age have already seen: unprecedented extremes in interest rates, the invention of radical monetary policy, the Republican Party’s embrace of the essential tenets of modern monetary theory, the Fed’s shift from the Volcker-era doctrine of killing inflation to the post-Ben Bernanke program of nurturing that former scourge, and the shriveling of real yields almost to the vanishing point.
Lower and lower interest rates for ever and ever? It generally doesn’t work that way.
Some people who want self-improvement prefer deep dives into a particular technique. Others prefer quick-and-dirty. This article is for the latter.
As I think back on my 5,500 career and personal coachingclients, I believe these 10 items are most central to self-improvement:
Put in the time. There’s no substitute for time-on-task. “Working smarter” takes you only so far and, chances are, if you’re reading an article on self-improvement, you’re probably already working as smart as you can yet still feel the need to significantly improve. Whether it’s building on a strength or remediating a weakness, your choice is to push harder or to be satisfied with modest growth. I don’t necessarily criticize the latter: It’s called “satisficing” and it can be a wise approach. Perhaps your time could be better spent getting better at something else, taking care of necessities, or simply having fun.
Avoid time-sucks. That is what enables people to put in the time without working too many hours. Accomplishers avoid such time-sucks as excessive TV watching, chatting, clothes shopping when you already have more than enough clothes, video-game playing, time-consuming sportslike golf, and going to a second cousin twice-removed’s third wedding in Kalamazoo.
Focus on what you can control. Successful people spend little time jawboning about their illness, politics, or people they can’t stand. They focus on what’s in their sphere of influence.
In our ever more complicated world, it’s ever more difficult to be good enough as a generalist. You need to be at least relatively expert in some niche. For example, the generic marriage-and-family therapist could well be beset by the imposter syndrome because there’s so much science and especially art to marriage-and-family counseling. Unless you’re unusually brilliant and hard-working, it’s wiser to specialize in something: for example, interracial couples, transgendercouples, intellectually gifted children, physically abusive parents, men with stay-at-home wives, etc.
Take low-risk actions. Excessive rumination can lead to more fearand less accomplishment. So after a modest amount of reflection and perhaps research, follow that widely-agreed-on key to success: Ready, FIRE, Aim! That is, it’s far easier to revise your way to excellence than to think it up in the abstract. You need the feedback of empiricism to adjust what you’re doing. I like to invoke the metaphor of the person who’d like to sail from San Francisco to Hawaii. Yes, s/he should plan, but after just moderate planning, s/he’d be wise to set sail. On encountering the winds, the weather, s/he can adjust the plan. S/he’ll likely get to Hawaii far faster than would the excessive planner.
Hang with people who bring out the best in you. Whether it’s a boss, romantic partner, platonic friend, or activity partner, some people bring out the best in us while others drag us down. Of course, you can’t always control who’s in your life but, when you have discretion, spend time with those who help you flower.
Take the time to find a fine mentor(s.) A generous person who is successful and ethical in what you’re trying to develop or who is an all-around winner, is a treasure, and usually having such a mentor is requisite to success for all but the most gifted people. How to find a fine mentor? Ask a question of one or more respected people. If s/he responds and responds well, offer to be of help in any way you can. After a while, if you do your part and you’re lucky, your mentor will offer more help, become your cheerleader and champion, and be willing to open crucial doors for you.
Chart your progress. That can be as simple as, next to your desk, hanging a hand-drawn thermometer with milestones on the side, like nonprofits when they’re trying to raise money. Or give yourself a daily letter grade A to F. Keep that grade to yourself or share it with your social-media friends or real friends.
Look inward. My unsuccessful clients tend to blame their setbacks mostly on externalities: their boss, the economy, their race, their gender, etc. In contrast, my successful clients mainly look inward to see what, if anything, they need to do differently, for example, acquire a new skill, upgrade their attitude, slow or stop their substance abuse, revise their job target upward, downward, sideways, or to a new career that’s more aligned with their natural abilities.
Resolve to rebound. You’ve heard it before but it’s true: Even highly successful people fail. The difference between them and other people is that successful people tend to force themselves, yes force themselves, to rebound, not wallow. They see if there’s a lesson to be learned from the failure and then resolve to succeed at something at least as big. At the risk of being personal, when I was let go as a columnist in the San Francisco Chronicle, after an hour—yes just an hour—of feeling outraged, I channeled the anger. I said, “I’ll show them. I’ll go national! That very day, I sent clips to 10 national publications and since then, I’ve written a lot for such publications as TIME, The Atlantic, and yes, Psychology Today.
1.5% Pullbacks Normal But Less Frequent Than Previous Decades.
With that said, while market “pullbacks” are normal, they have come with much less frequency this decade than most. So far in the 2010s the market has seen a 5% pullback 27 times, or 2.7 times on average each year. This is lower than the overall average of 3.3 per year and much lower than the average of the previous decade of 4.7 per year as the 2000s experienced a total of 47 such moves.
This chart from TD Securities shows that traders in the fed fund futures market now foresee around two rate cuts before the end of 2019 as heightening trade tensions have stoked worries over the economic outlook. Expectations of easier policy gained ground on Friday after President Donald Trump threatened to wield tariffs against Mexican imports unless the country stemmed the flow of migrants to the U.S. southern border.
Panic-stricken traders now expect Fed to cut rates twice in 2019, this chart shows
Heightened trade tensions underscore worries about economy
“When the industry starts to move toward commoditization over the next decade,” says Henderson, “Colombia is the only place that makes sense.” An equatorial climate and low-cost, skilled labor give Colombia a clear advantage in agricultural trade. And that makes the nation a threat to North American companies like Canopy Growth (ticker: CGC), Tilray (TLRY) andAurora Cannabis (ACB). These firms have invested hundreds of millions of dollars in building the climate-controlled grow-operations needed to grow weed in cold latitudes.
Most Canadian companies nurse the long-term hope of getting their production costs below two Canadian dollars per gram of cannabis. Colombian producers say their costs will start well below 50 cents a gram—and go down from there.
The Next Threat to Big Marijuana Companies Comes From Way South of the Border
1.Search for Yield….Investors Pile into Junk Munis.
Investors seeking yield are piling into the riskiest corner of the municipal bond market at a pace not seen in decades.
They have poured $8 billion into funds that deal in high-yield muni bonds—or junk munis—this year, the most through May since at least 1992, according to Refinitiv data. Muni-bond funds overall have attracted $37 billion during that same period, the most in almost three decades.
Risky Municipal Bonds Are on a Hot Streak
Funds dealing in high-yield munis have drawn $8 billion as investors search further afield for returns
1.Asset Allocation Changes…Money Flowing to Large Cap and Emerging Markets.
SPDR BLOG
Asset allocation: Bullish on emerging markets, bearish on high yield
With respect to asset allocation trends, the chart below reveals where investors are willing to increase or decrease exposure as we head into the second half of 2019. Any asset class below the line indicates more bullish sentiment, where respondents are more inclined to increase allocations relative to the percentage seeking to decrease. Investment-grade credit has the highest ratio of increase to decrease percentages, reflecting the strongest agreement among respondents on where to position. This indicates investors’ preference to move up in quality this late in the cycle.
Emerging markets is a key area where investors are increasing allocations, with 40% of those surveyed indicating that they plan to do so. This is likely a result of the attractive valuations in the region combined with supportive demographic trends. However, we note that this survey was taken while trade tensions appeared to be softening. As recent rhetoric has reignited fears of a trade war escalation, the results of this survey might look somewhat different today.
On the bearish side, investors cited high yield bonds as an area where they plan to reduce allocations, with 30% planning a decrease. High yield not only had the highest decrease percentage, but also had the highest ratio of decrease to increase. As credit spreads continue to tighten—currently they’re 34% below the long-term 20-year median—high yield bonds present less upside relative to downside on a forward-looking basis,1 and may partially explain these survey results.
Consistent with our theme of ‘cautiously optimistic’ attitudes toward US equity markets, US large cap results were mixed. While investors are planning to increase their small-cap allocations, they are also expecting to increase allocations to cash. Lastly, while broad developed ex-US is on the bullish side of the ledger, specific country or region allocations to Europe or Japan are not. The latter reflects the unwillingness of investors to take on country- or region-specific risk, but rather be broadly diversified outside the US.
What happens to the stock market during a recession?
Even if a recession does not appear to be imminent, it’s never too early to think about how one could affect your portfolio. That’s because bear markets and recessions usually overlap at times — with equities leading the economic cycle by six to seven months on the way down and again on the way up.
During a recession, the stock market typically continues to decline sharply for several months. It then often bottoms out about six months after the start of a recession, and usually begins to rally before the economy starts humming again. (Keep in mind, these are market averages and can vary widely between cycles.)
Aggressive market-timing moves, such as shifting an entire portfolio into cash, can backfire. Some of the strongest returns can occur during the late stages of an economic cycle or immediately after a market bottom. It’s often better to stay invested to avoid missing out on the upswing.
Economic indicators are a way to take the temperature of the U.S. economy. One or two negative readings could be meaningless. But when several key indicators start flashing red for a sustained period, the picture becomes clearer and far more significant. In our view, that time has not yet arrived.
Although some imbalances are developing, they don’t seem extreme enough to derail economic growth in the near term. The culprit that ultimately sinks the current expansion may one day be obvious: Rising interest rates, higher inflation, or unsustainable debt levels can be major triggers.
These events, if they continue, suggest that the economy could weaken in the next two years, placing a 2020 recession on the horizon. But we are not there yet.
With slowing growth, disparate rates of inflation, and continued policy normalization, volatility in the financial markets is likely to accelerate.
Long term, our ten-year outlook for investment returns remains guarded, given the backdrop of high valuations and depressed risk-free rates across major markets.
Returns in global equity markets are likely to be about 4.5%–6.5% for U.S.-dollar-based investors.
We do, however, foresee improving return prospects in non-U.S. developed markets, building on slightly more attractive valuations.
U.S. fixed income returns are most likely to be in the 2.5%–4.5% range, driven by rising policy rates and higher yields across the maturity curve as policy normalizes.
Ten-year projected return ranges
U.S. equities: 4.0%–6.0%
U.S. aggregate bonds: 2.5%–4.5%
International equities: 5%–9.5%
International bonds (hedged): 0%–4.0%
IMPORTANT: The projections and other information generated by the Vanguard Capital Markets Model® (VCMM) regarding the likelihood of various investment outcomes are hypothetical in nature, do not reflect actual investment results, and are not guarantees of future results. Distribution of return outcomes from VCMM are derived from 10,000 simulations for each modeled asset class. Simulations as of December 31, 2018. Results from the model may vary with each use and over time. For more information on VCMM, see the Important Information.
U.S. steelmakers woke last week to the brutal reality of evaporating tariffs on Canadian and Mexican steel. But an even greater problem is waiting in the wings: China may soon be tempted to ship more of its unwanted steel to foreign shores.
President Trump said Friday that the 25% tariffs he imposed on Canada and Mexico in mid-2018 would be lifted and that both countries would drop retaliatory levies. That removes a major hurdle to congressional approval for Mr. Trump’s revamped Nafta, the U.S.-Mexico-Canada Agreement.
U.S. steel companies will certainly take a hit, given that the tariffs boosted U.S. prices significantly above the global average for most of 2018, at the expense of steel-consuming industries like oil and autos. Even with the 25% tariff, imports of Canadian and Mexican hot-rolled coil steel are roughly 5% cheaper, according to Moody’s.
Trump, Tariffs and China Spell Trouble for American Steel
The vanishing levies on Canada and Mexico could be just the beginning of the industry’s problems
Today Eurozone banks are lagging the market, but that’s nothing new. During the mid-2000s banks were the key drivers of European equity market performance, outperforming by almost 40% from mid-1999 through mid-2007. Since, it’s been a seemingly never-ending series of disasters: the global financial crisis, the Eurozone crisis, non-performing loan build-ups, recapitalization, negative interest rates, and more. As a result, Eurozone banks have underperformed the broadest measure of European stock prices by 77% since the 1990s came to a close. How much lower can this ratio go? Buying Eurozone banks here would certainly qualify as “buying low.” Start a two-week free trial to Bespoke Institutional to read more on international equity markets and the global macro backdrop.
Google, Qualcomm and Broadcom are among the companies that have reportedly frozen their supply of components and software to the Chinese technology giant to comply with a crackdown by the Trump administration.
“Google has suspended business with Huawei that requires the transfer of hardware, software and technical services except those publicly available via open source licensing,” Reuters reported, citing unidentified sources.
“Chipmakers including Intel, Qualcomm, Xilinx and Broadcom have told their employees they will not supply Huawei till further notice,” Bloomberg added, also citing unnamed sources.
The moves follow a Trump administration clampdown. The Commerce Department announced last week that U.S. companies would need special permission to sell some products to Huawei.
It’s not yet clear how long or deep the crackdown will be. Some commentators have said that it could be a short-lived part of U.S. trade war posturing. But the administration has been vocal about its concerns over possible threats to national security, and Huawei has said that it was prepared for being frozen out.
How the moves could hurt Huawei. Existing products would continue to receive Google updates, but future devices would have to use the open-source version of the operating system, without services like YouTube and Google Maps. The chip freeze-out means it might be forced to use its stockpile of U.S. components.
“We can now expect China to redouble efforts to roll out a homegrown smartphone operating system, design its own chips, develop its own semiconductor technology (including design tools and manufacturing equipment), and implement its own technology standards,” Tim Culpan of Bloomberg Opinion writes. “This can only accelerate the process of creating a digital iron curtain that separates the world into two distinct, mutually exclusive technological spheres.”
8.5 Trends Emerge in the Gartner Hype Cycle for Emerging Technologies, 2018
This year, Gartner organized the 17 technologies into five major trends: Democratized artificial intelligence (AI), digitalized ecosystems, do-it-yourself biohacking, transparently immersive experiences and ubiquitous infrastructure.
“As a technology leader, you will continue to be faced with rapidly accelerating technology innovations that will profoundly impact the way you deal with your workforce, customers and partners. The trends exposed by these emerging technologies are poised to be the next most impactful technologies that have the potential to disrupt your business, and must be actively monitored by your executive teams,” says Mike Walker, Research Vice President at Gartner.
Widespread artificial intelligence, biohacking, new platforms and immersive experiences dominate this year’s Gartner Hype Cycle.
A lot of ink has been spilled and consultant hours racked up talking about the ins and outs of hiring heuristics. What deeply nuanced psychological traits should we be looking for? What tactics can you use to see them? What’s the one surprising trick that will help you identify the exceptional among the average?
According to some of the so-called savviest of executives, the secret to identifying future stars lies in the following interview questions:
“On a scale of one to ten, how weird are you?” (Tony Hsieh, Zappos founder)
“What’s your spirit animal?” (Ryan Holmes, Hootsuite)
“What would you do in the event of a zombie apocalypse?” (Ashley Morris, Capriotti’s)
“What was the last costume you wore?” (David Gilboa, Warby Parker)
While these prompts might lead to delightful conversations, no candidate’s response will indicate how well they’ll be able to do a particular job. Not to mention: How does one stack-rank applicants who most recently dressed up as an ice cream sundae or a box of crayons?
The truth is, the best way to hire isn’t outrageous, groundbreaking, or clickbaity. It’s incredibly structured and boring. And that’s why no one does it.
Too many people see hiring as an instinct art form, honed by years of their own experience: when asked, three-fourths of people involved in the interview process at elite law, banking, and consulting firms admitted to making hiring decisions based on their gut.
How does one stack-rank applicants who most recently dressed up as an ice cream sundae or a box of crayons?
But our instincts are rarely, if ever, scientifically valid. Humans are error-prone creatures. We get excited about people who have impressive zombie apocalypse strategies or send thank you notes—and then we hire them over candidates who might have become our best-performing employees.
To test how helpful interviews really are, Yale professor Jason Dana and his colleagues had two groups of students predict their classmates’ GPAs. One group had access only to past GPAs and current course lists, while the other was also allowed to conduct free-for-all interviews. The students who interviewed their classmates were over 50 percent worse at predicting future GPA.
To fix the hiring process, we have to replace hubris with heuristics. Here are five steps to identifying the very best candidates. **
**Warning: the rest of this article might seem dry, but I promise it will improve the quality of your hires.
#1: Define job attributes
The goal of any interview process should be to predict how candidates will perform once they
join the team. Start by clearly outlining what missing skills your team needs to succeed, and identifying themes across people you did hire, as well as those you didn’t. At Google, we found four distinct attributes that predicted whether or not someone would be successful on the job: general cognitive ability, leadership, “Googleyness” (e.g., a dose of humility and comfort with ambiguity), and role-related knowledge. Once we identified these attributes, we required all interview feedback to comment specifically on each one.
#2: Ask for a work sample
This entails giving candidates a sample piece of work, identical to that which they would do in the job, and assessing their performance on it. But even this can’t predict performance perfectly, since actual performance also depends on other skills, and worse, many jobs don’t have nice, neat pieces of work that you can hand to a candidate.
The truth is, the best way to hire isn’t outrageous, groundbreaking, or clickbaity. It’s incredibly structured and boring. And that’s why no one does it.
#3: Ask behavioral questions
Which brings us to interviews. Asking behavioral questions (something like, “Give me an example of a time when you solved an analytically difficult problem”) will get you two kinds of information: one is you get to see how the candidate actually interacted in a real-world situation, and the valuable “meta” information you get about the candidate is a sense of what they consider to be difficult.
Ask candidates a consistent set of questions, in the same order, with clear criteria to assess the quality of responses. This ensures that any variation in responses is a result of the candidate’s performance, not because an interviewer has particularly high or low standards, or asked harder or easier questions.
#4: Average scores and make a decision
The “wisdom of crowds” works for hiring decisions, too. An average score has the virtue of eliminating the ability of a single person to veto or politic for a candidate. Equally weight each interviewer’s rating—a subordinate’s feedback is at least as valuable, if not more so, than a hiring manager’s feedback. And finally, when you sit down to compare candidates, look at and rank all the scores on the first attribute or question. Then look at and rank all the responses on the second one, and so on. This prevents you from focusing on a single candidate for too long, which is when bias creeps in.
#5: Constantly check that your hiring process actually works
Most organizations never go back a year or two after hiring someone to find out if that thank you note really did predict their performance—which is why they keep letting jokes and notes shape their staff. Continue to identify themes across your top performers, and then work your findings into the interview process.
Following these five steps might not feel exciting or entertaining, and in fact that’s why most companies don’t bother. Sometimes doing something right means doing it in a staid, measured, repeatable way. But by doing so you’ll discover that structure and science (not sentiment or social cues) are the keys to a successful—and unbiased—hiring process.
Laszlo Bock is CEO of Humu, a company that’s making work better with science, machine learning, and a little bit of love. He is the author of The New York Times bestseller Work Rules! and the former senior vice president of people operations at Google.
When thinking about how to develop in our careers, most of us tend to focus on promotions, projects, courses, certifications. We seek out expanded roles, more senior titles, extra money. We overlook one very key piece of the learning puzzle: proactively surrounding ourselves with people who will push us to succeed in unexpected ways and, in so doing, build genuinely rich, purposeful lives of growth, excellence, and impact.
Back in the 1990s, when I was working full-time as a partner in our executive search firm, I pursued one such friend—a leading researcher and writer—and cultivated the relationship for several years. And then, in 1998, during a walk along the Charles River in Cambridge, he surprised me with a challenge. He suggested that, in addition to my client practice and internal leadership roles at Egon Zehnder, I could find even more meaning (and have a larger reach) by using my knowledge of and passion for talent-spotting and development to also become a writer, teacher, and public speaker. I took his advice, and it has drastically changed my life, both professionally and personally.
We typically spend at least two decades in our formal education and, in developed countries, hundreds of thousands of dollars. We carefully choose our places of employment and invest significant time and effort in training within them. However, few of us engage in a deliberate, determined search for those wise individuals who, through their inspiration and advice, can literally make us new.
My dynamic circle of advisers and confidantes has included, in addition to my wife María and my Charles River friend, several other academics in the United States, an undergraduate professor in Argentina, a McKinsey director in Spain, and colleagues working in Egon Zehnder offices across the Americas, Europe, and Asia. They have, throughout my career, successively inspired me into different possibilities I would never had envisioned, from teaching statistics to applying for an MBA, from becoming a strategic consultant to spending three decades and taking on global leadership roles in executive search, from publishing books to teaching executives at Harvard.
They have been companions on my journey, offering honest feedback, helping me to discover new identities and pushing me to become a highly different yet significantly better version of myself. How can you find a similar group? The following guidelines should help:
Think about the people who inspire you. These can be teachers of certain disciplines; inventors; entrepreneurs; business, social, or public leaders. I have always been moved and inspired by specific people, not just abstract professions. I “met” them originally in many cases by reading their work or about them, but also via social media and at conferences.
Don’t be afraid to chase. Conferences are a great place to get inspired, approach, and start a relationship with some of the people you’ve identified. Likewise, contacting even top academics is usually much easier than you think. Other cases may require a much more determined investment. For example, I flew back and forth from Buenos Aires to a little town in Massachusetts just to meet my Charles River friend. While this double red-eye may sound excessive, think how little time commitment it was compared to what we invest in our education, or to the opportunity cost and frustration of a poor career choice or wrong job decision.
Aim for a mix of people inside and outside your organization. Lots of healthy change can and should ideally happen within your own company. However, external contacts can potentially have the benefit of greater independence, a broader perspective with radically new horizons, as well as potential connections across both worlds which will benefit everyone.
Be candid about the reason for your interest. Most truly great people live their lives with genuine passion and want to expand their missions. Most times, they will be delighted to both inspire you and help you see how to close the gap between dream and reality.
Ask them specifically about how to get started. After suggesting my new potential persona, my Charles River friend gave me some invaluable advice about what I had to do. He said to me: “You need three Cs: capability, which you have; connectivity, which at least initially you can do through the global network of your firm; and credibility, which you don’t have yet. In order to achieve it, you need to publish a great article in a credible magazine and ideally a book.” He then put me in touch with a senior editor at HBR, with whom I worked to make that first article happen.
Proactively offer them help. These great companions who lead us to greater lives deserve our very best. I have always offered them that, with no strings attached. That included becoming a pro bono assistant professor, conducting intensive research for a full year for someone’s new book, becoming the critical reader of a best-selling author, and much more. And whenever I get a message from them, I drop everything I’m doing and respond right away. I have constantly done this out of gratitude but, as always, I also gained in the form of more learning, opportunities, and deeper friendships.
Have crucial conversations in the right settings. Meeting face-to-face with no distractions will help you reach a level of intimacy which simply can’t achieve remotely. I would add that many of my life-changing moments have occurred while walking with my trusted friends in beautiful surroundings – whether by a river, in the countryside, on the beach, along a snow-covered mountain, or across peaceful villages. One of my Egon Zehnder colleagues and I have done this in more than 30 different parts of the world. The combination of exercise and nature makes me particularly energetic, enthusiastic and positive – and therefore more willing to consider new possibilities.
Don’t hesitate to ask the truly big questions. What shall I do with my life? What really motivates me? What am I doing that I really don’t like to do? While pondering these questions, in addition to checking my capability, connectivity and credibility, I also engage my friends in conversation about three other Cs: contemplation (Am I in touch with my inner compass?), compassion (Do I show it for myself and others?), and companions (Who else might inspire me to new growth?)
Proactively seeking out and cultivating those who will help us become better versions of ourselves is, by a wide margin, the key for living a truly happy and meaningful life. I sincerely hope these guidelines help you.
Despite the news that MSCI announced to double Chinese stocks’ weightings in its global gauge by the end of the month, overseas traders sold 10.6 billion yuan (US$1.54 billion) worth of mainland-traded shares through the exchange links today. That was the biggest single-day outflow since at least December 2016, when the stock connect programme between Shenzhen and Hong Kong started
“The fact that inversion occurred with futures expiration still over two weeks away gives us confidence that this move isn’t just noise (the front of the curve can be volatile near futures expiration) but is actually showing a demand for protection in the market,” said Vinay Viswanathan, an equity derivatives strategist at Macro Risk Advisors – There was record volume in TVIX, the 2x VIX ETF, yesterday
According to chip makers, the plunge isn’t over yet. Now hoping it won’t turn into the mess as in 2001 when the last tech bubble became the dotcom bust.
Global semiconductor sales dropped 15.5% in the first quarter, from the fourth quarter last year, to $96.8 billion, the World Semiconductor Trade Statistics (WSTS) organization reported Monday afternoon. The three-month moving average in March has now plunged 25% from the three-month moving average at the peak last October, the deepest plunge since the Financial Crisis:
Demand was down across all regional markets: The global 15.5% drop in sales from Q4 2018 to Q1 2019 split up regionally this way – and the problem isn’t just China:
1.WeWork IPO…Second Biggest Offering of the Year….$1.9B in Losses Last Year.
The co-working company told employees yesterday that it has confidentially filed paperwork with the SEC to go public.
WeWork reportedly hasn’t picked bankers yet, and an offering wouldn’t happen until the third or fourth quarter of this year. But there’s more you should know about 2019’s latest mega-offering.
It’s as meaty as a WeWork company card will allow
A WeWork IPO would likely be the second-biggest offering in the U.S. this year behind Uber. WeWork was last valued at $47 billion and has 400,000 members in 100 cities.
Still, it’s burning through cash. Though WeWork’s revenue doubled last year to $1.8 billion, its losses more than doubled to $1.9 billion.
It’s not just WeWork
It’s the We Company after a rebranding earlier this year to focus on more than just the short-term office space rental service that (along with its notorious tenant Morning Brew) made it famous. Now, it’s diversified into businesses like housing, a children’s school, and a coding academy.
Wherefore the rebrand? Fend off skepticism over WeWork’s ability to withstand a market downturn, when fewer D2C birdseed startups will look for low-commitment office space. But we may always need apartments for “modern-day nomads.”
And speaking of skeptics…there are plenty. WeWork is a “love it or hate it” company, writes Axios. A “person close to the company” told Axios WeWork could become the second-most shorted stock after Tesla.
But as for believers…
WeWork is no mere co-working company. It serves a higher purpose.
From CEO Adam Neumann: “As one of the world’s largest physical networks, it is our responsibility to help lead the way and set the global example for people and corporations on how we should take care of each other and of our planet.”
Funds have already seen $30 billion inflow, analyst says
Bid to drive down tax bills pushes munis to pricey levels
It’s only four months into 2019, and already mutual funds that invest in state and local-government debt have raked in more cash than they usually do in a year.
Investors added $1.1 billion to such funds in the week ended April 17, the fifteenth straight weekly influx, the Investment Company Institute reported Wednesday. That bumped the total to about $30 billion since January, more than they’ve drawn during any full year since 2012, according to an analysis of the data by CreditSights.
1.U.S. Dollar Big Move Up in April….U.S. Rates Still the Highest in World.
Equities
The stock rally paused on Wednesday, pressured by the rising US dollar. Outside of the trade-related uncertainties, the dollar now poses the highest risk to equities. A firmer dollar tends to make US products more expensive for customers abroad and depreciates the value of foreign earnings for US companies. Imported products in the US become cheaper, making it harder for domestic firms to compete.
Weak economic data out of Germany (see the Eurozone section) and a more dovish Bank of Canada (Canada section) boosted the dollar on Wednesday. Rate differentials with other economies will provide tailwinds for the dollar over the long run.
So far, the 2019 crop of gig-economy IPOs aren’t performing like the dot.com era, when investors just “had” to own internet stocks. IPO research from Jay Ritter shows the first-day return of 476 IPOs in 1999 averaged a whopping 71%. What’s more, the Nasdaq Composite rose another 100% between the middle of 1999 and the market’s peak in March 2000. Dot.com stocks kept working even after internet companies sold shares to the public.
Pinterest Stock Is Hot After Its IPO. Why You Should Keep Your Cool.Al Root
1. No Shortage of Debt Issuance….Record Start to 2019.
Bond sales are booming in 2019, running at a record pace globally for the year so far, as a pivot in monetary policy among the world’s central banks prompts a fresh binge in corporate borrowing – Global corporate bond issuance has reached almost $747bn for the year to Monday, according to FT, edging ahead of the previous record of $734bn issued over the same time period in 2017, which ended up being the biggest year on record for new debt sales.

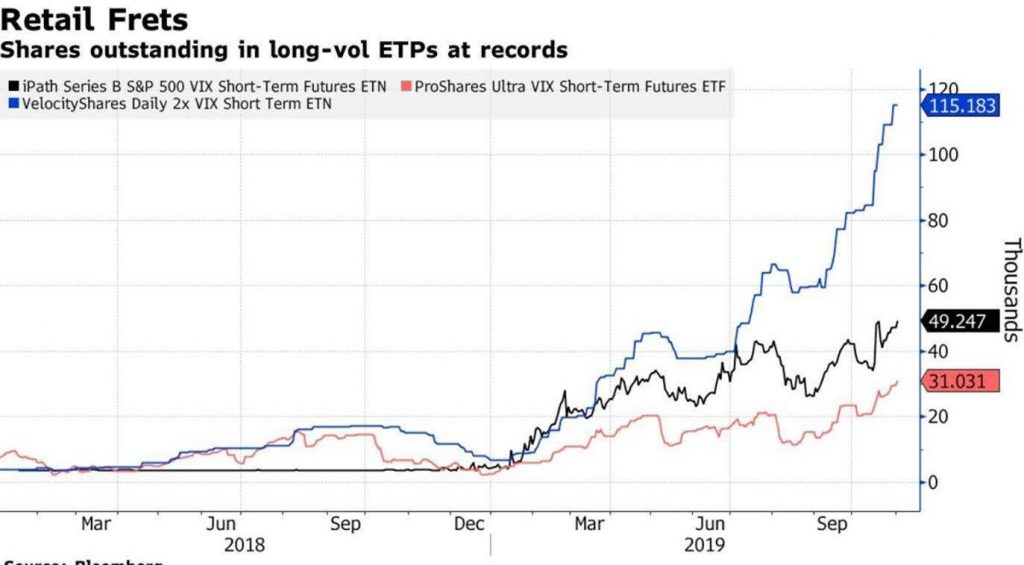
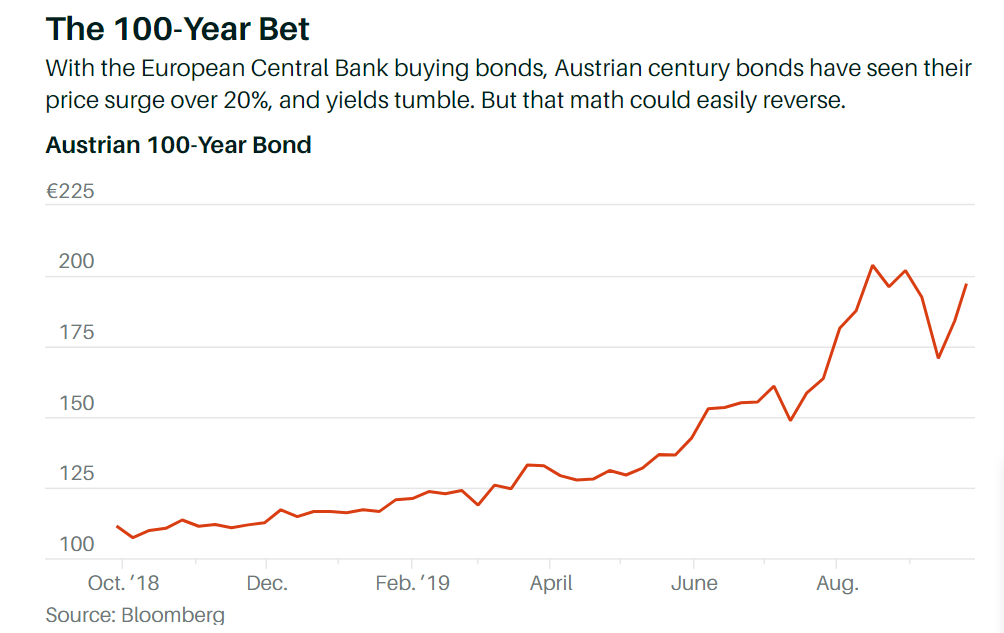
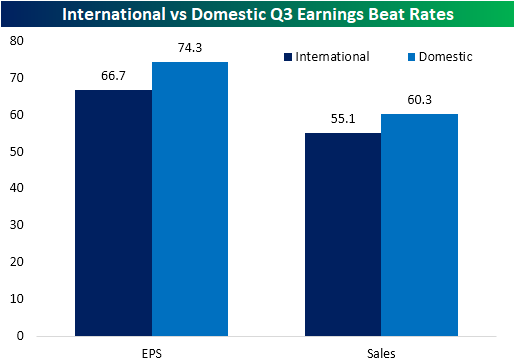
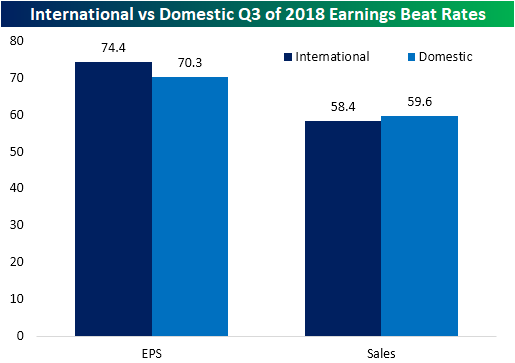
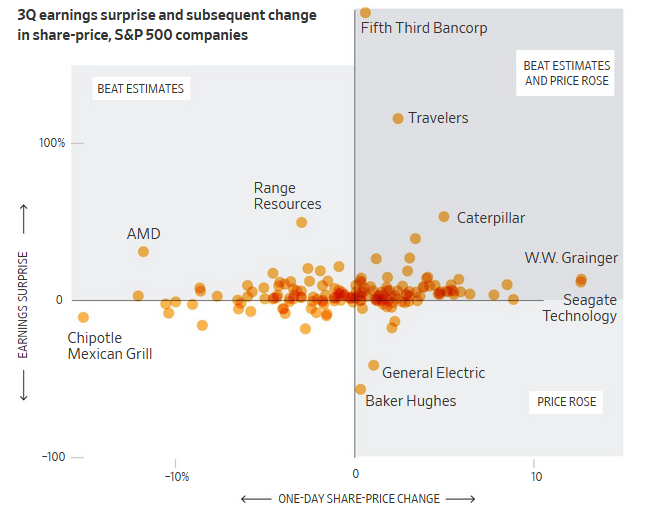
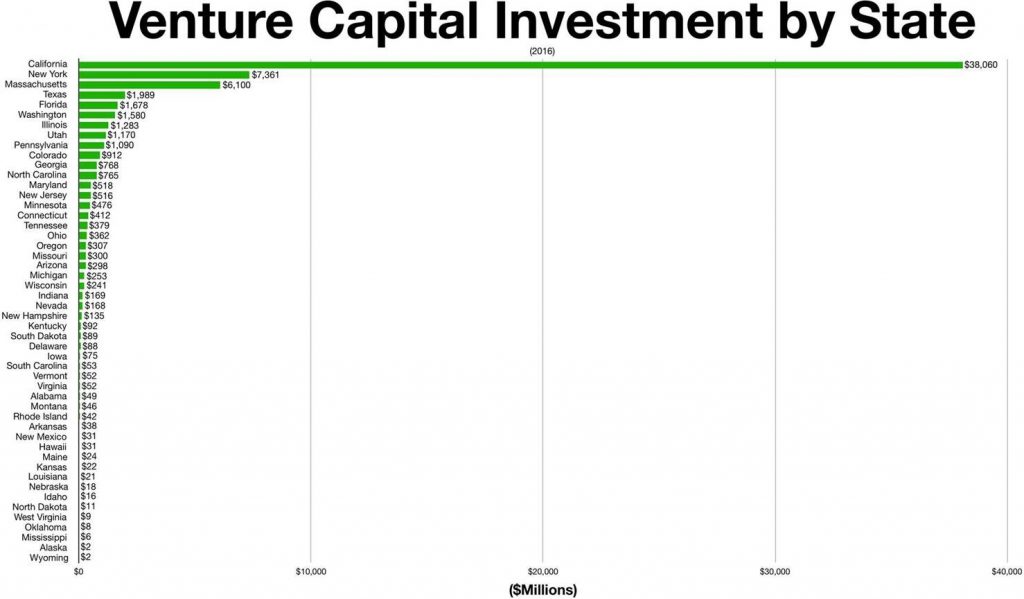
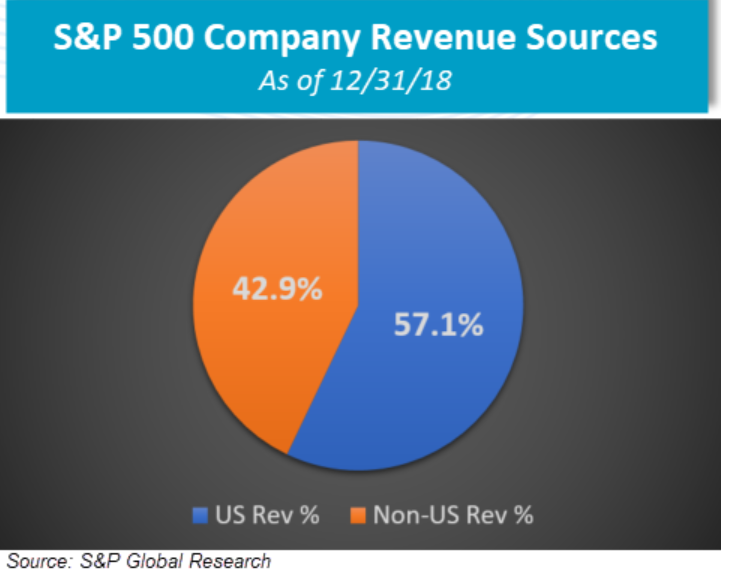
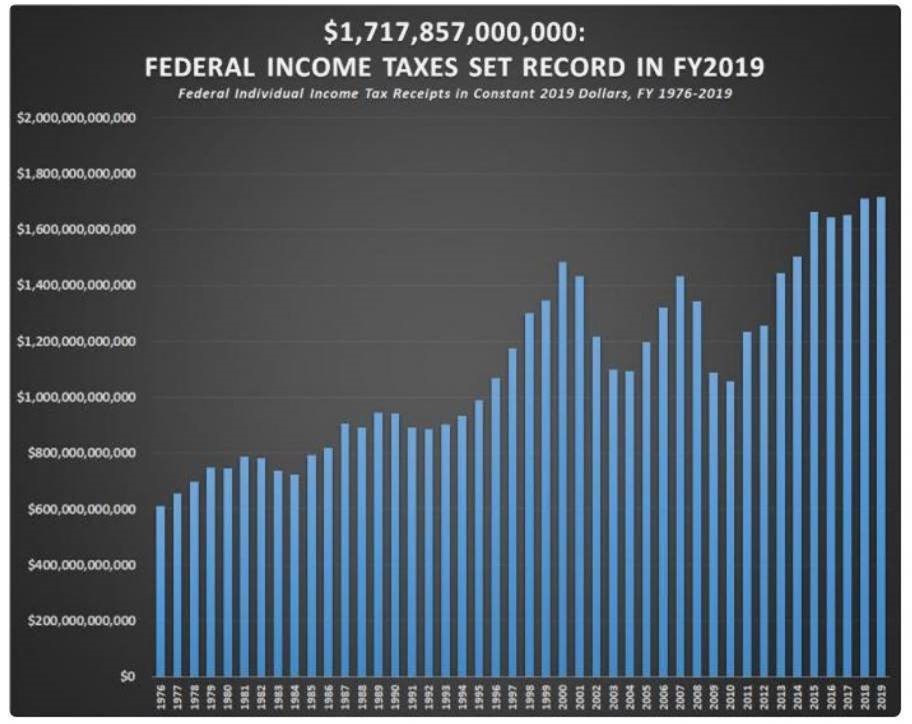
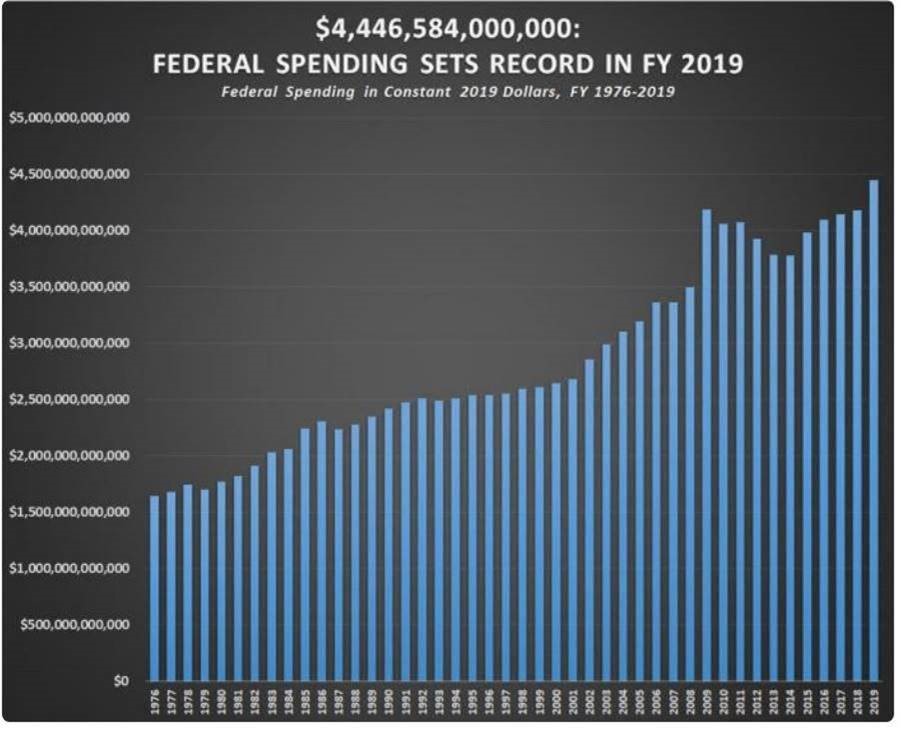
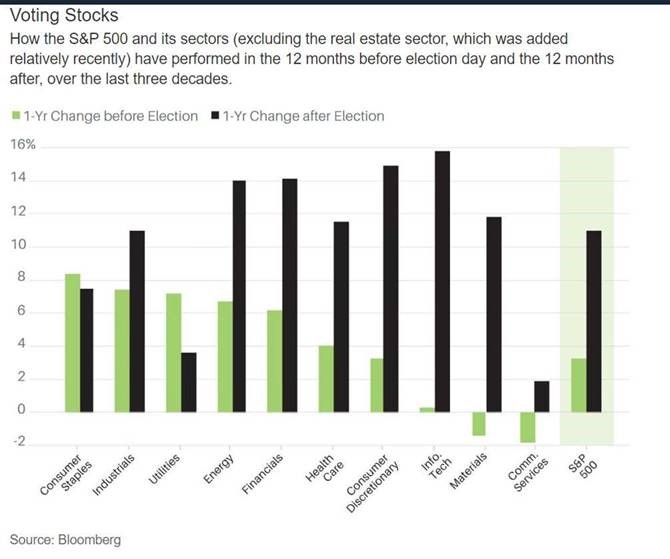
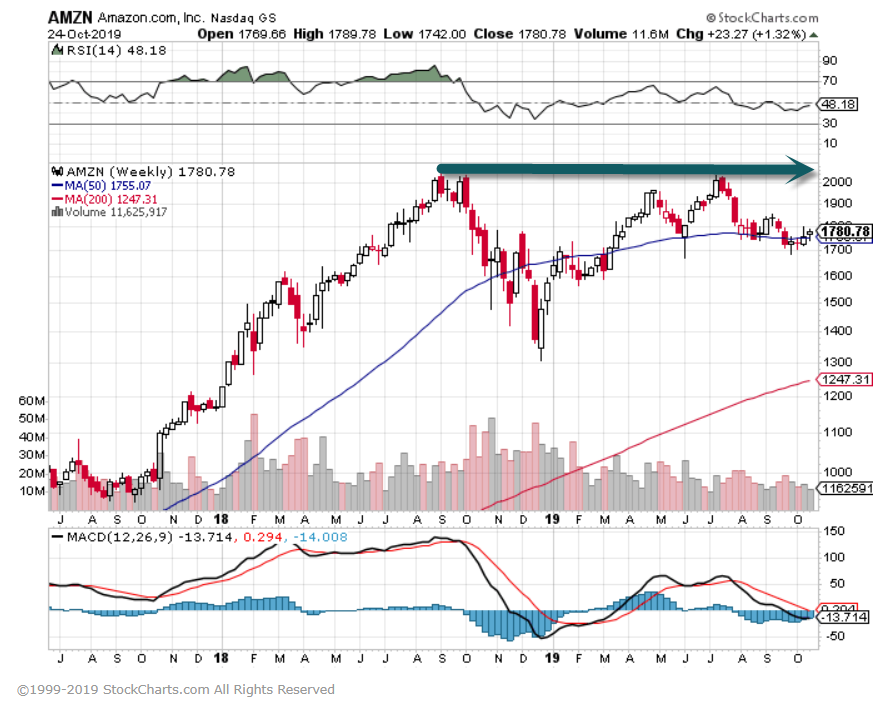
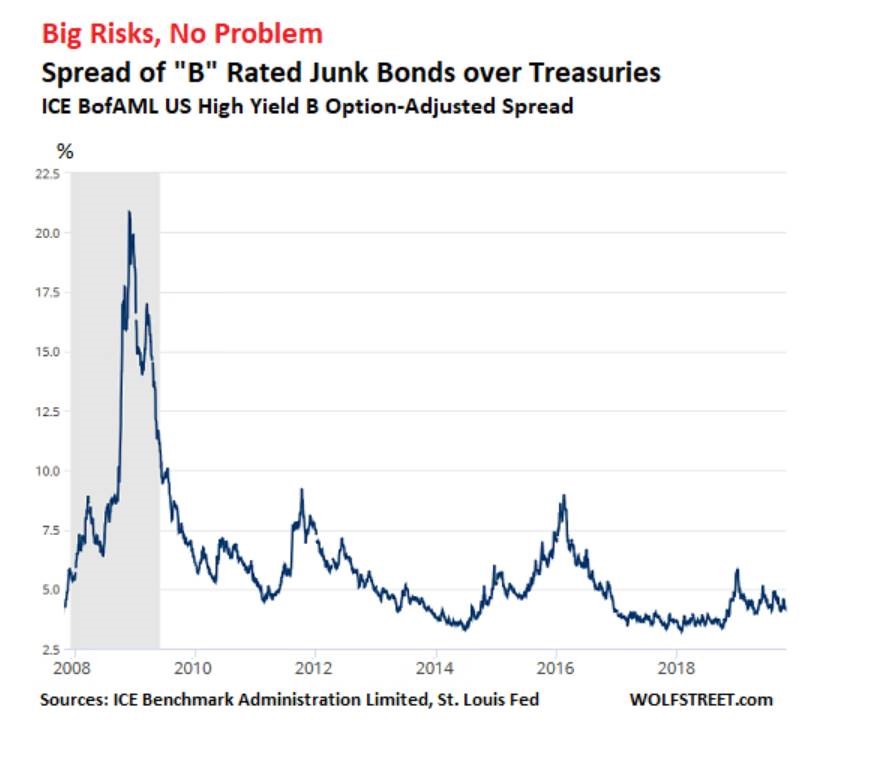
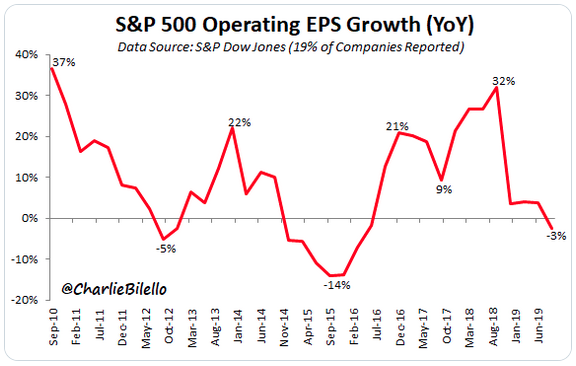
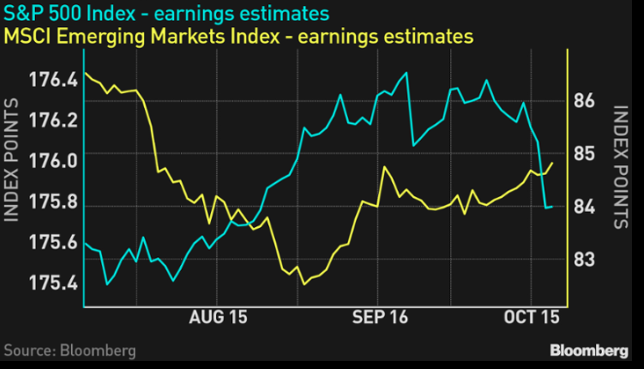
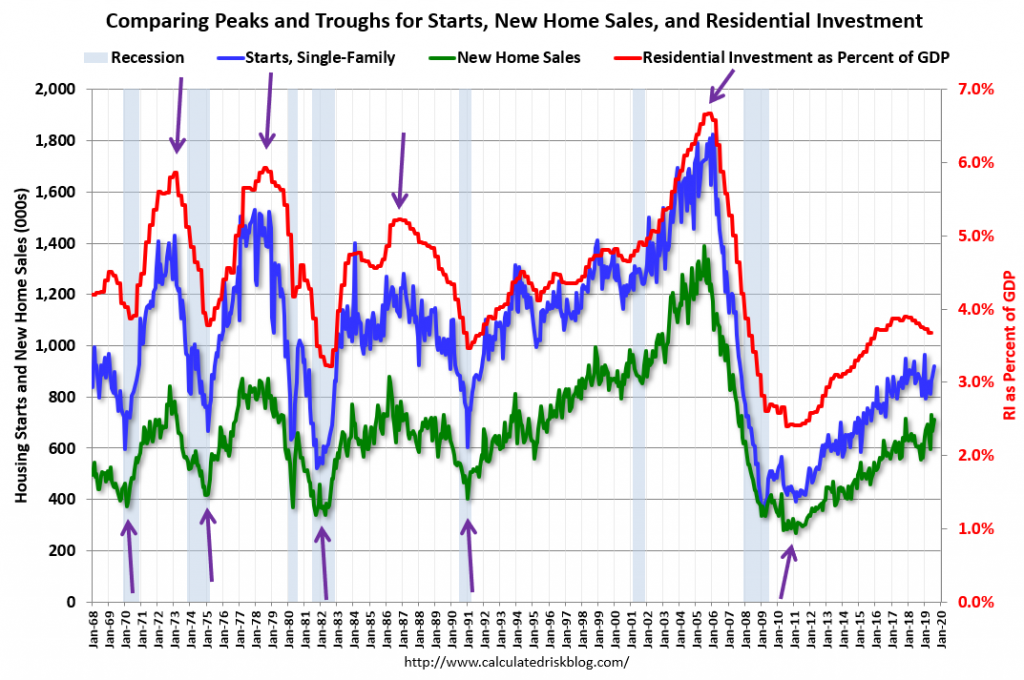
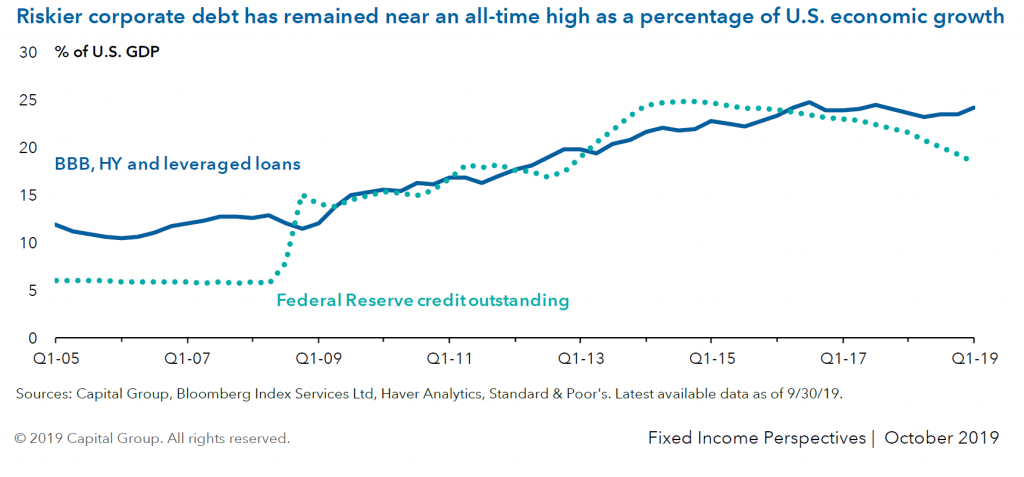
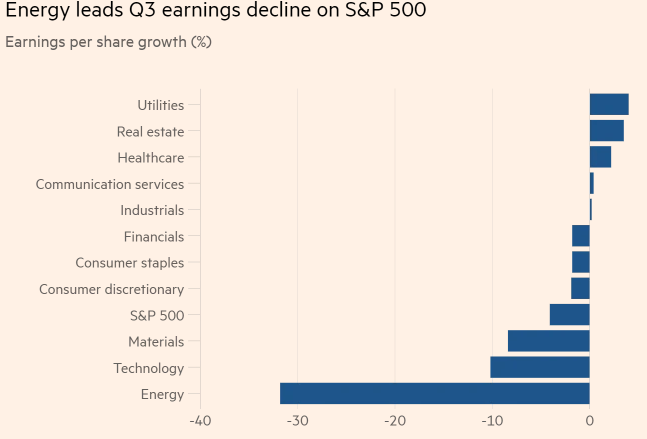


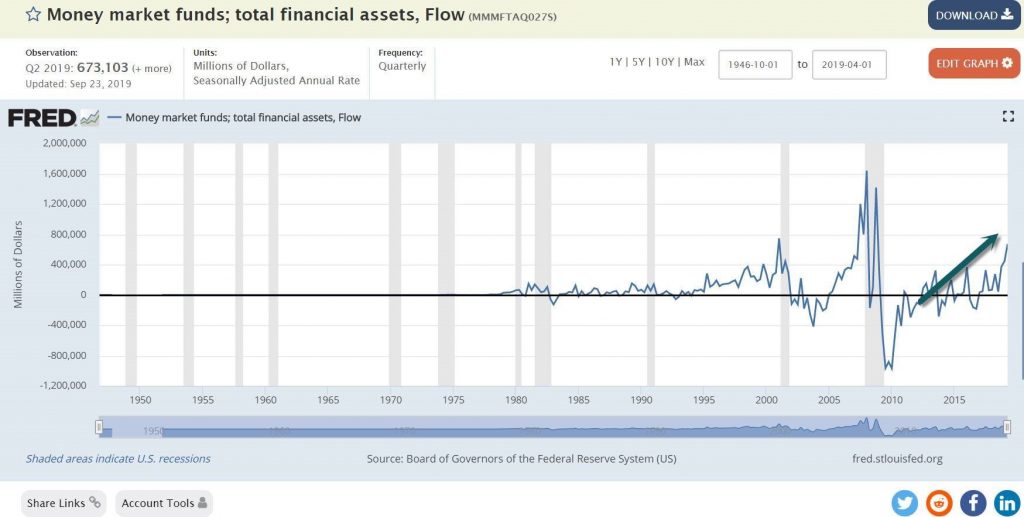
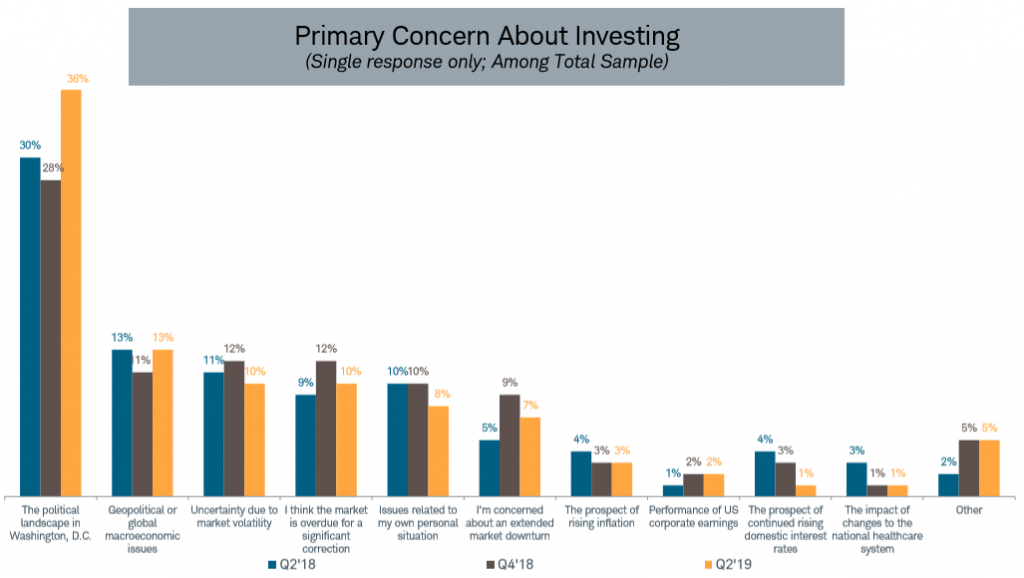
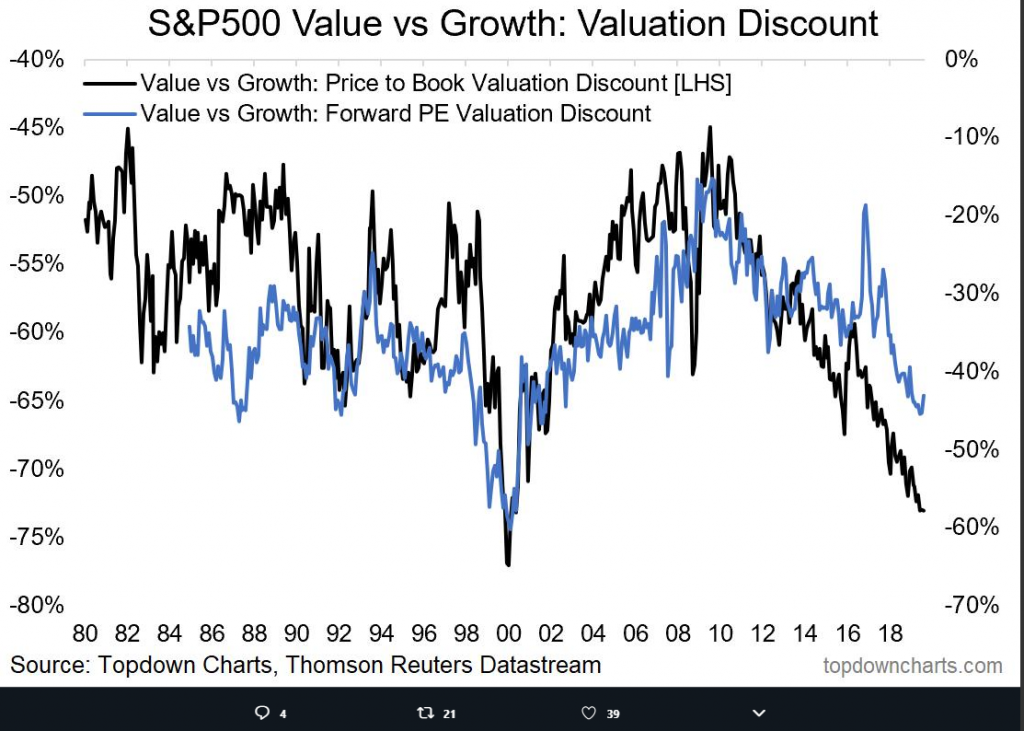
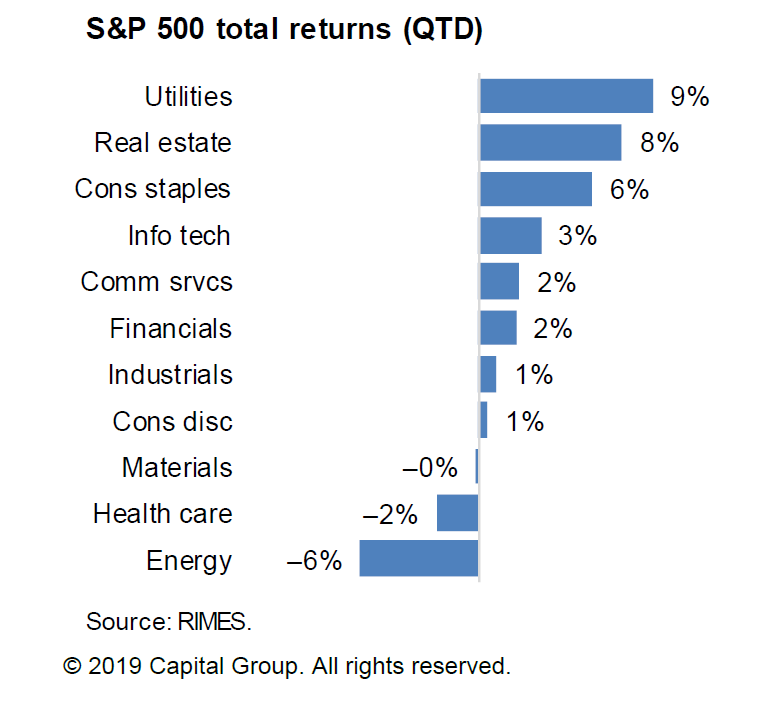
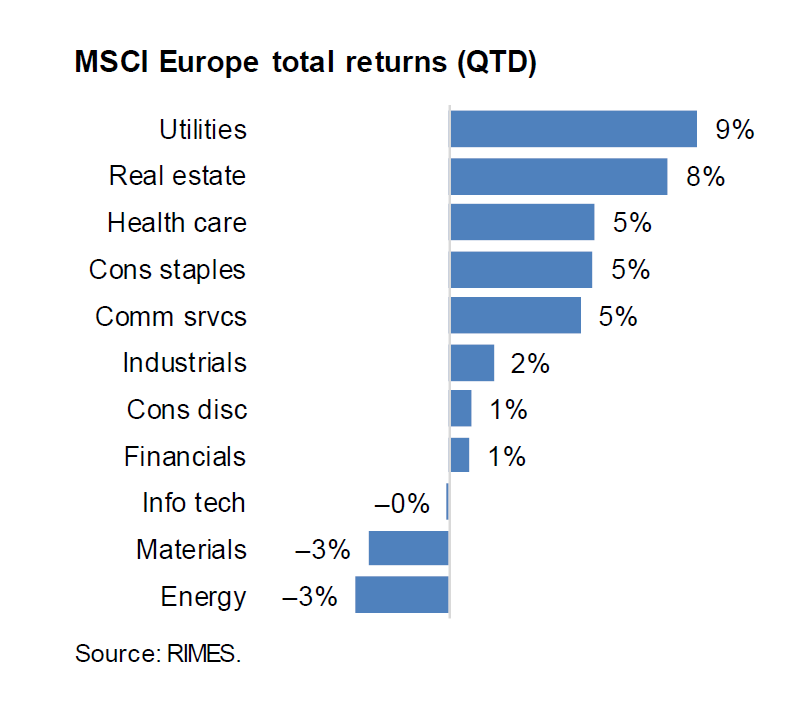
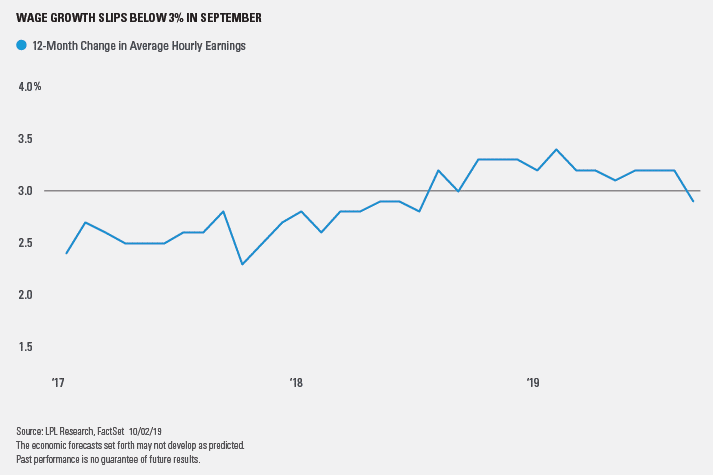
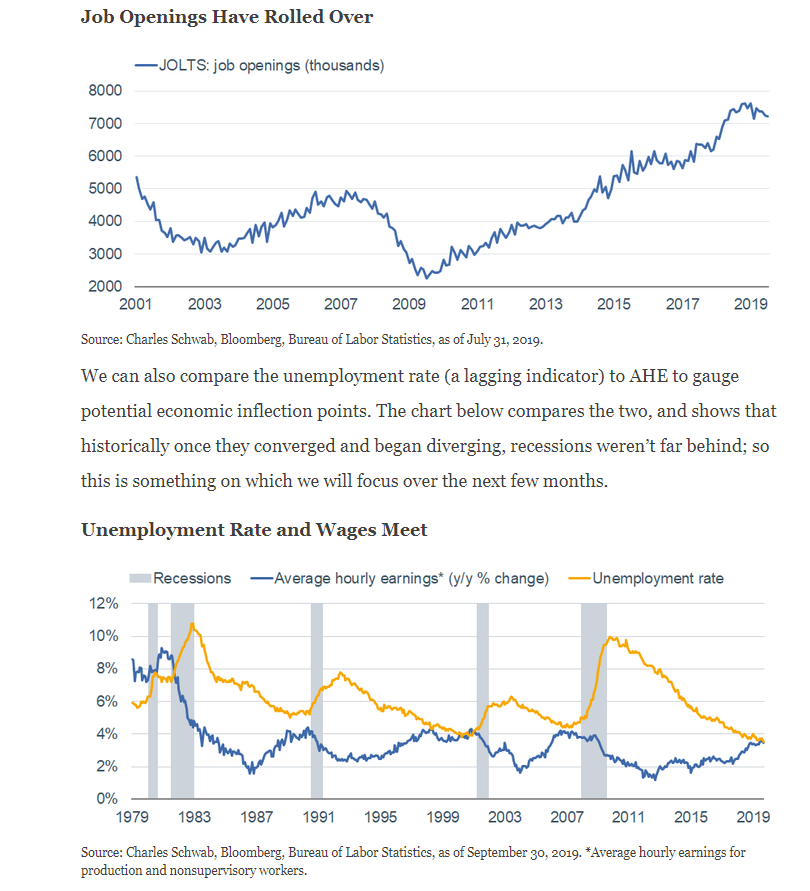


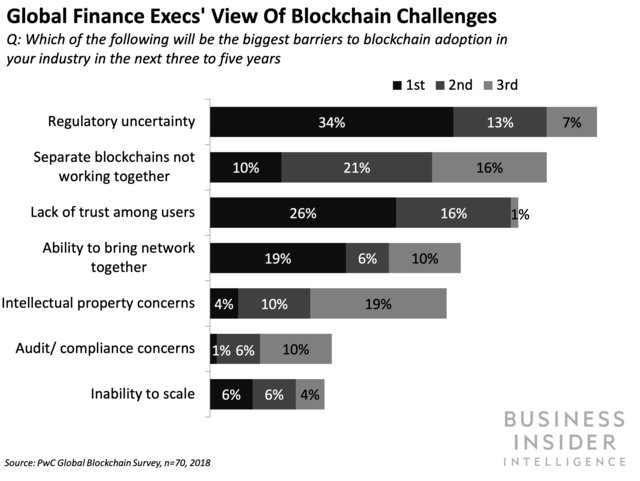
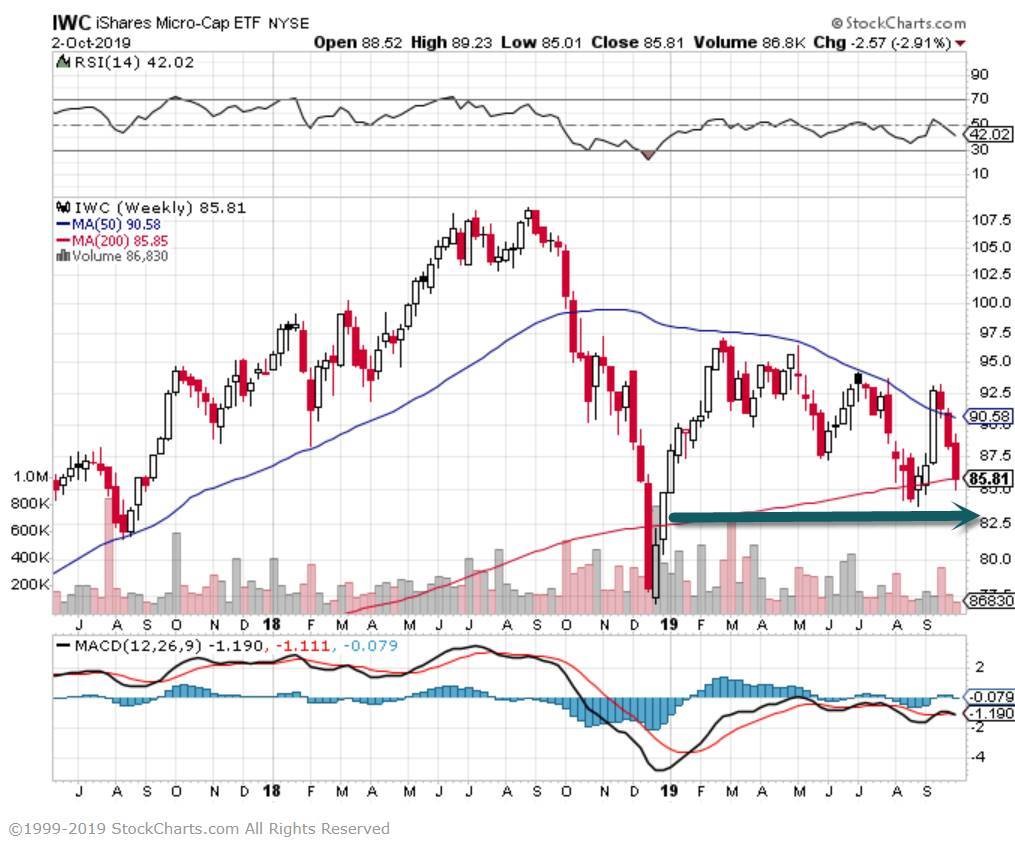
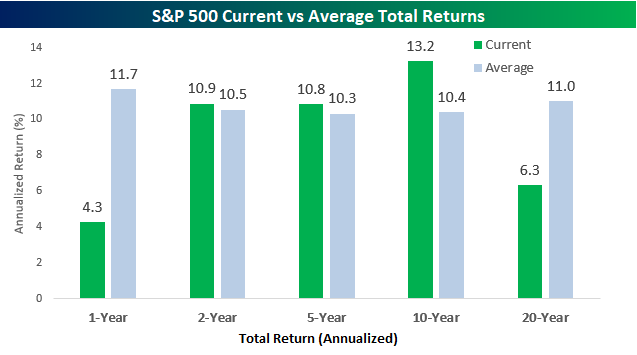
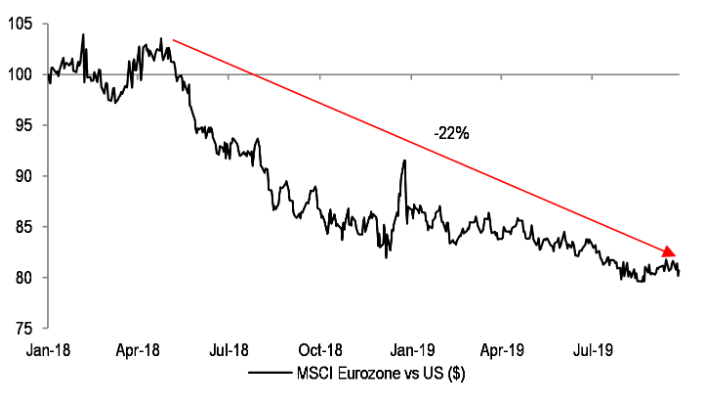
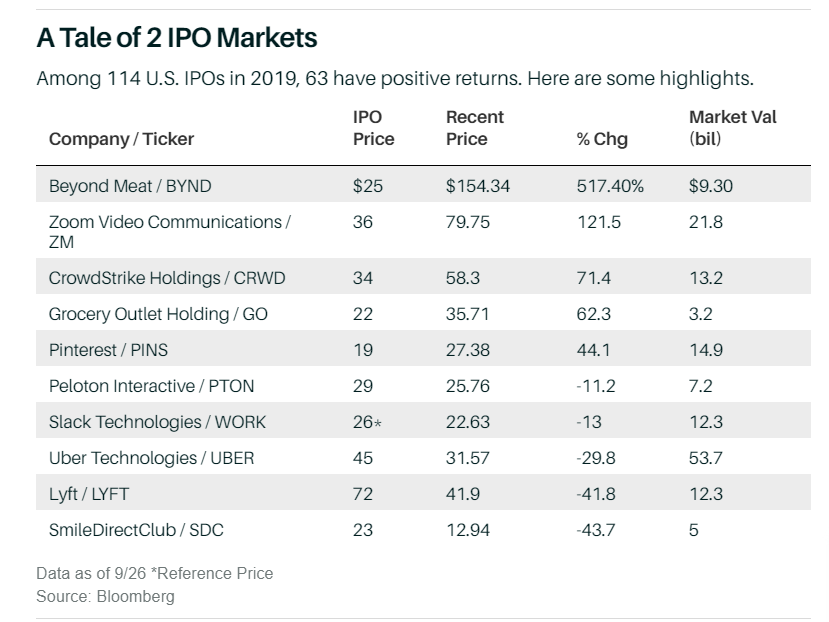
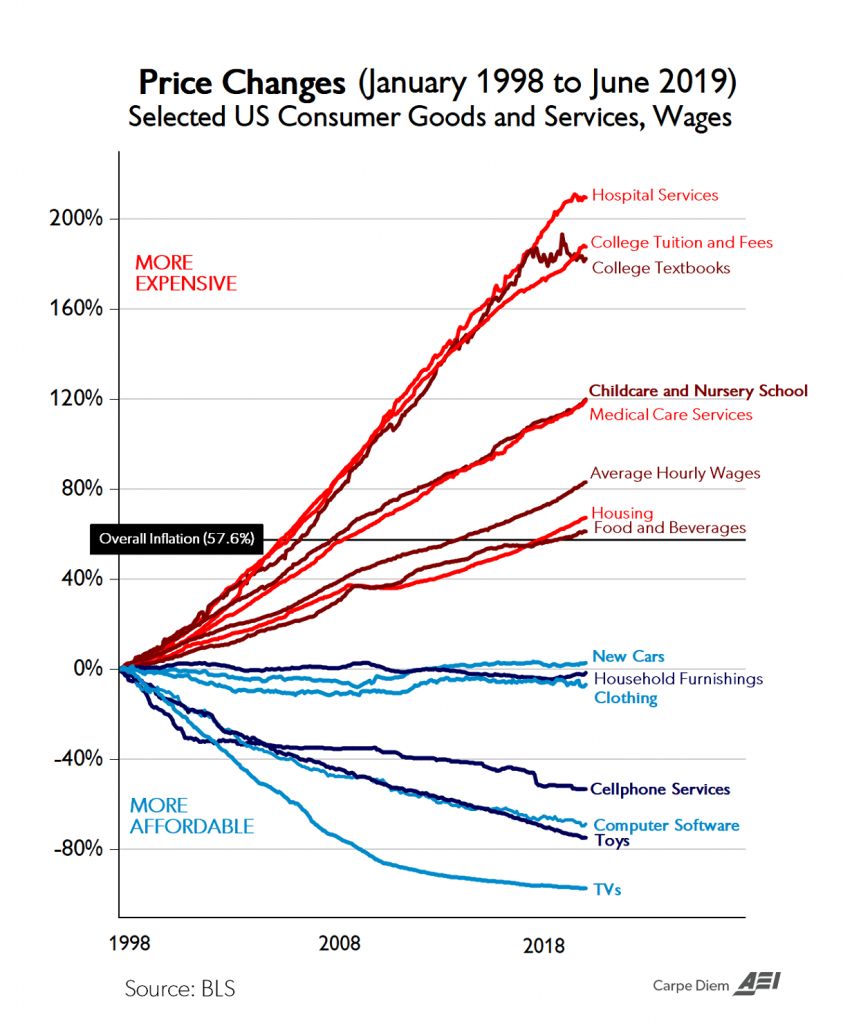
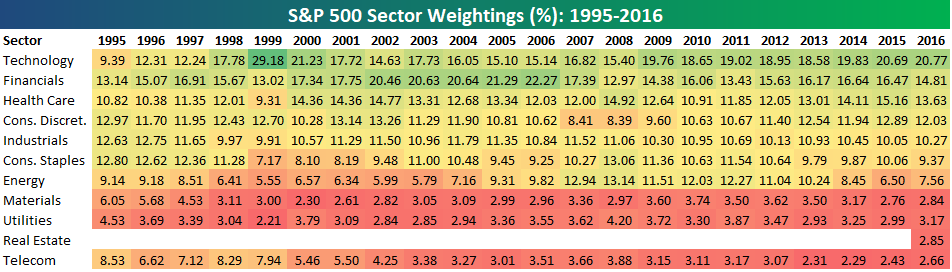
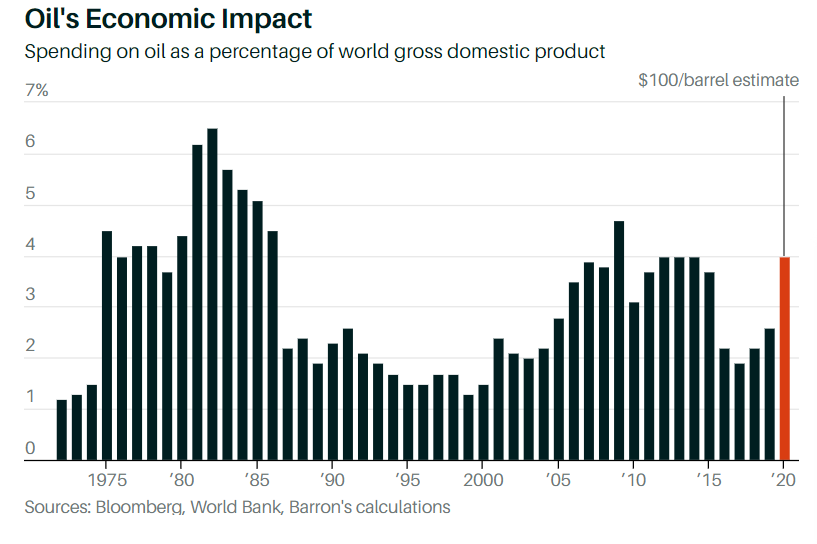
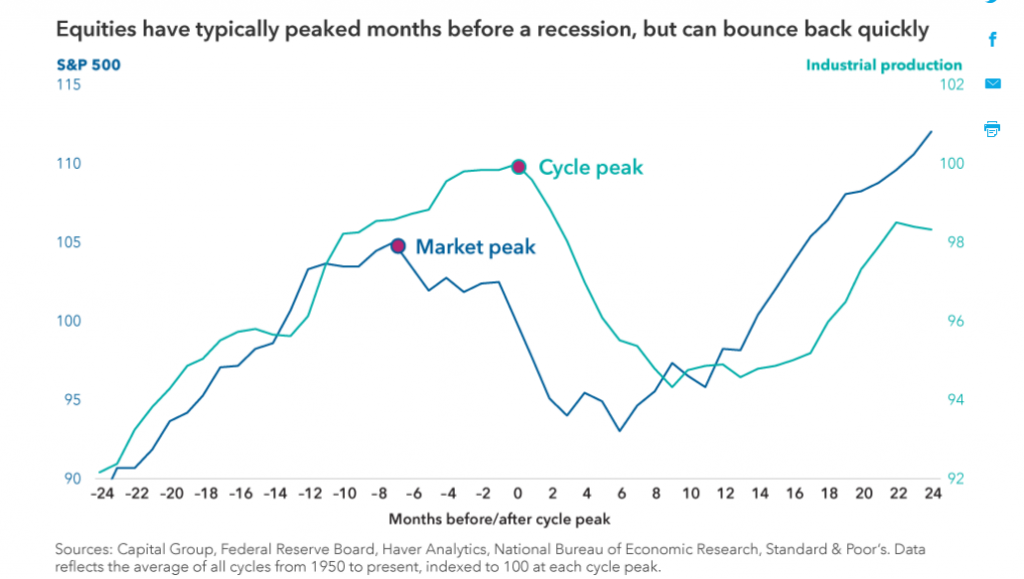

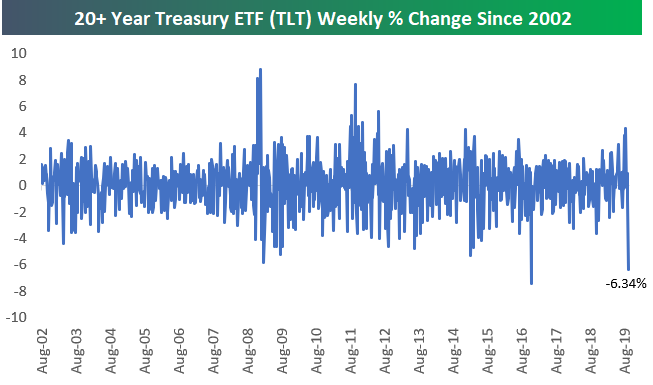
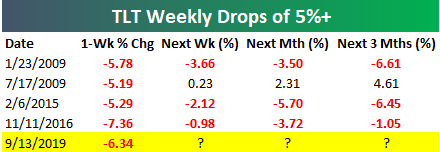
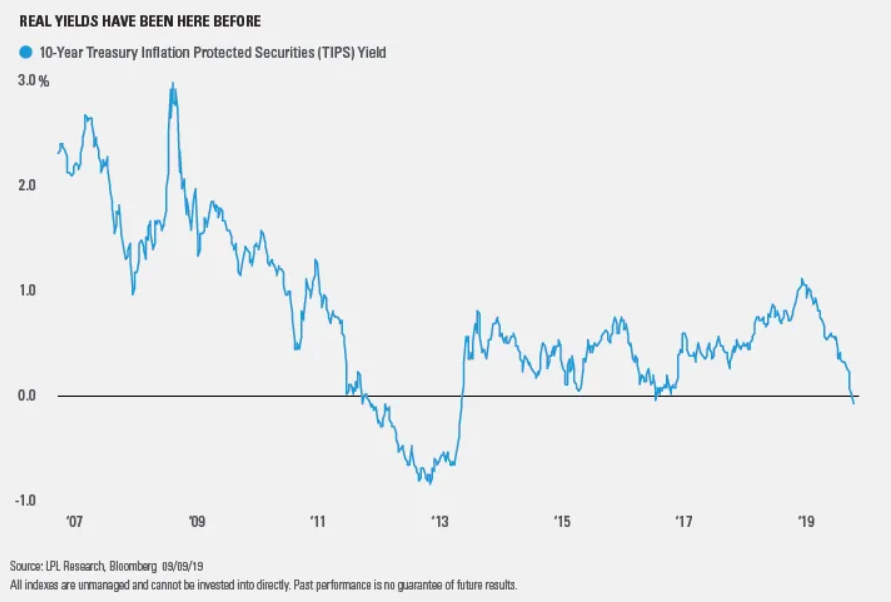

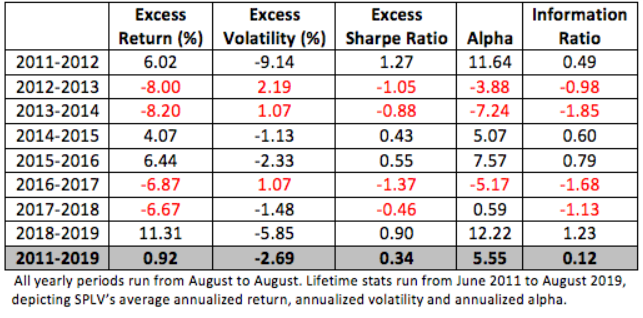
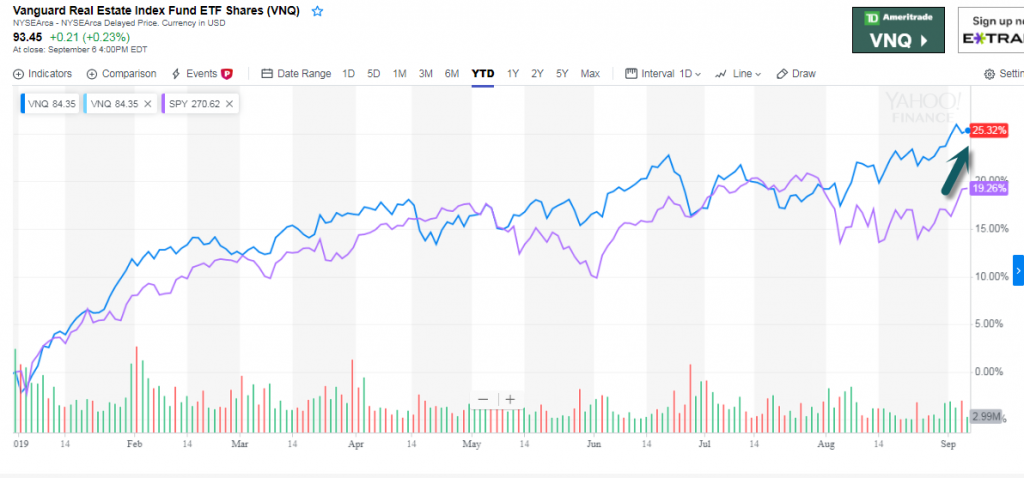
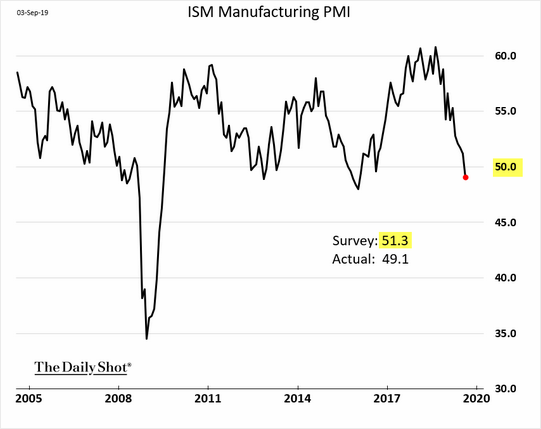
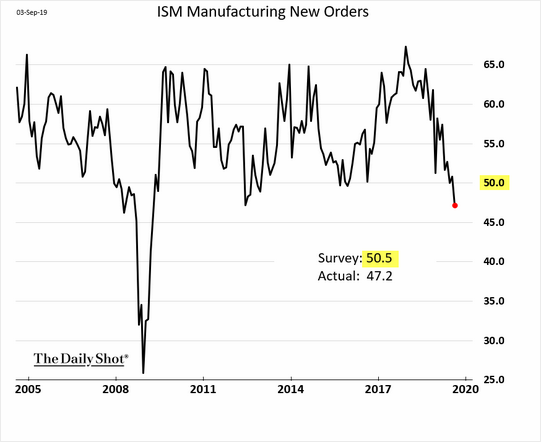
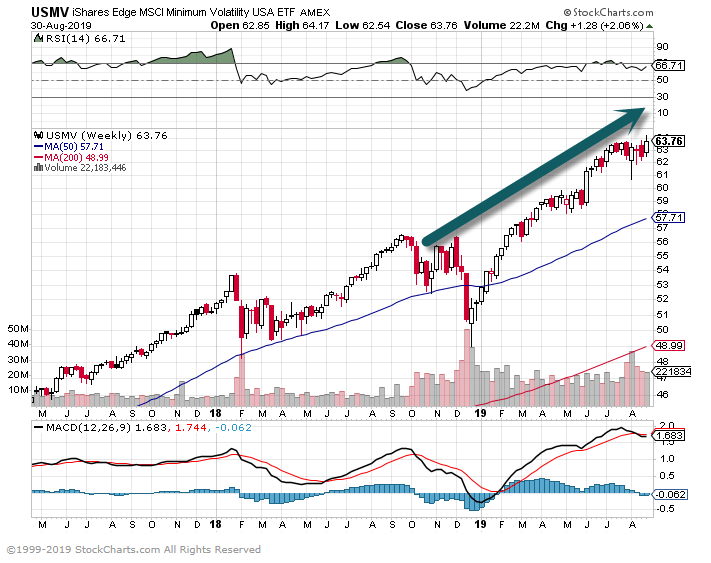
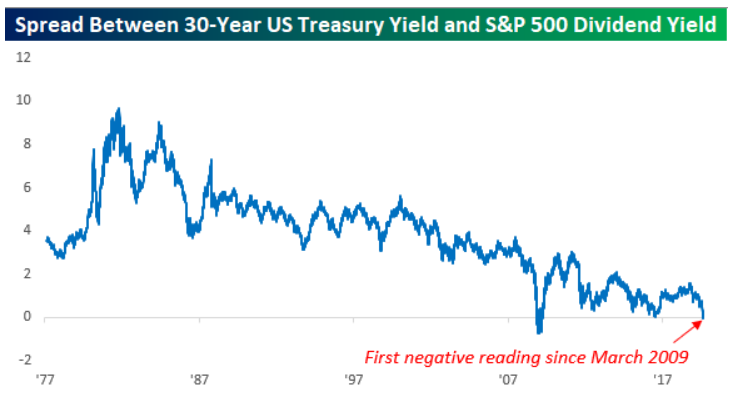
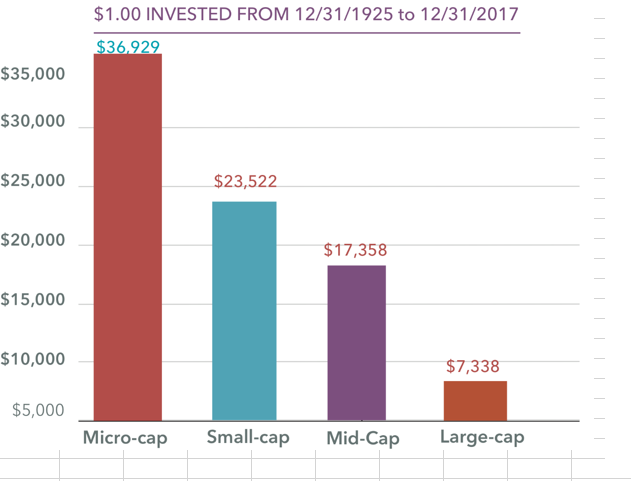
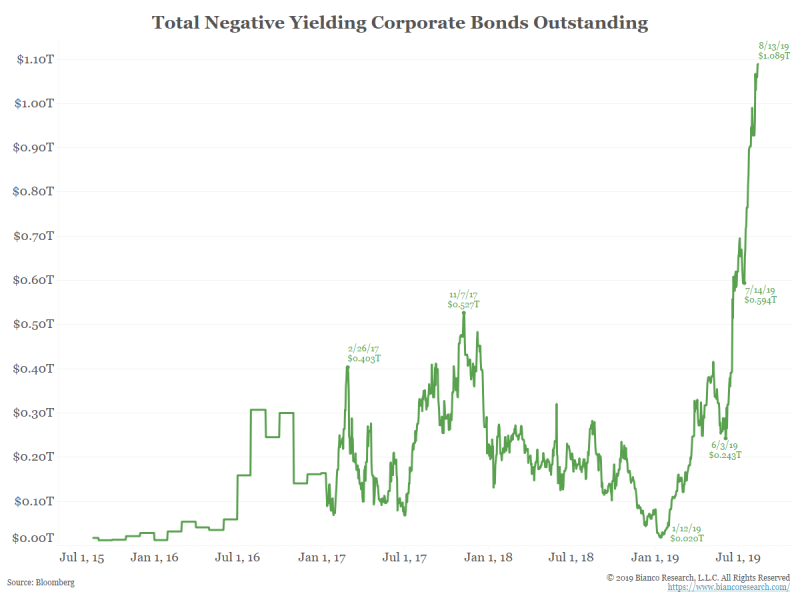
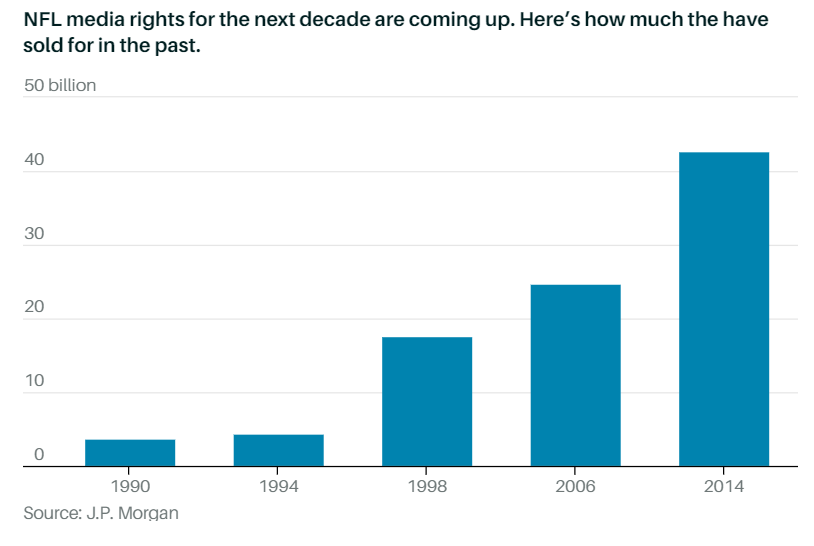
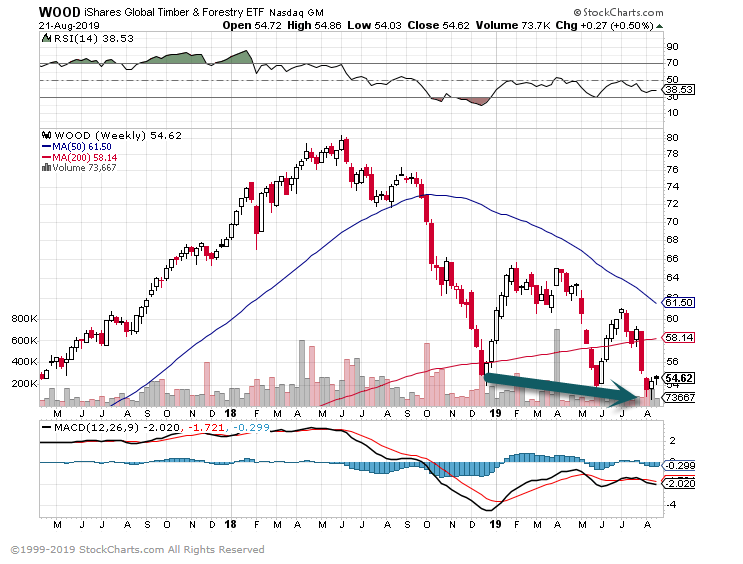
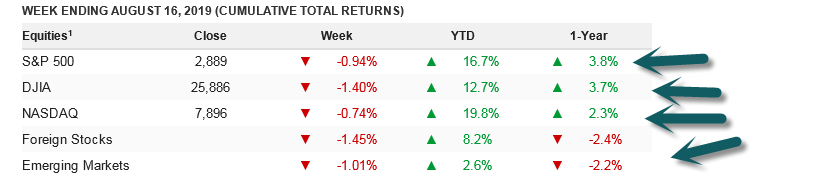
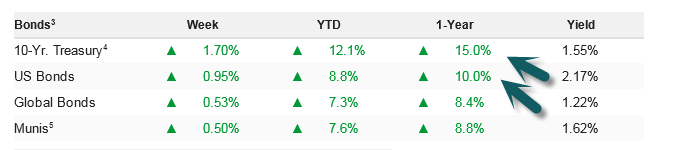
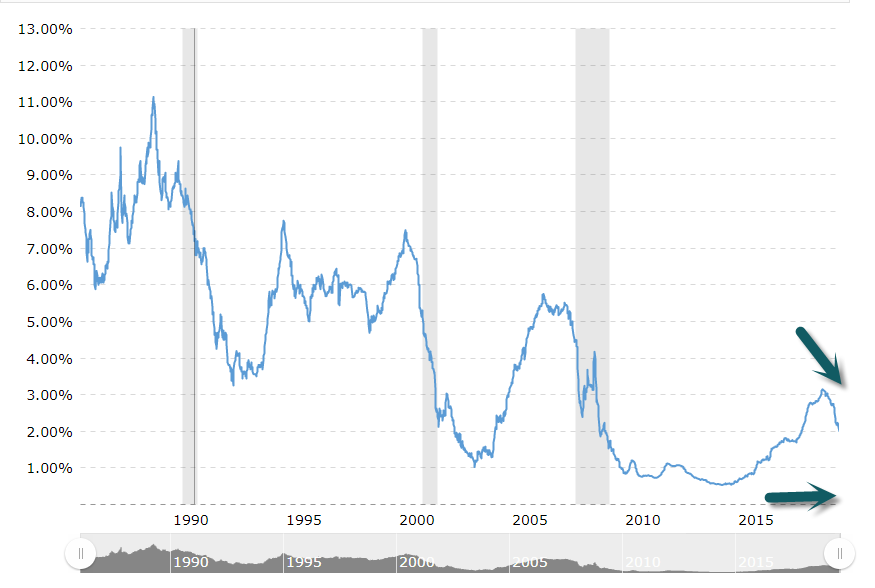

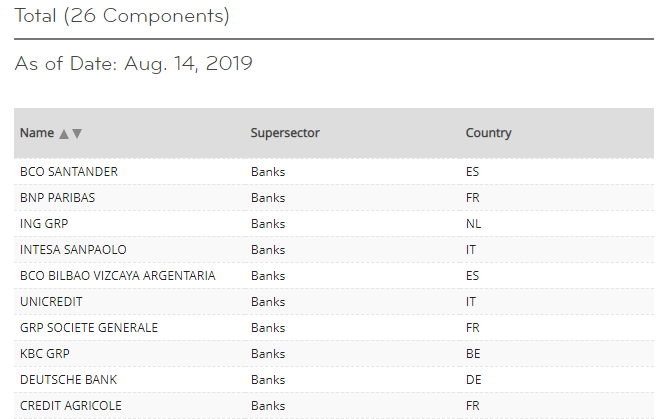
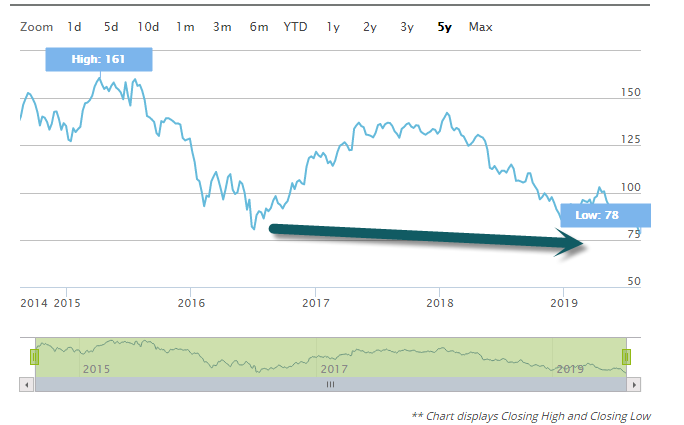
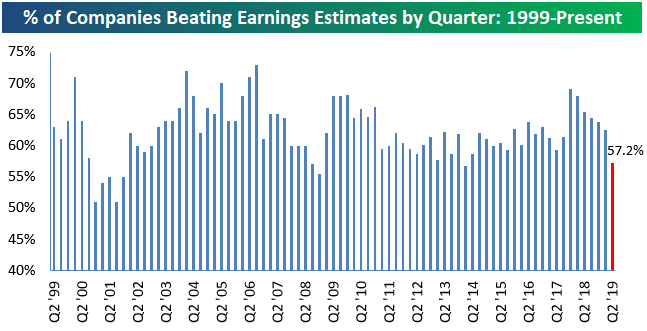
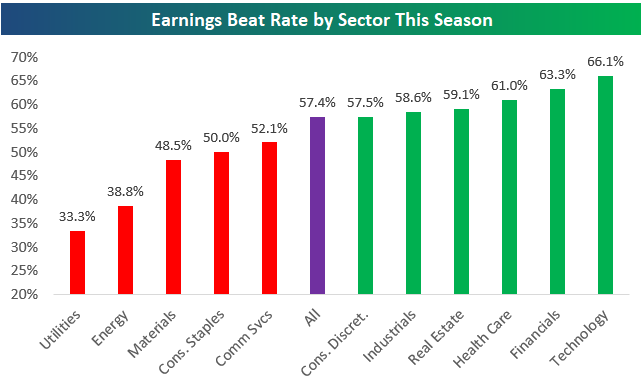
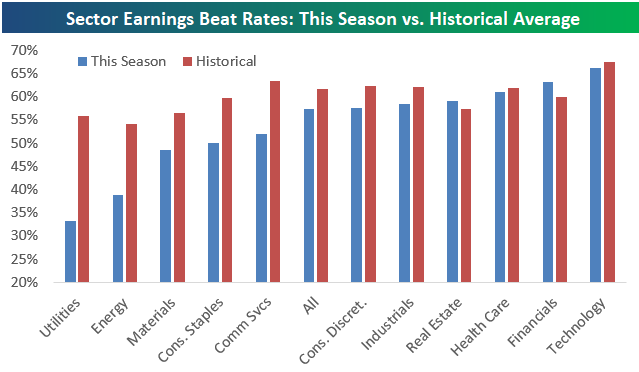
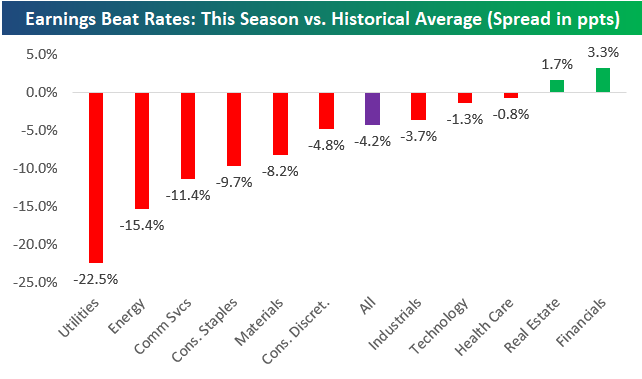

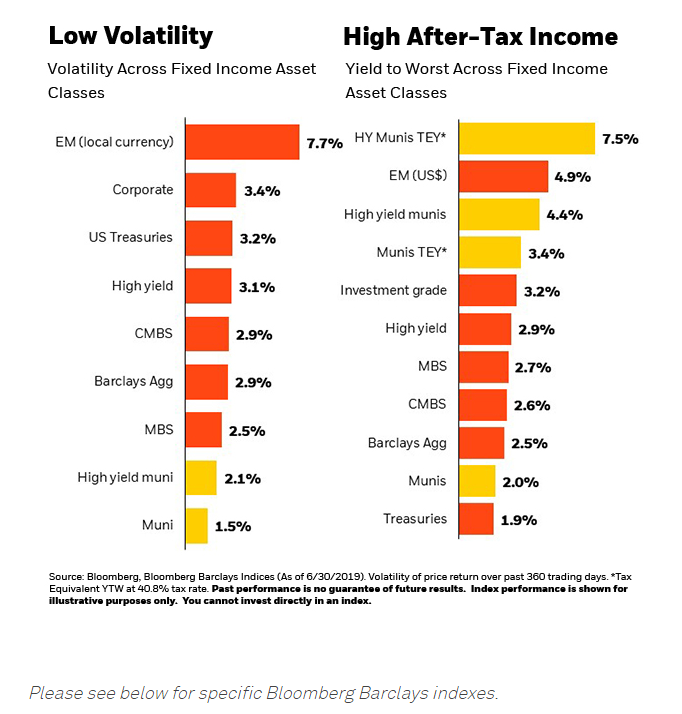
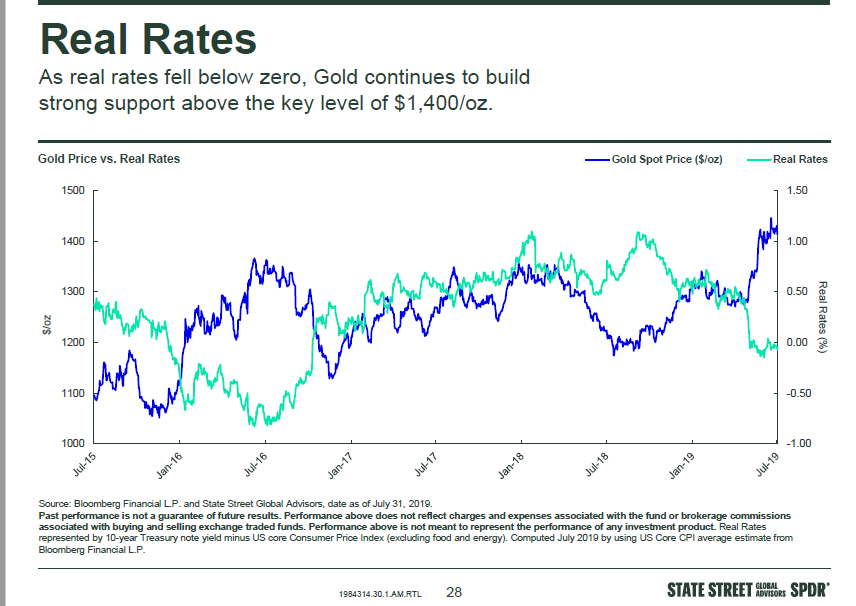

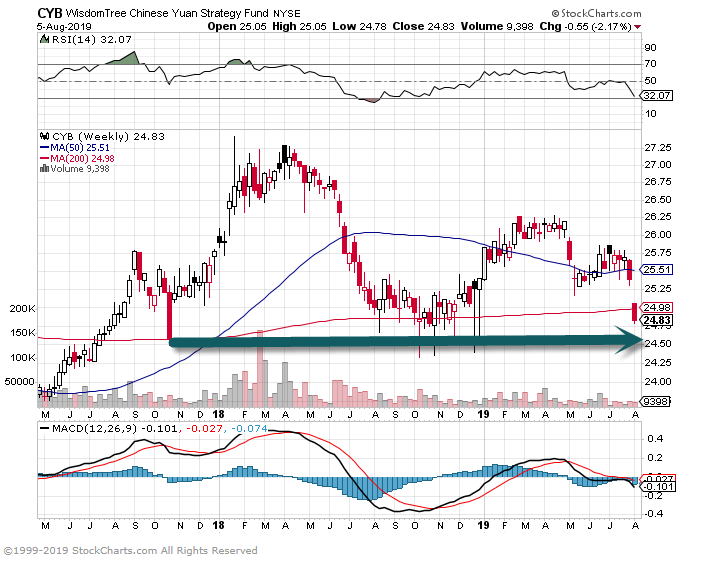
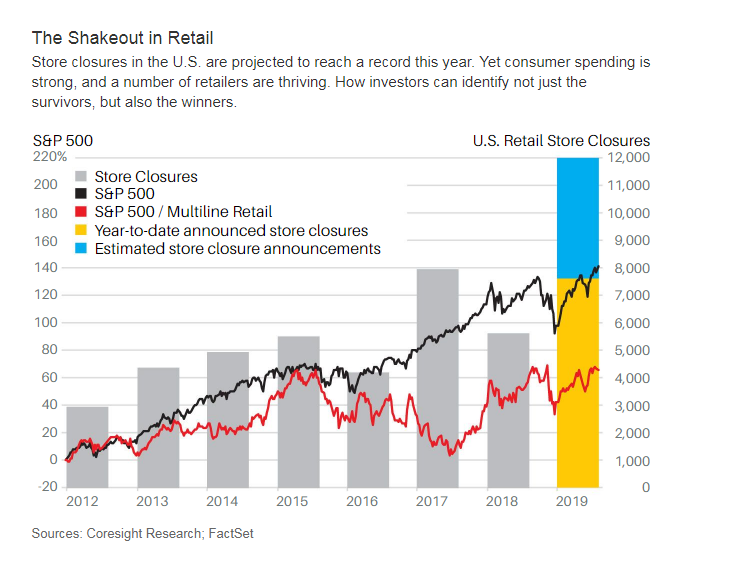
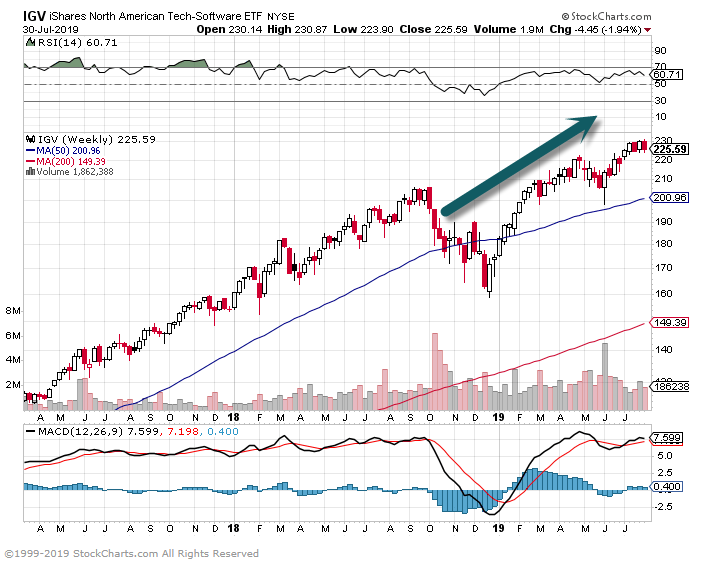
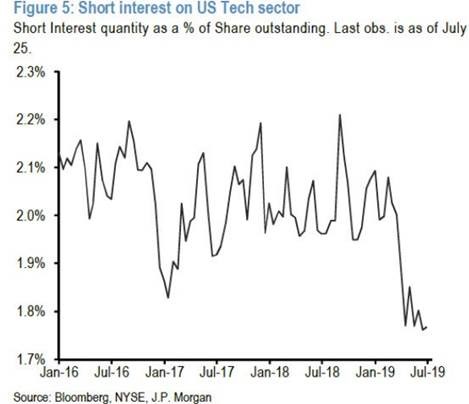
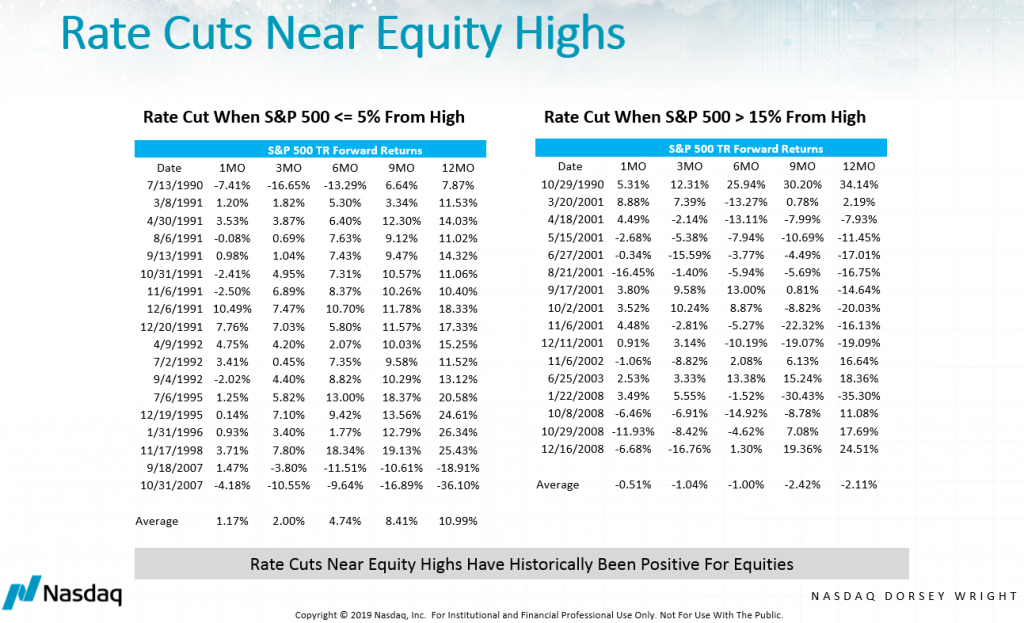
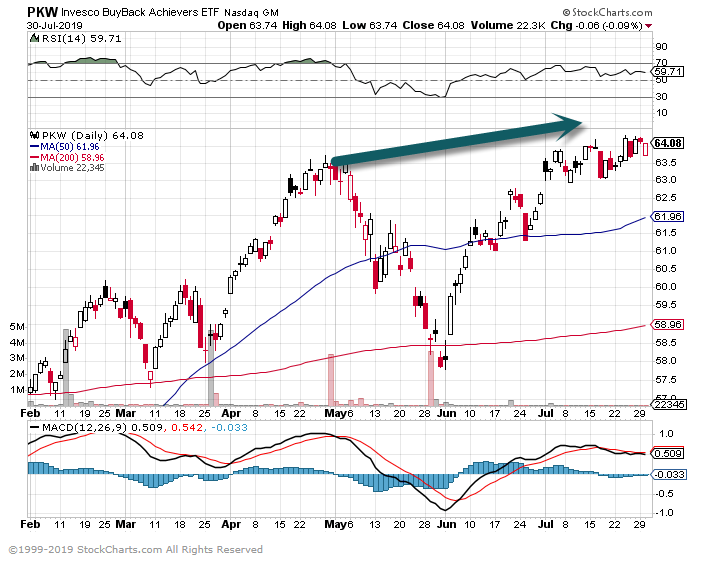
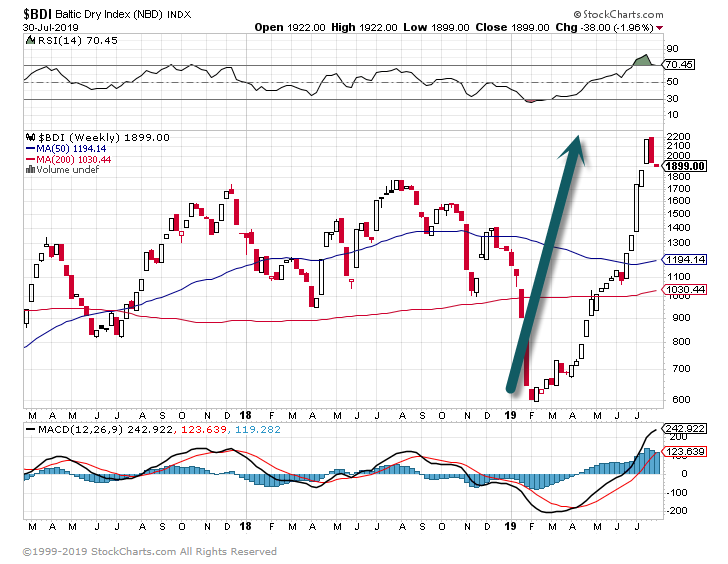
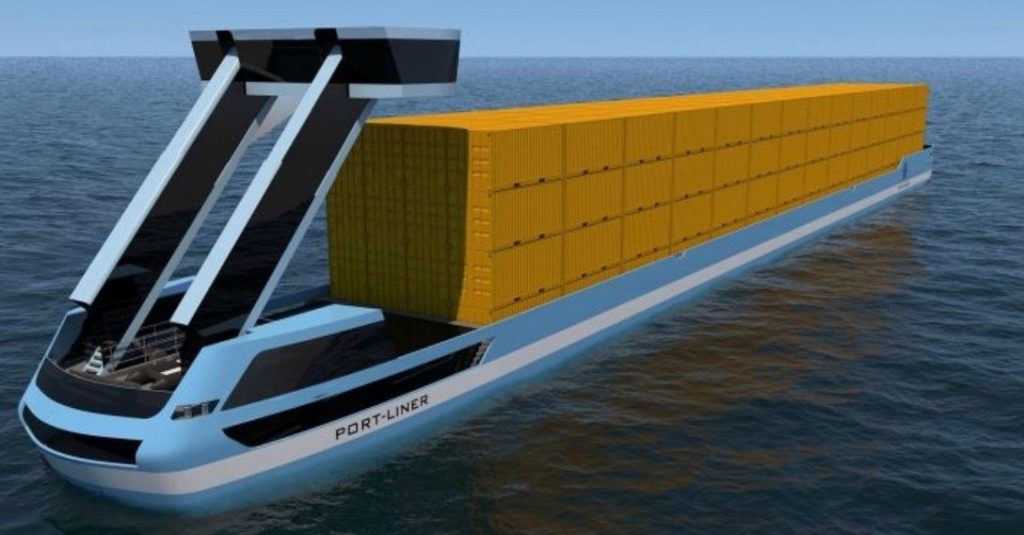
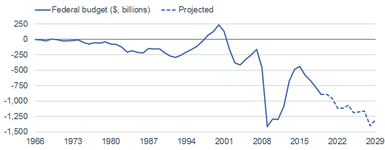
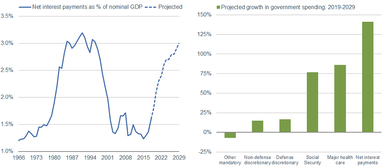
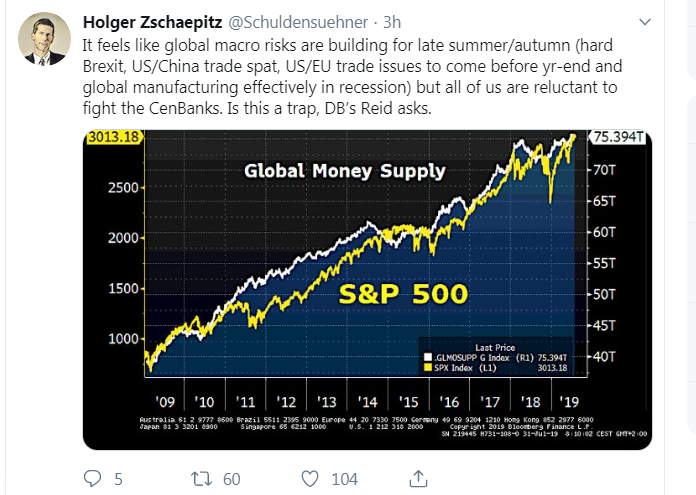
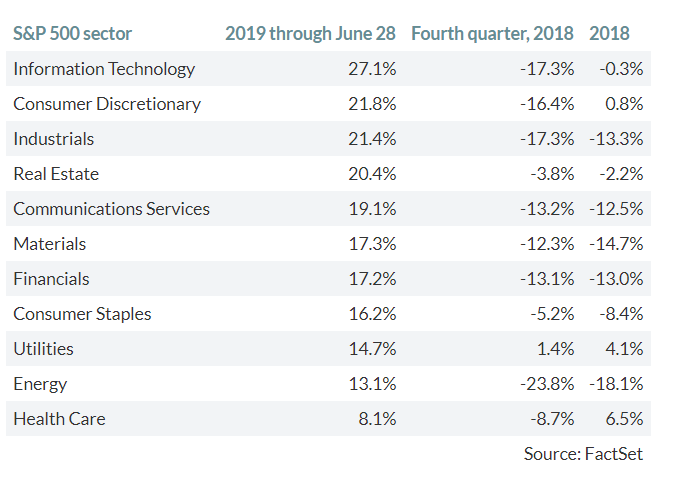
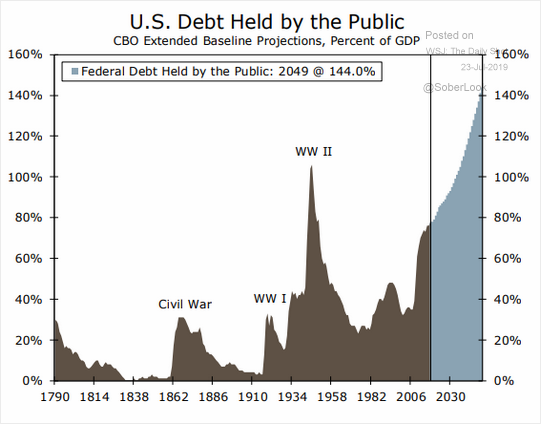
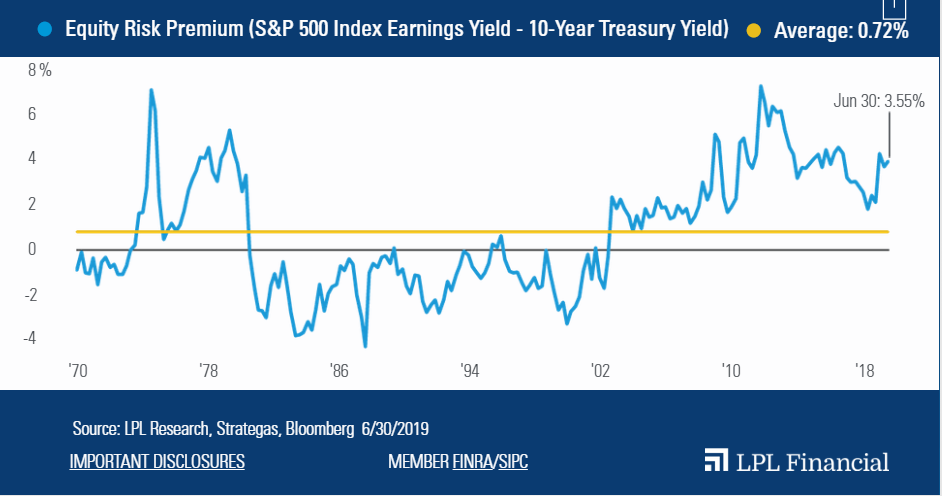
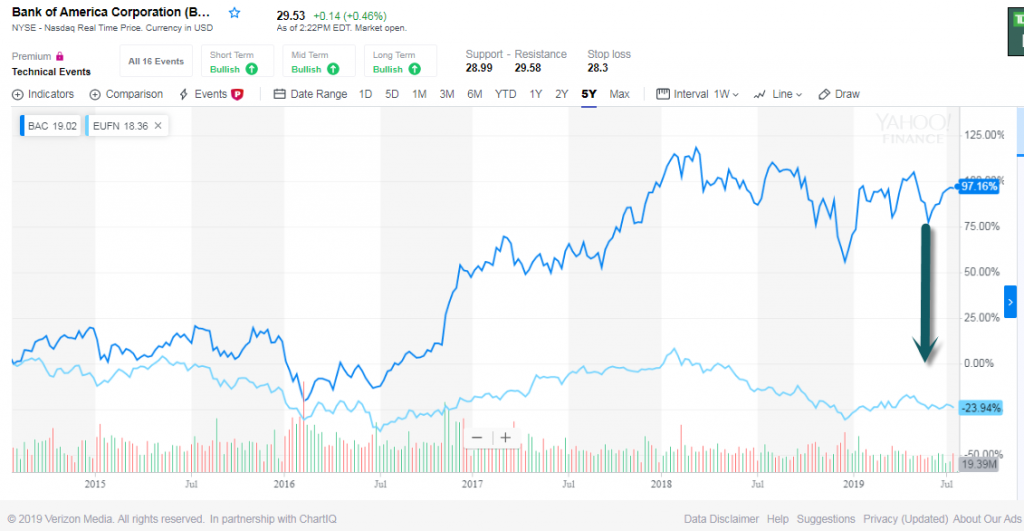
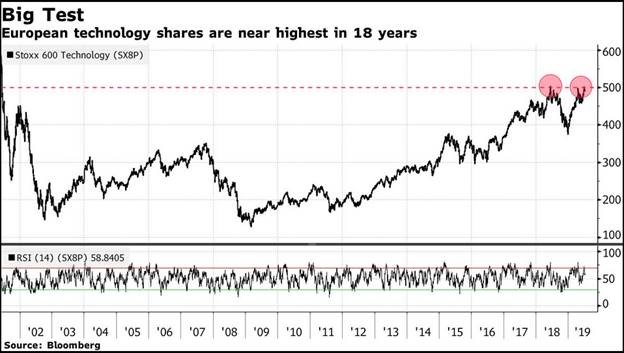
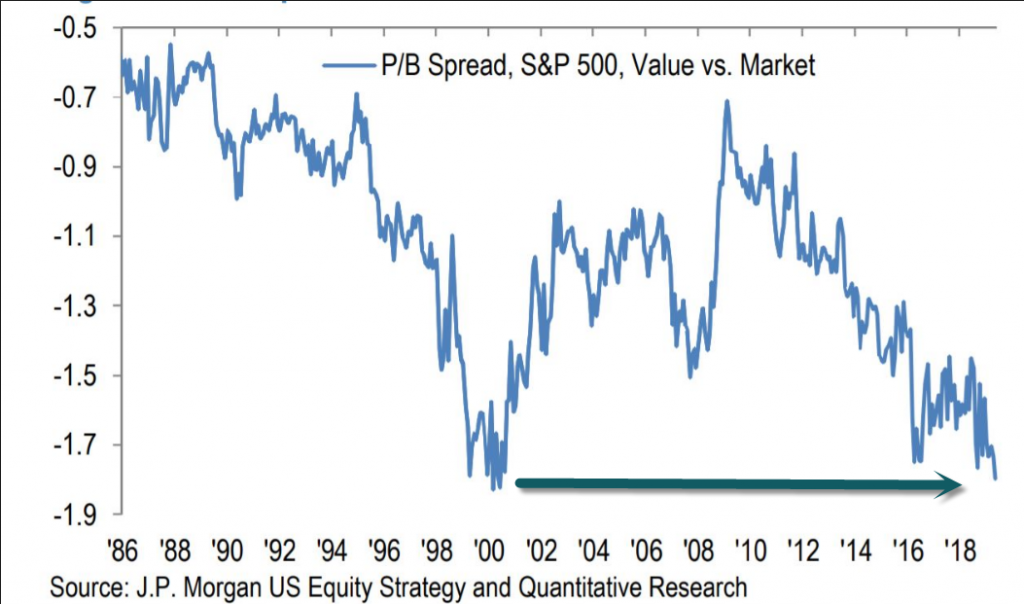
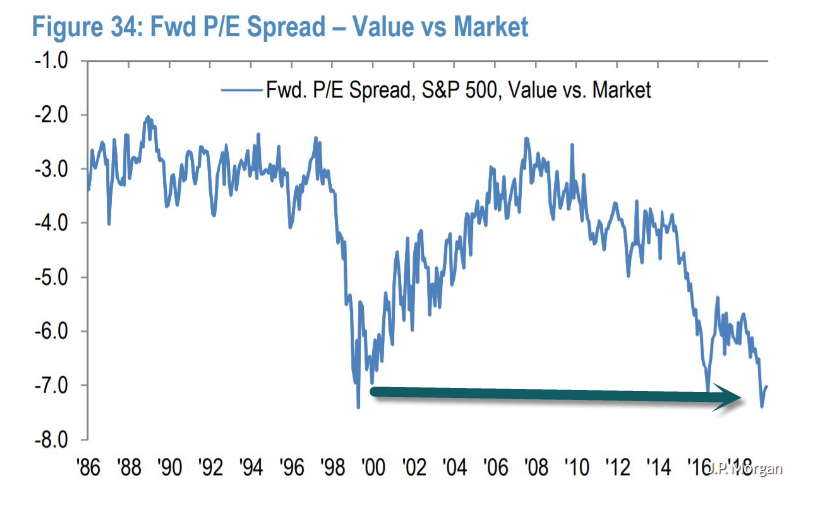
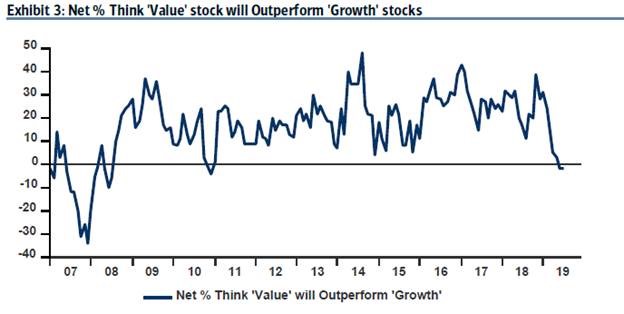
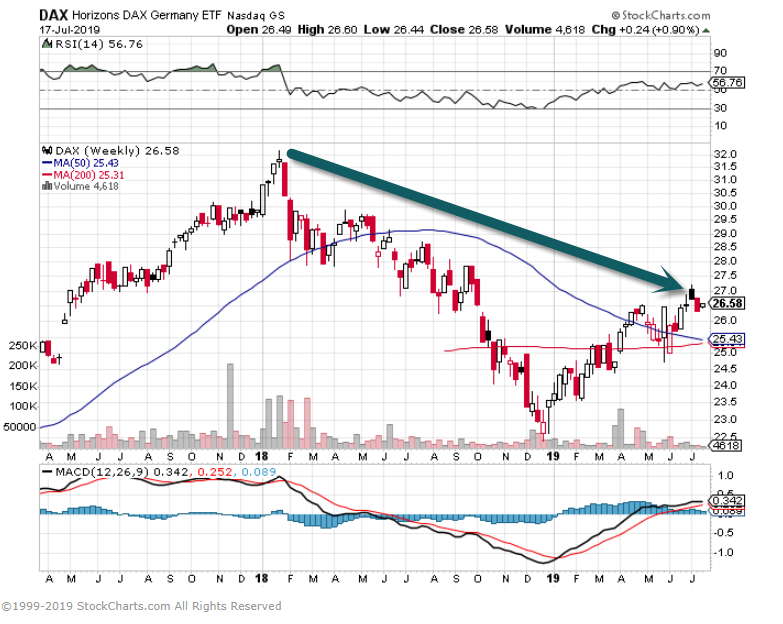
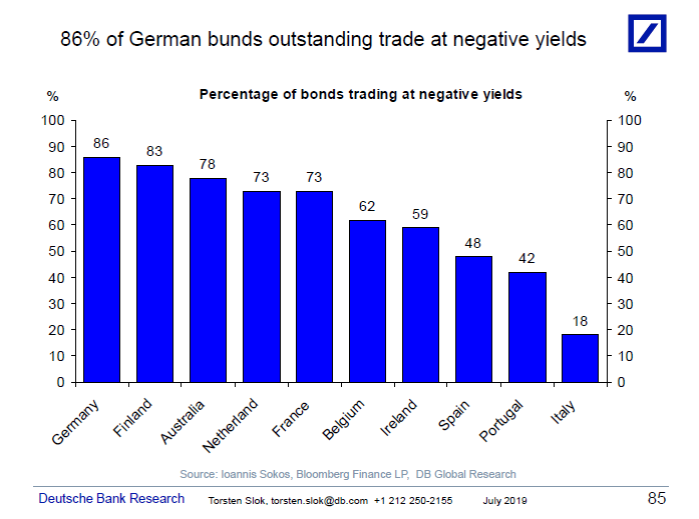
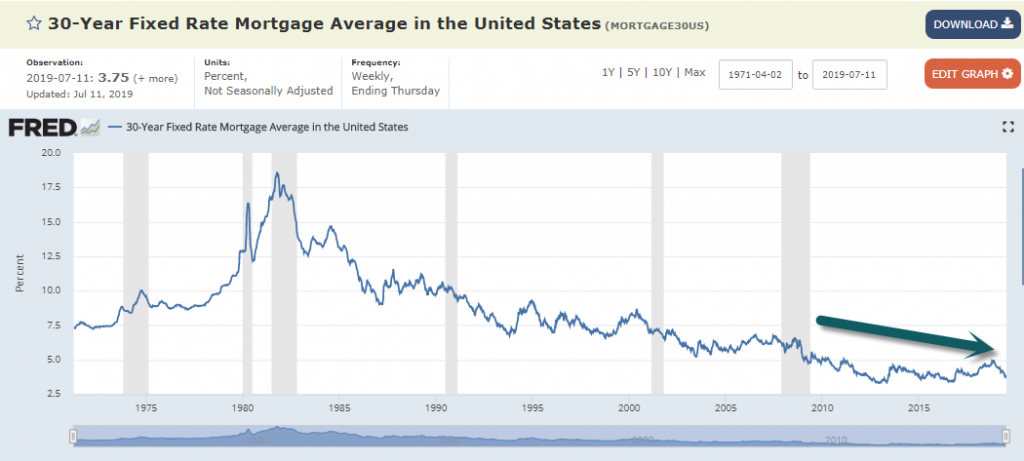
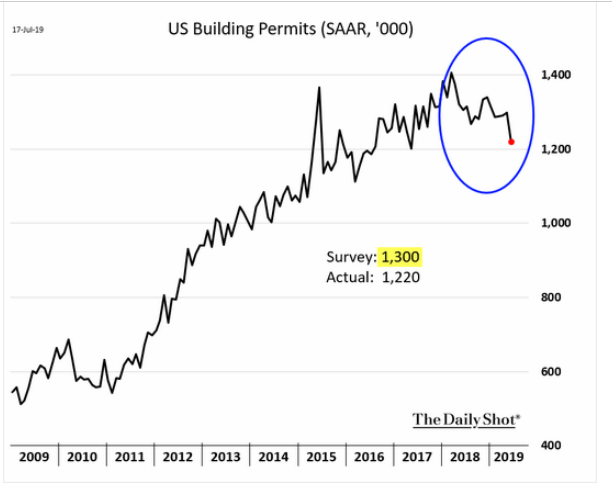
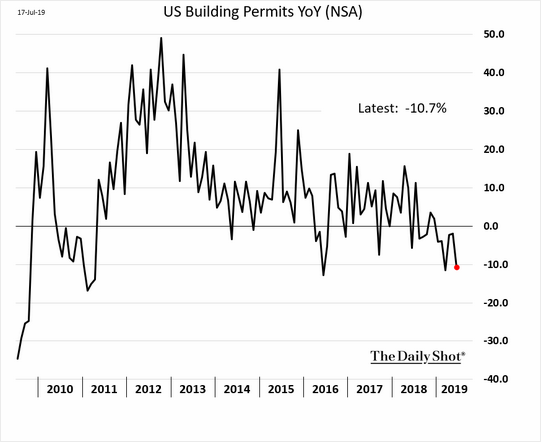
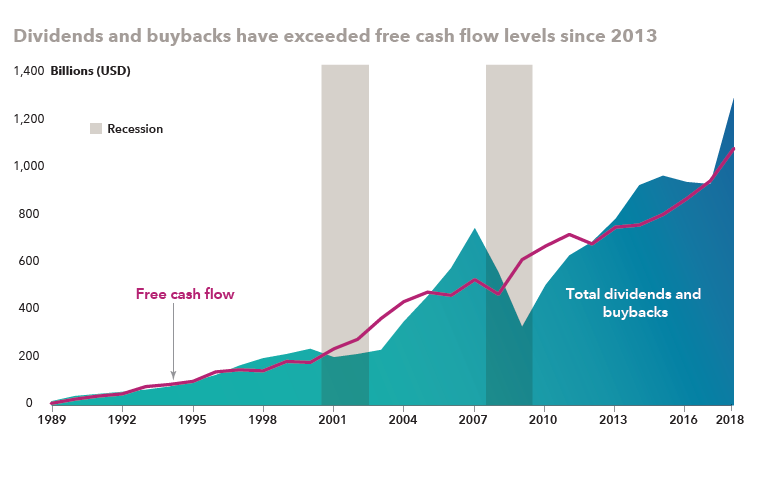
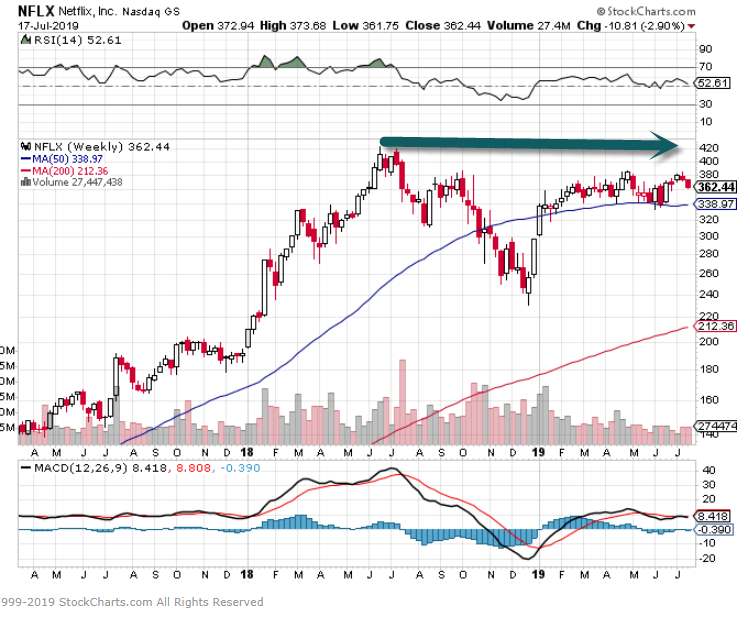

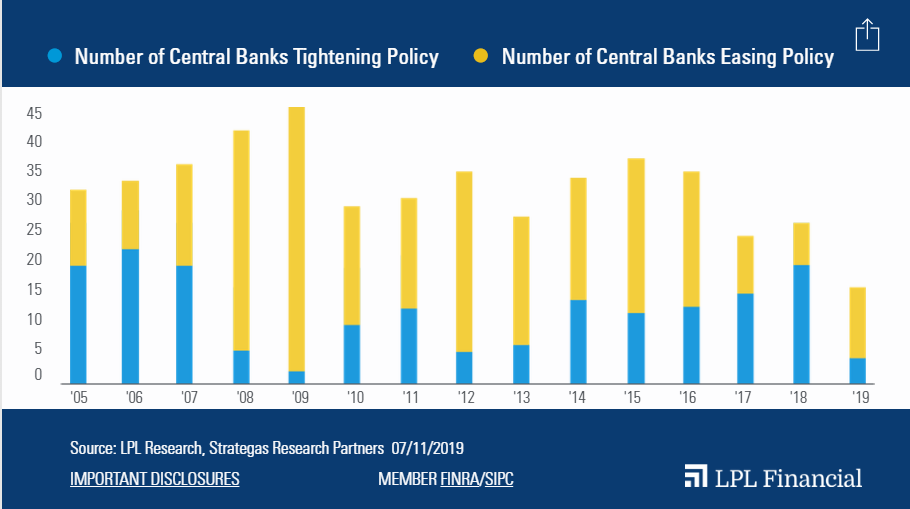
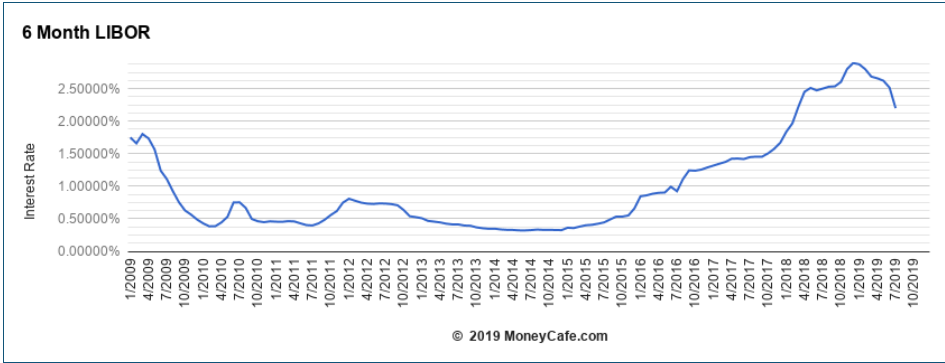
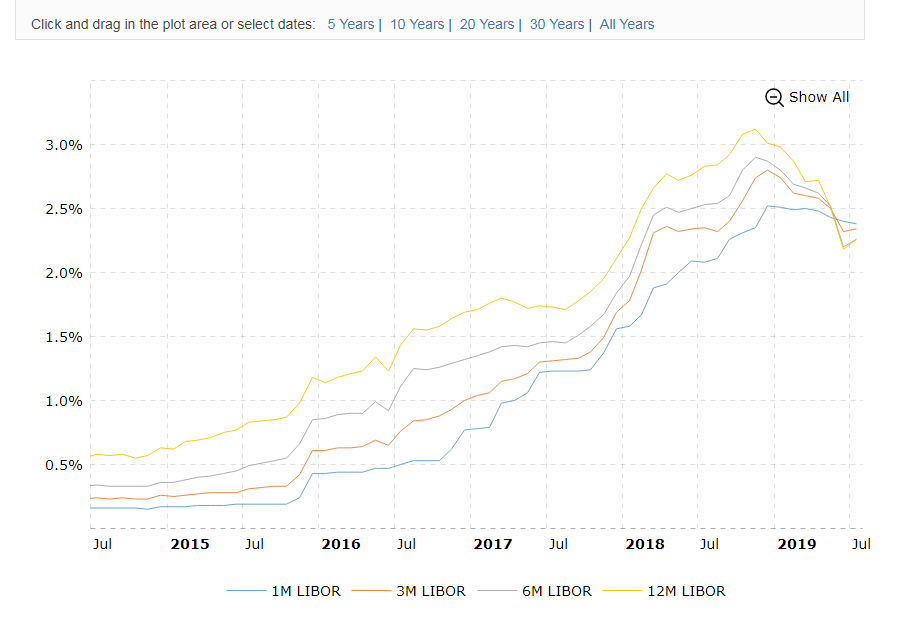
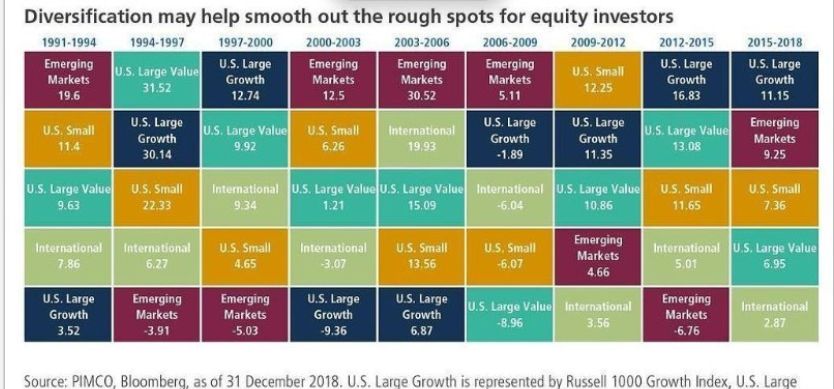
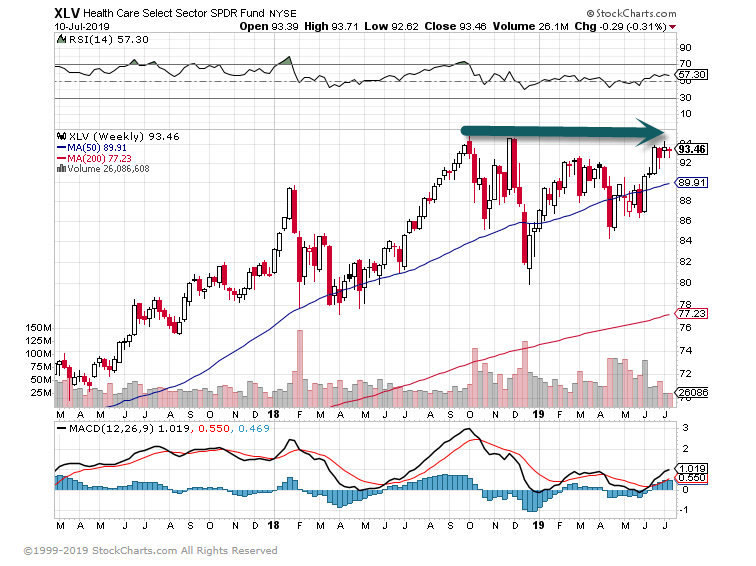
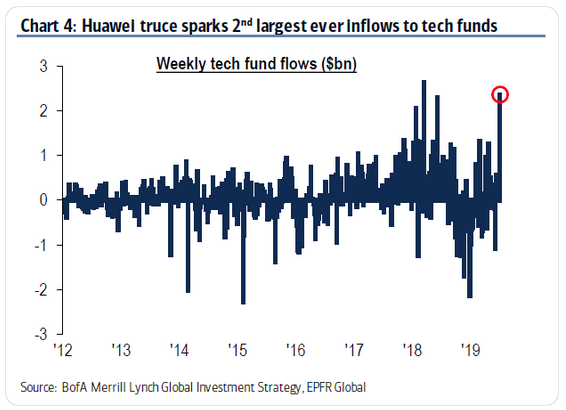
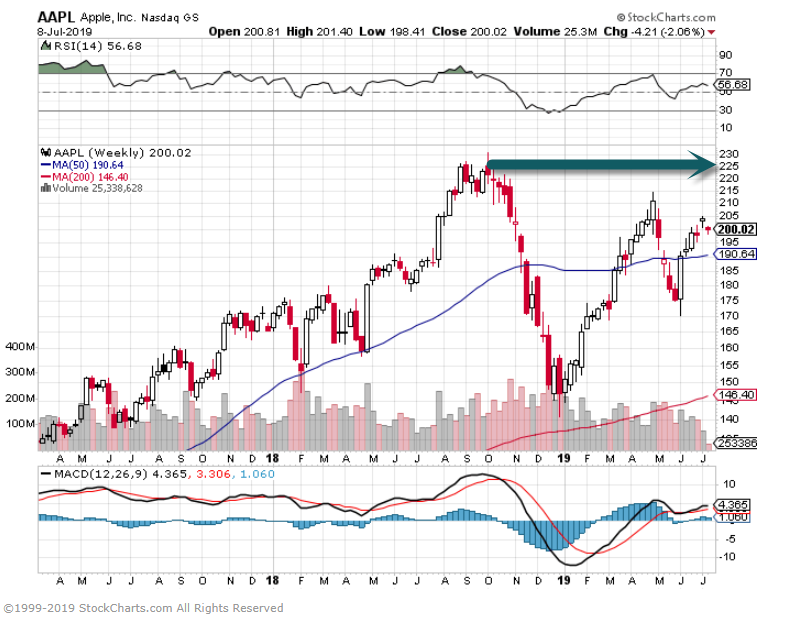
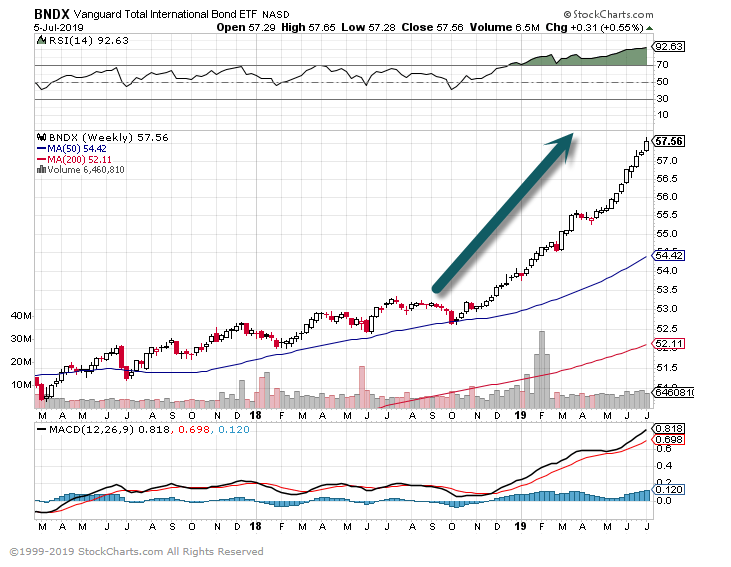
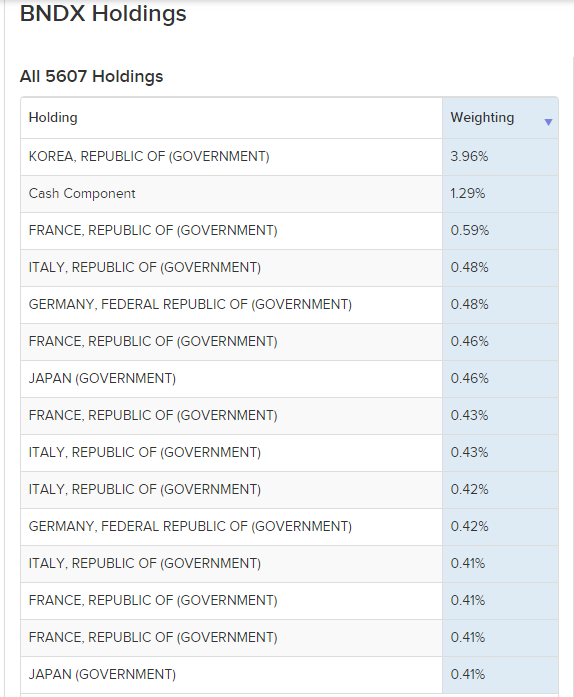
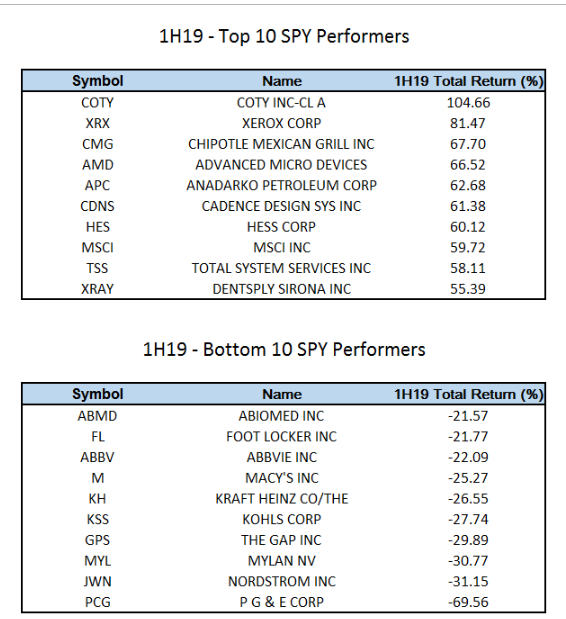
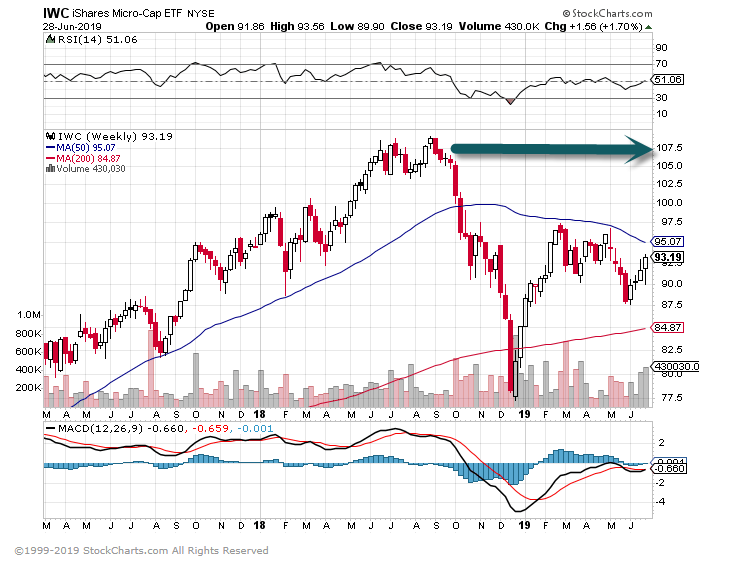
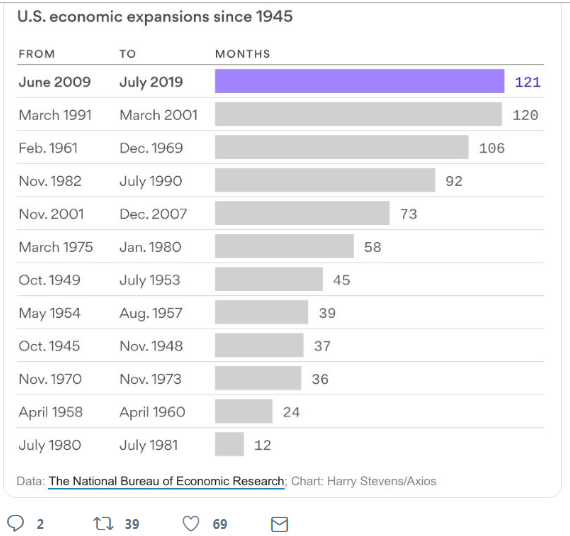
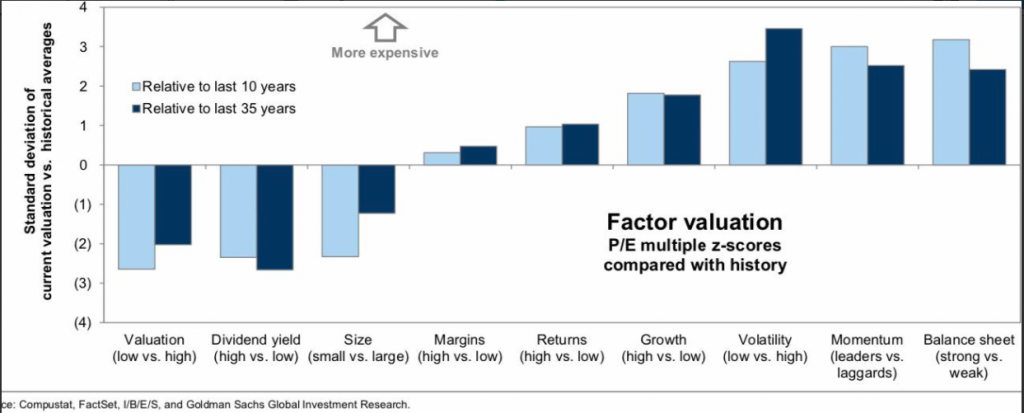
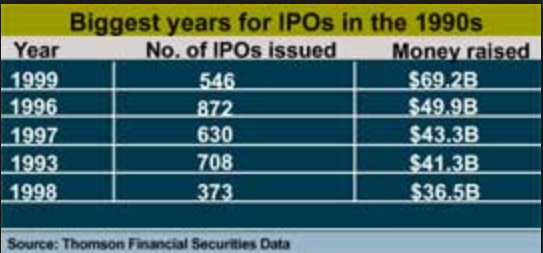


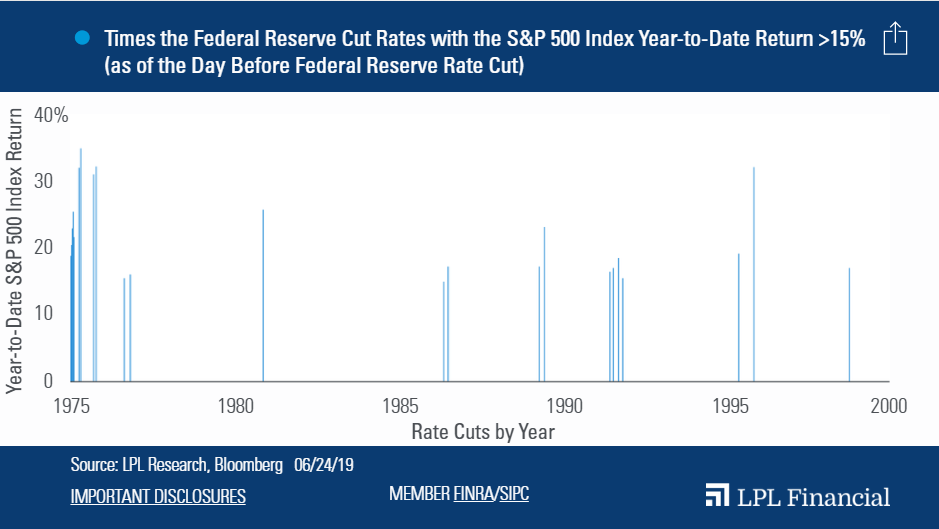

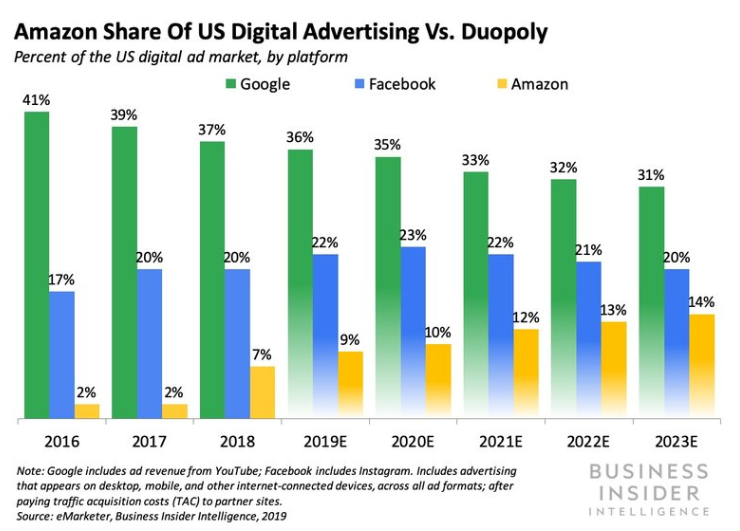
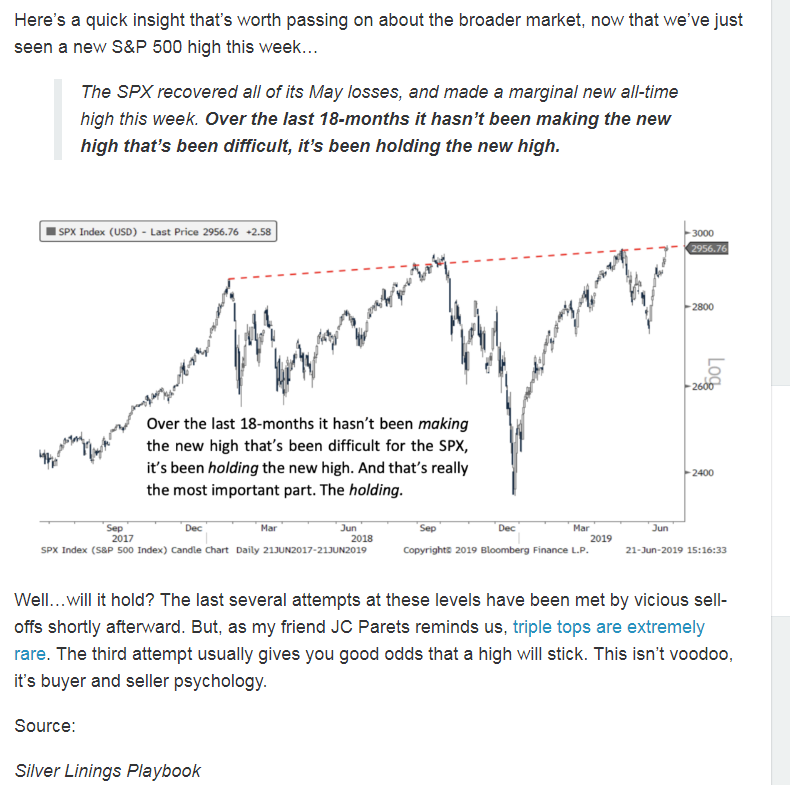
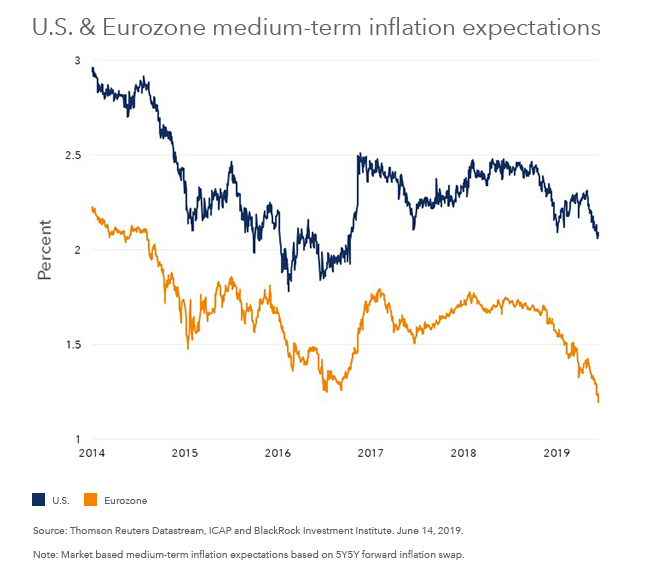
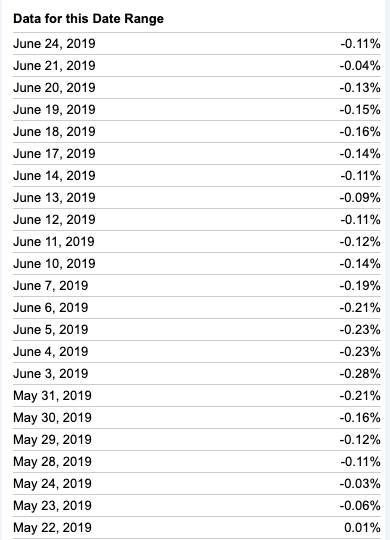
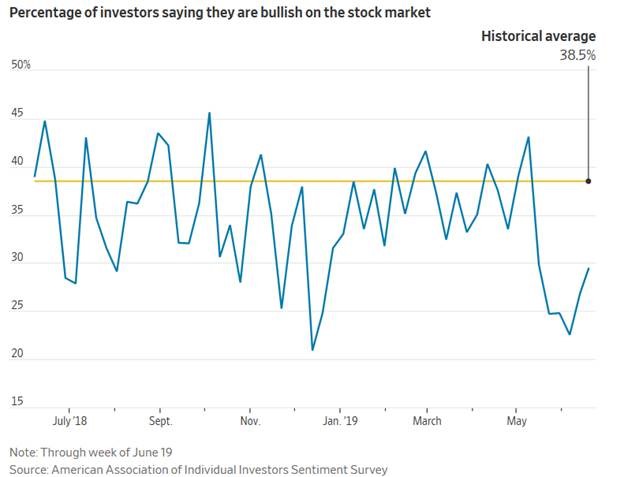
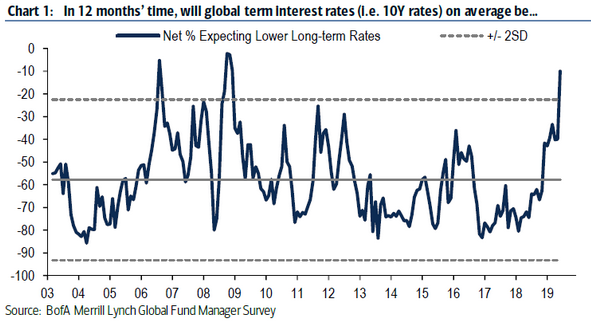
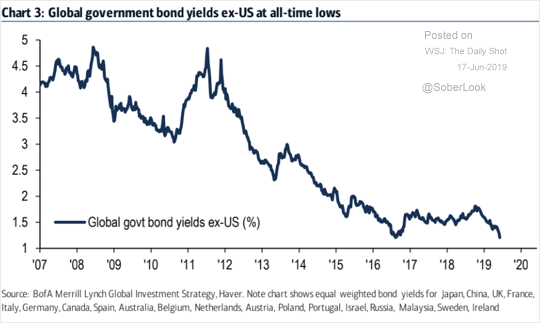
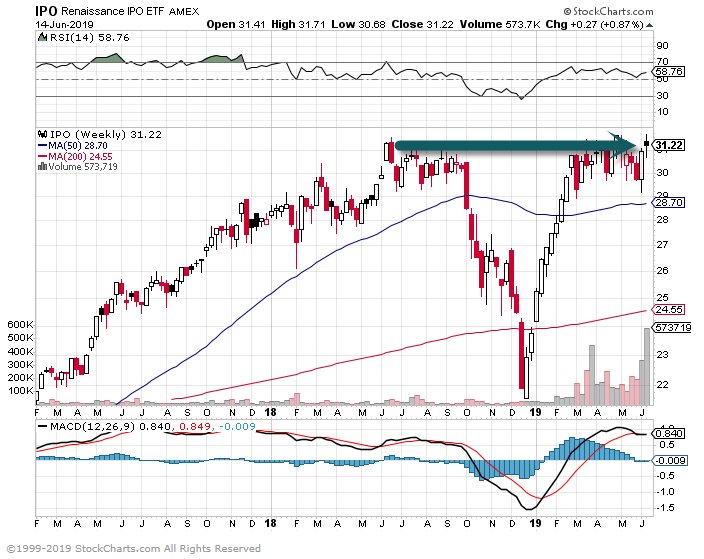
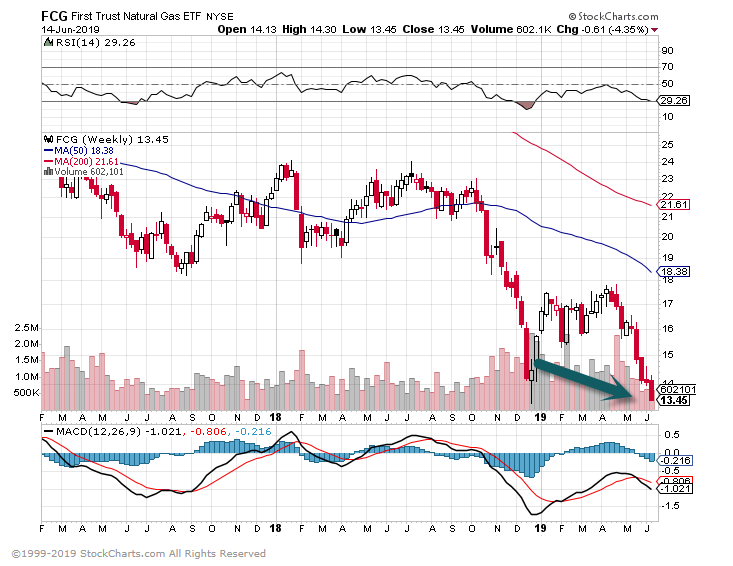
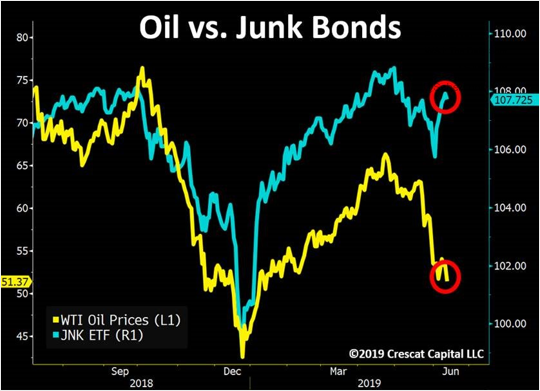
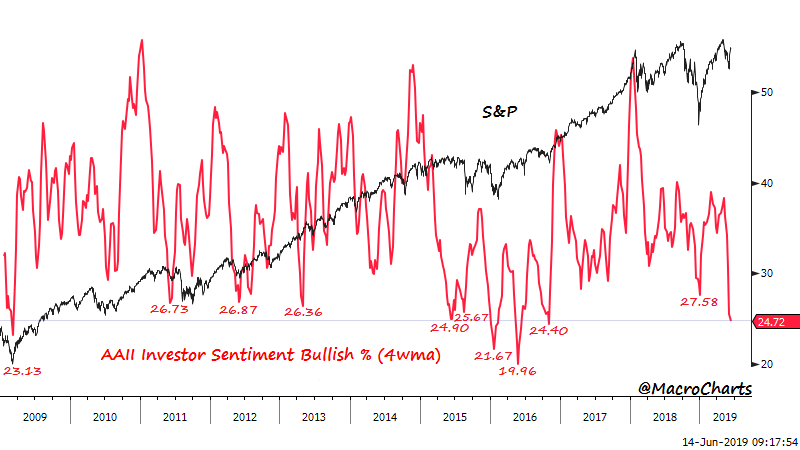
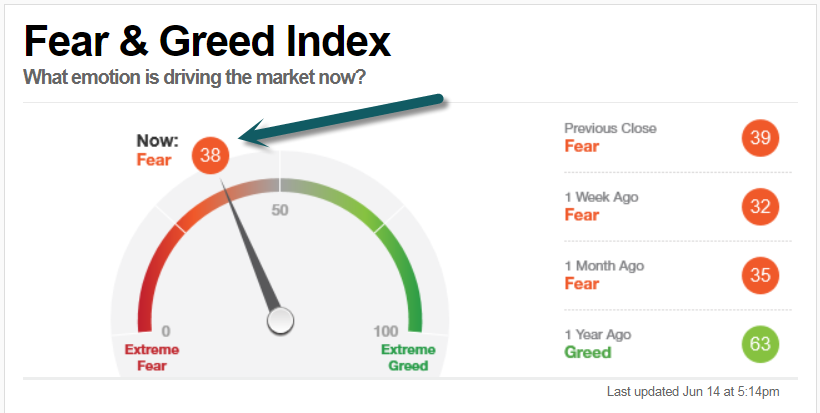
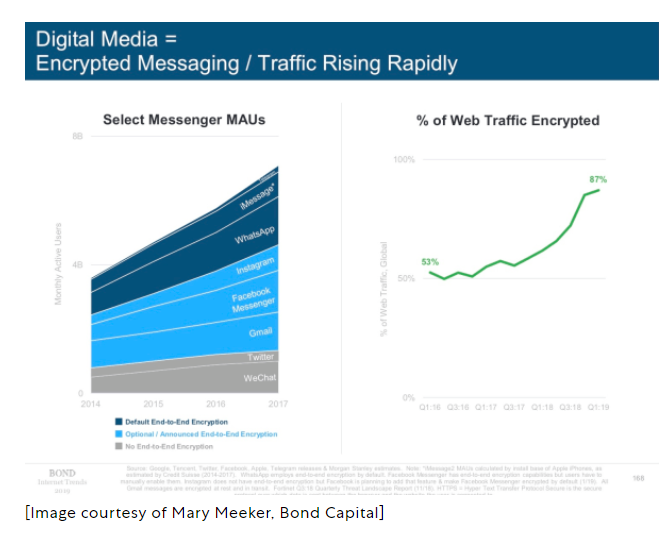
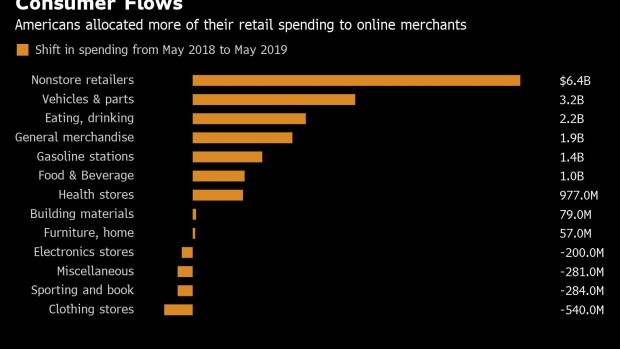
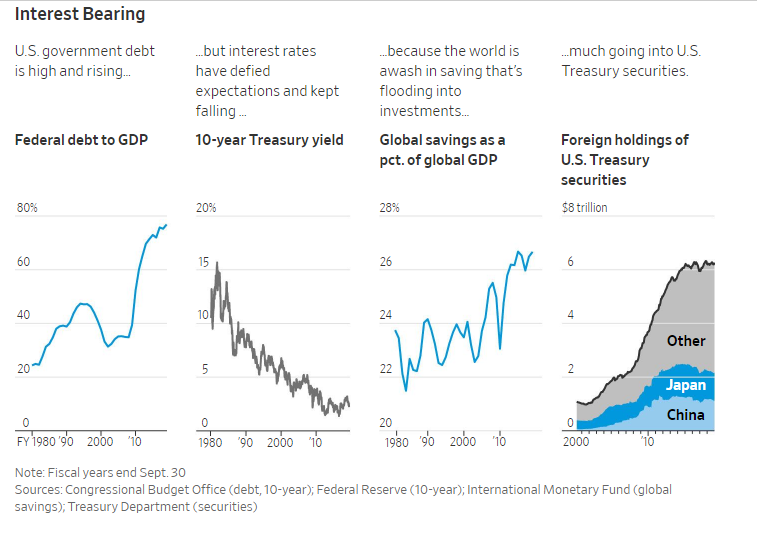
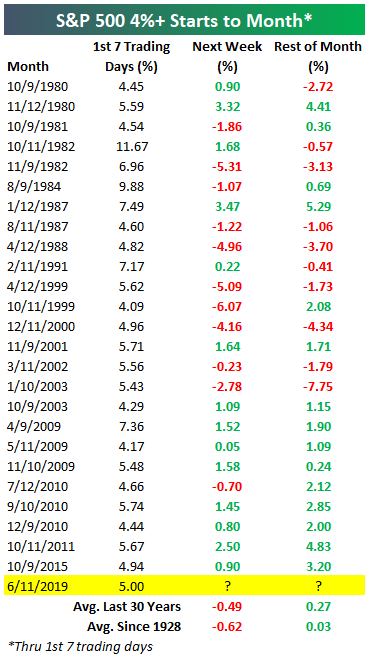
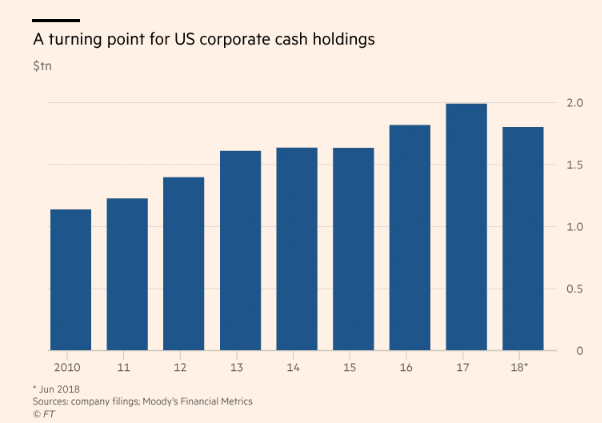
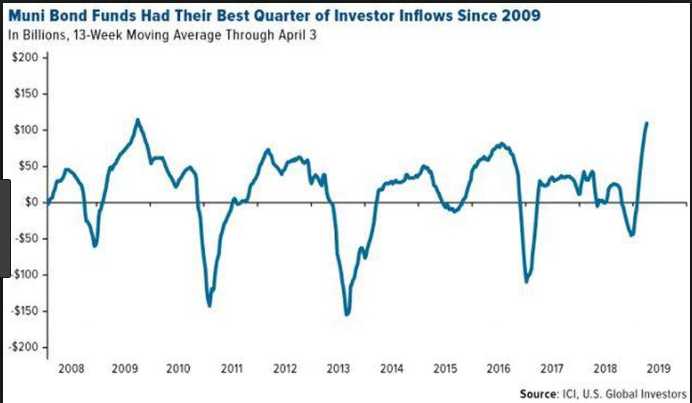
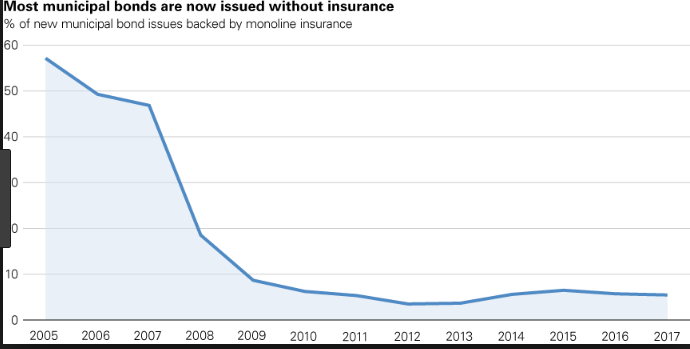
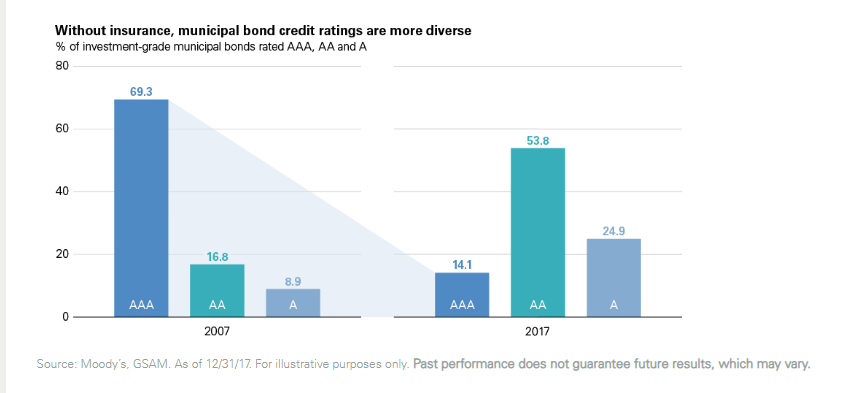
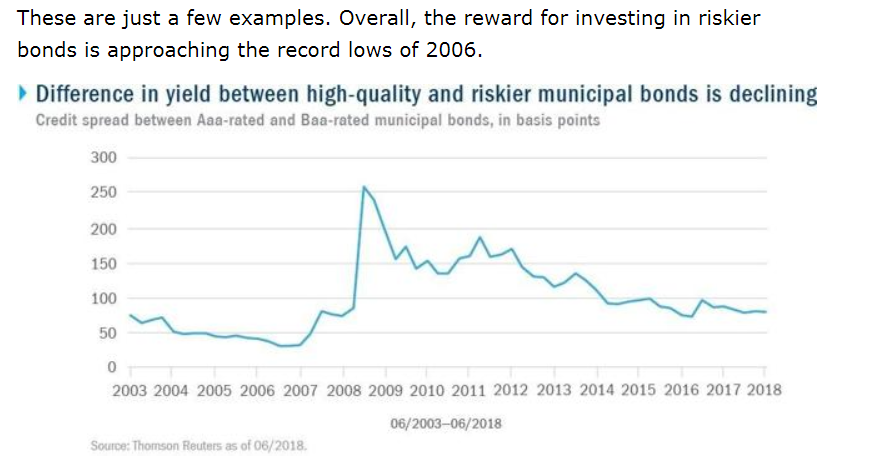
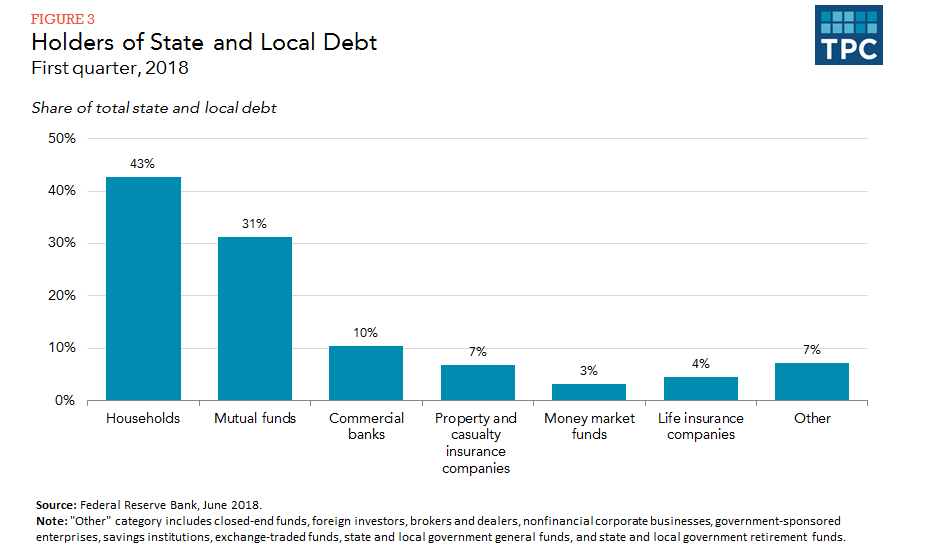
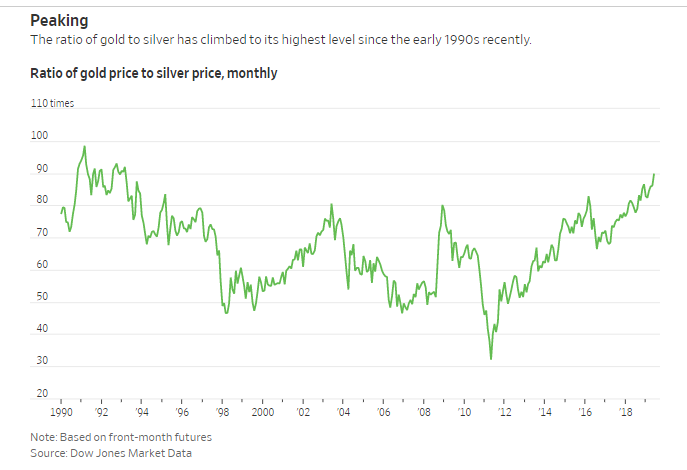
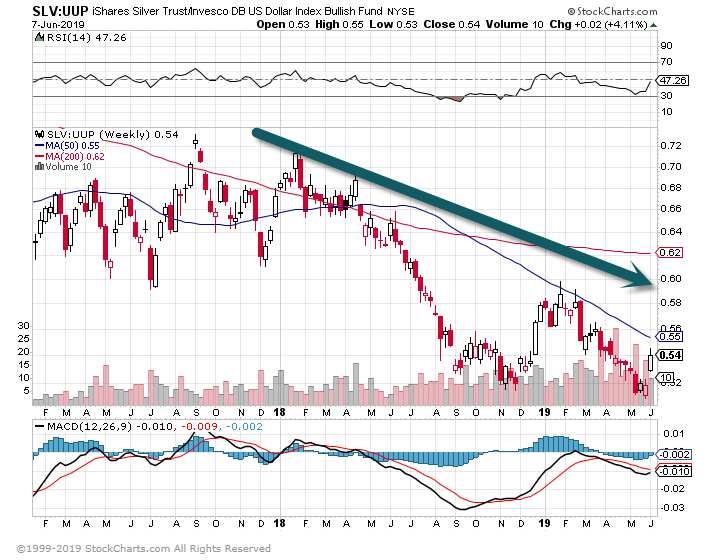
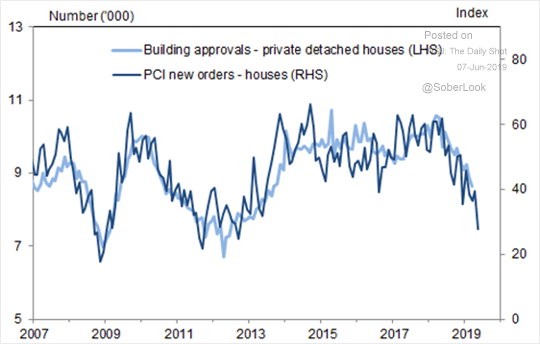
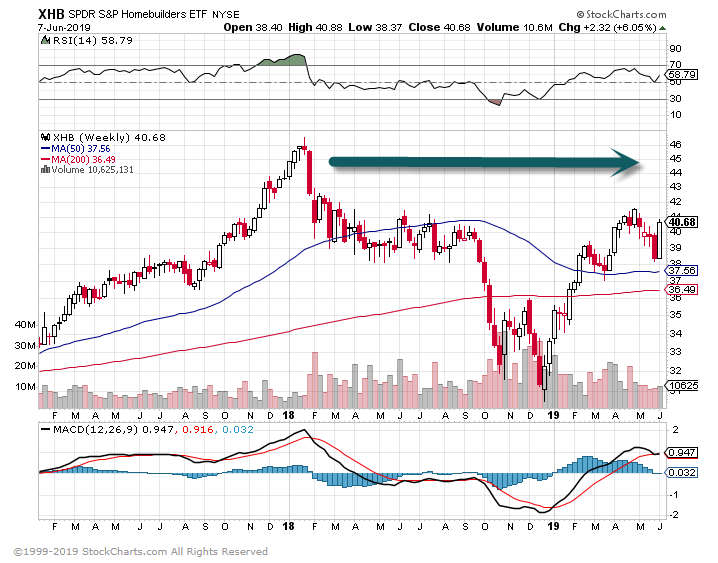
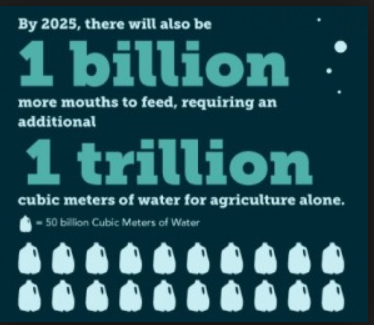
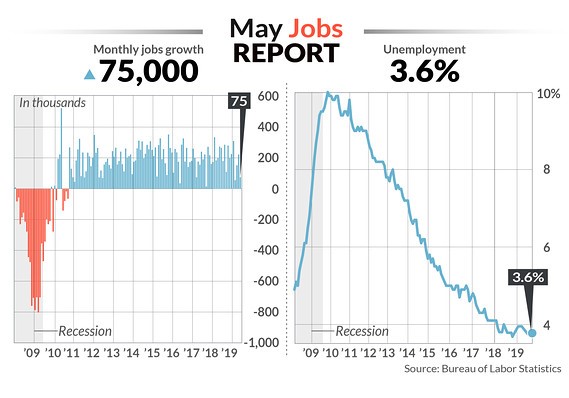
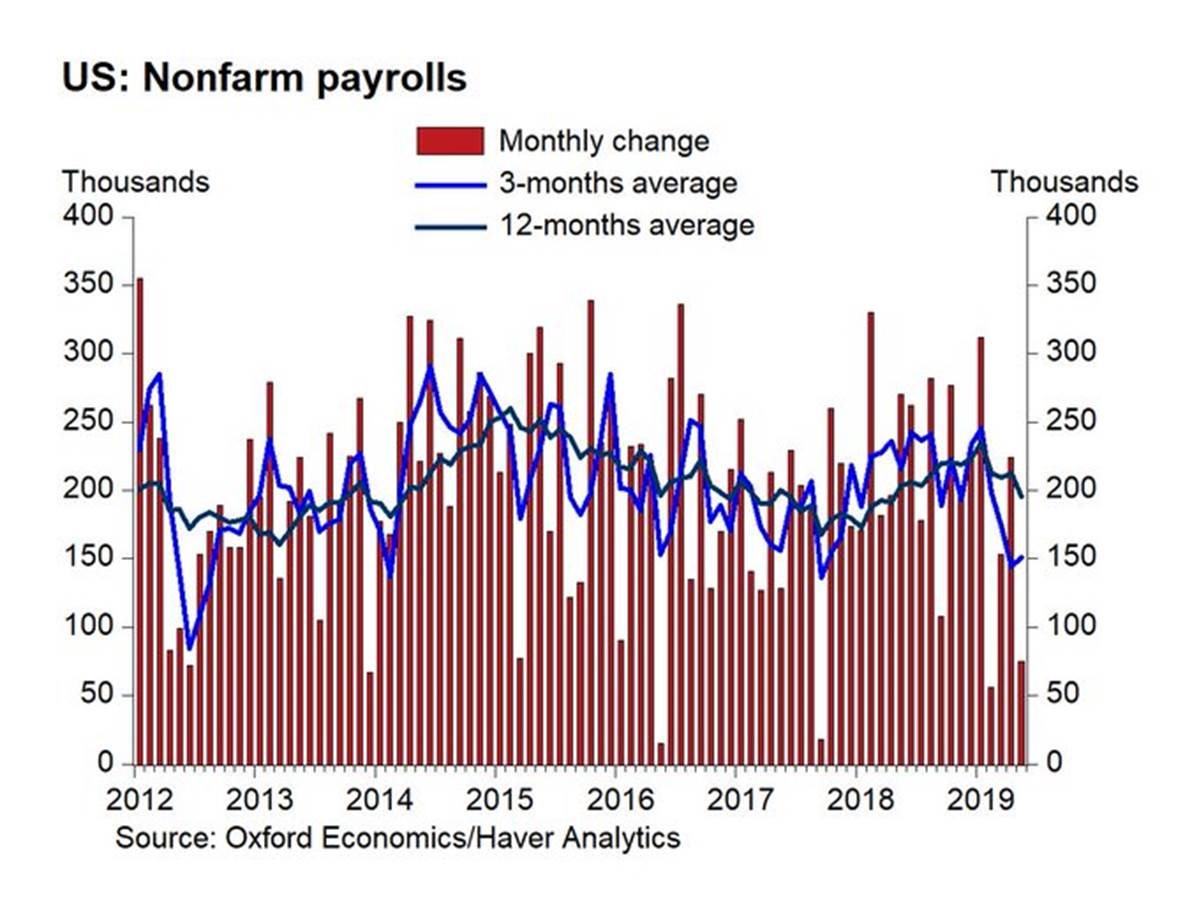
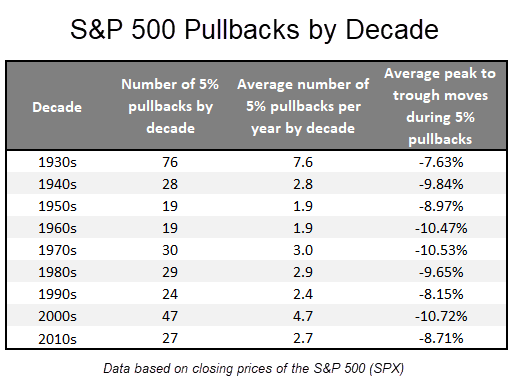
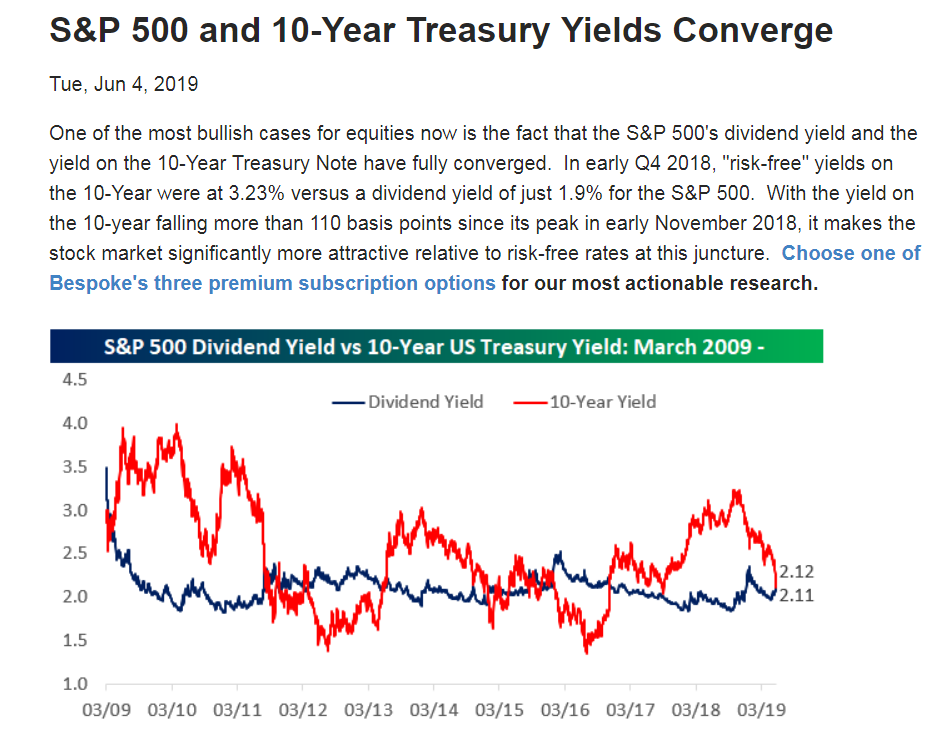
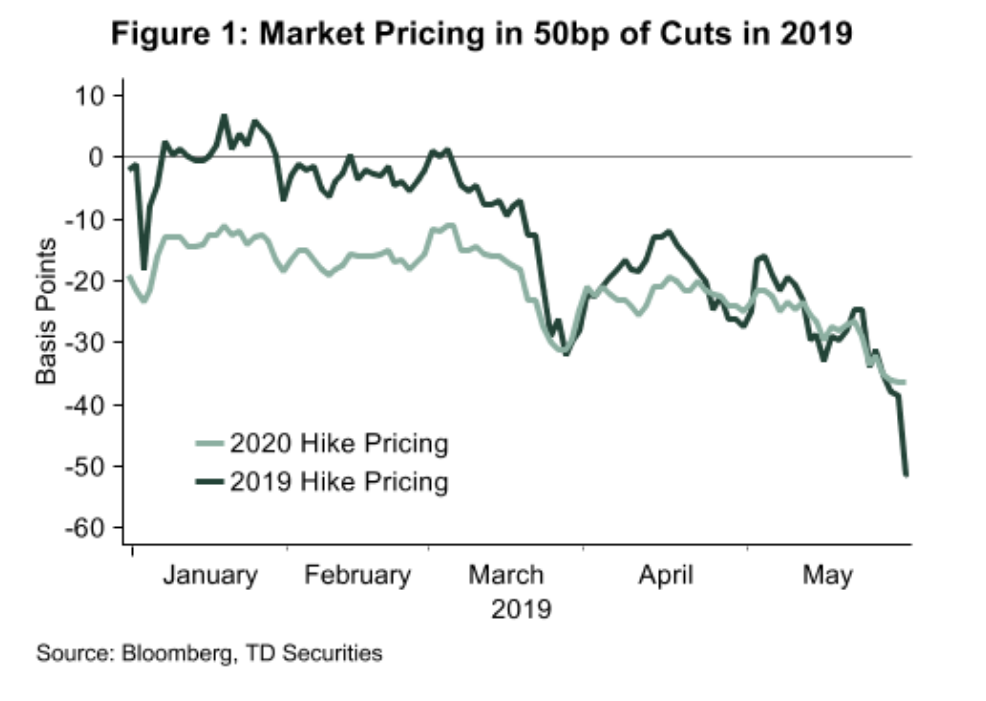
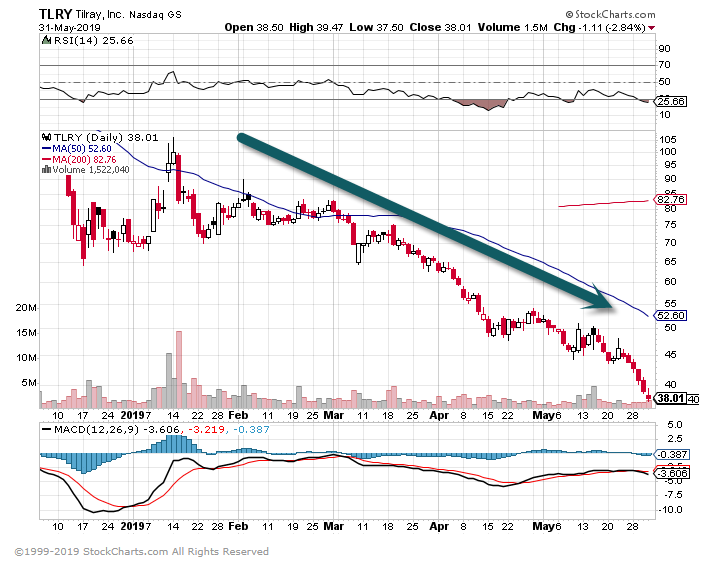
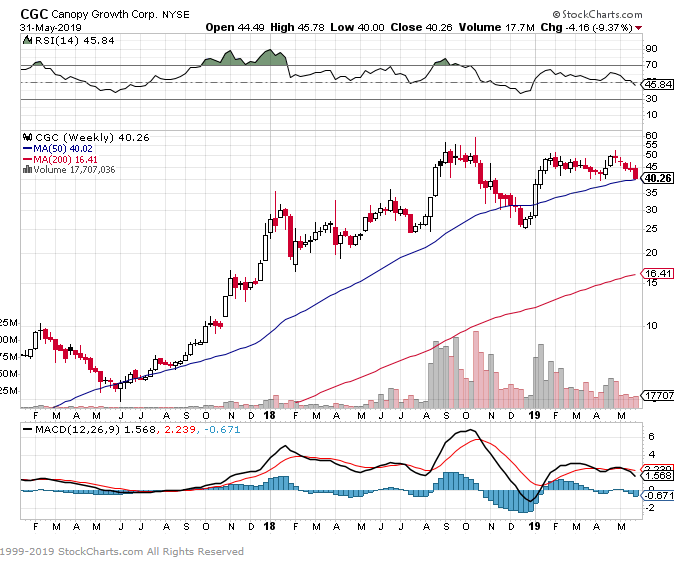
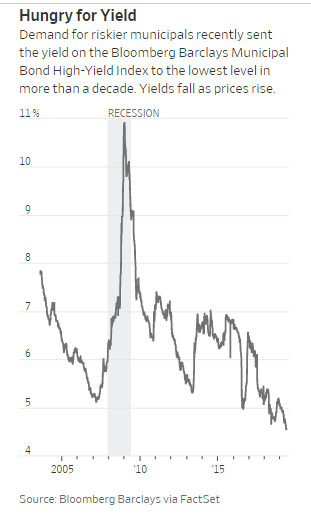
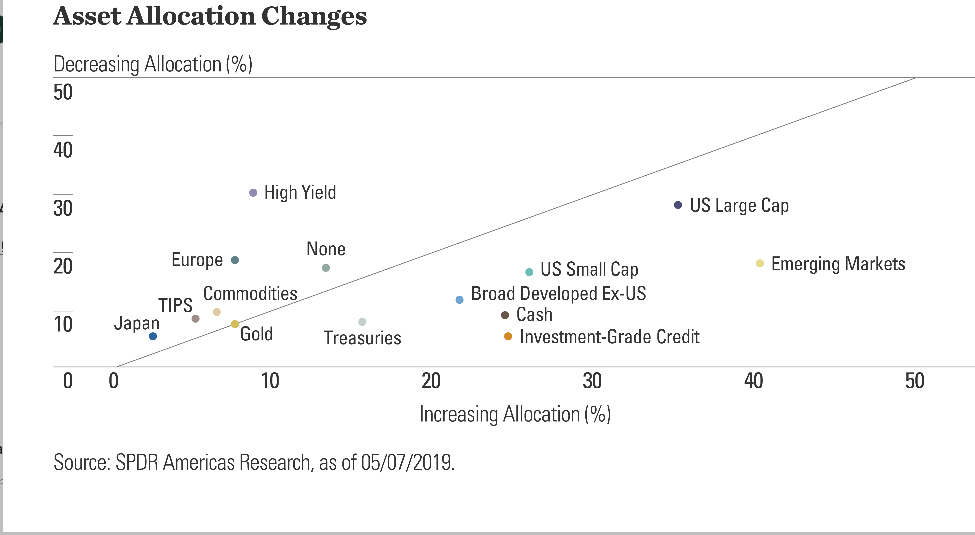
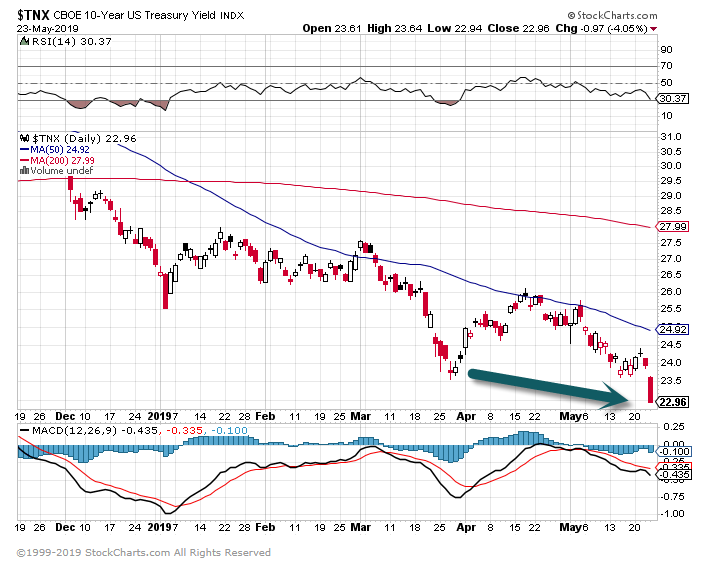
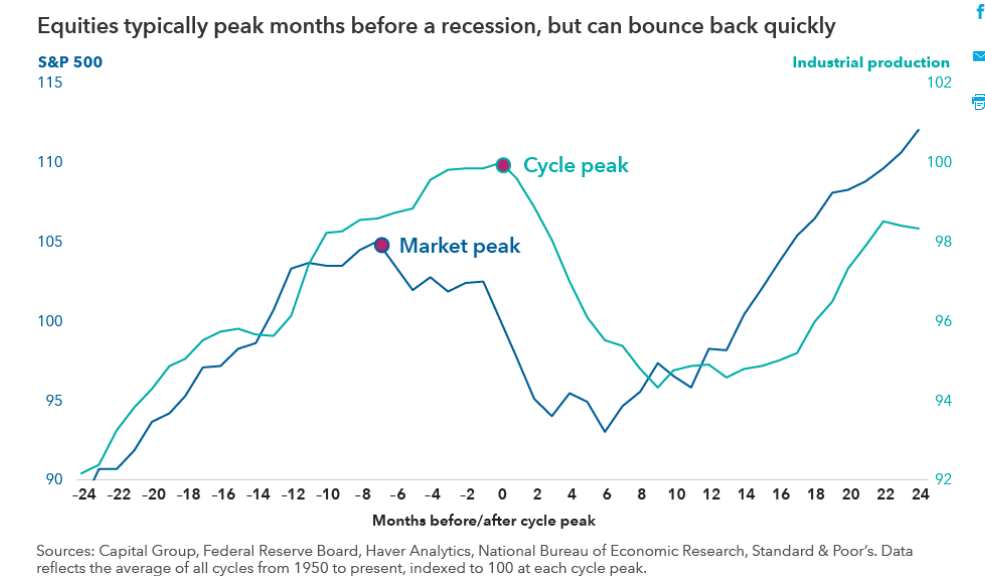
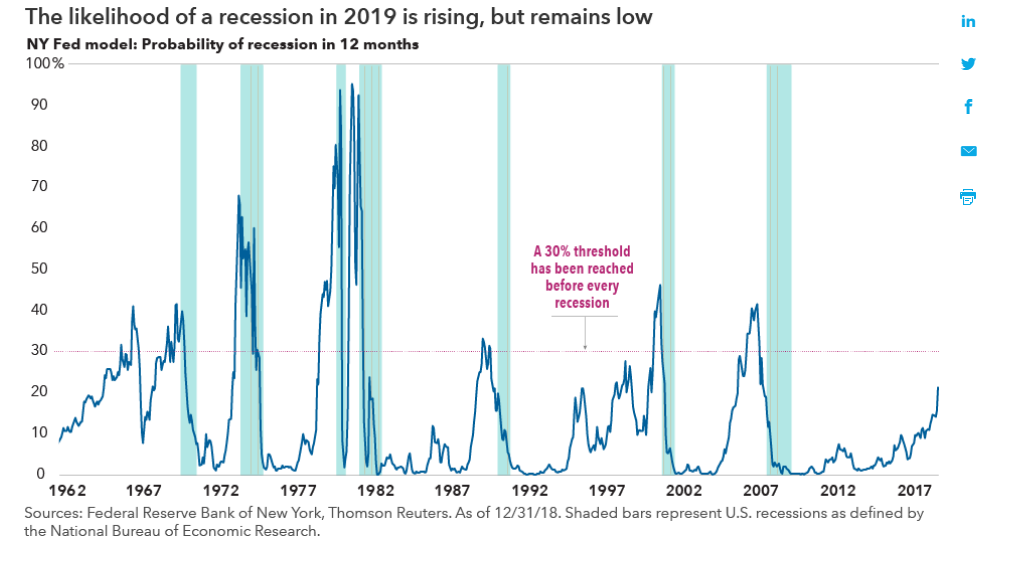
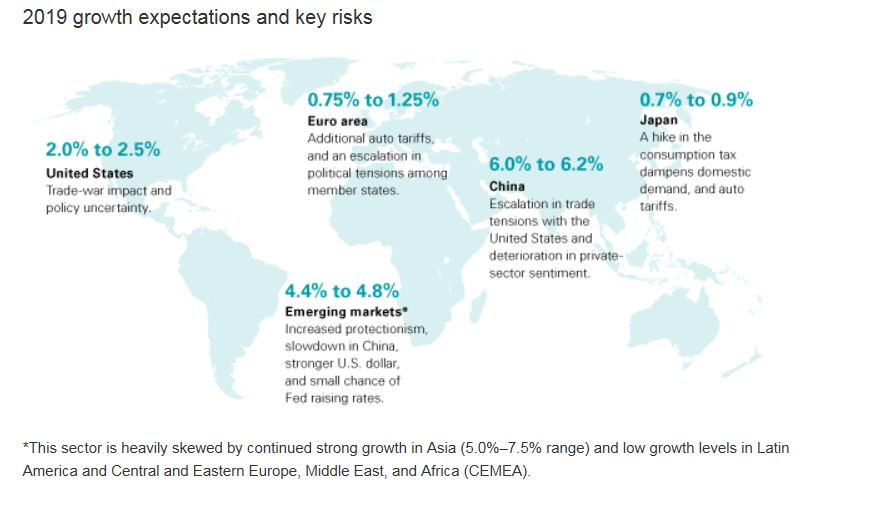
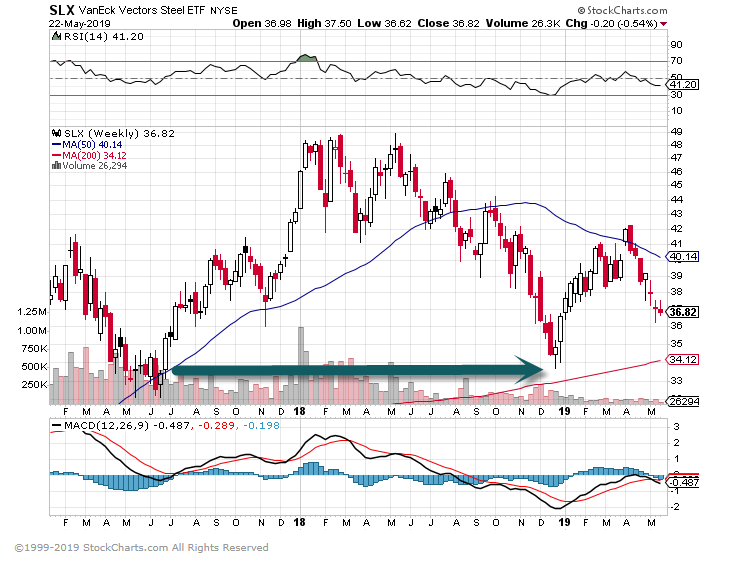
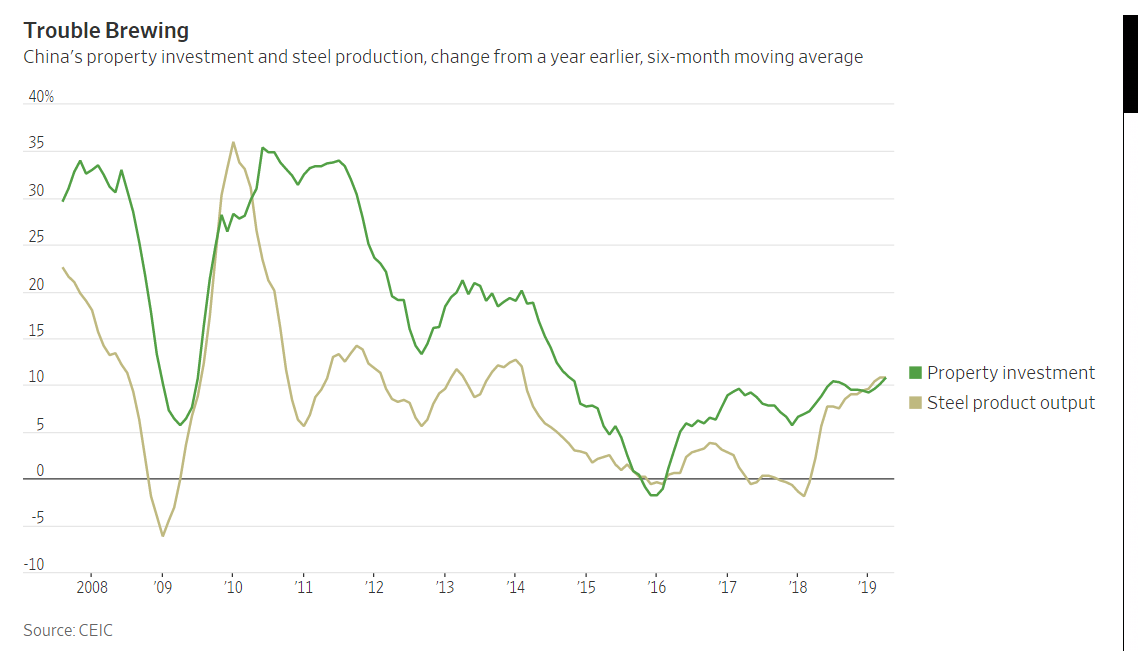
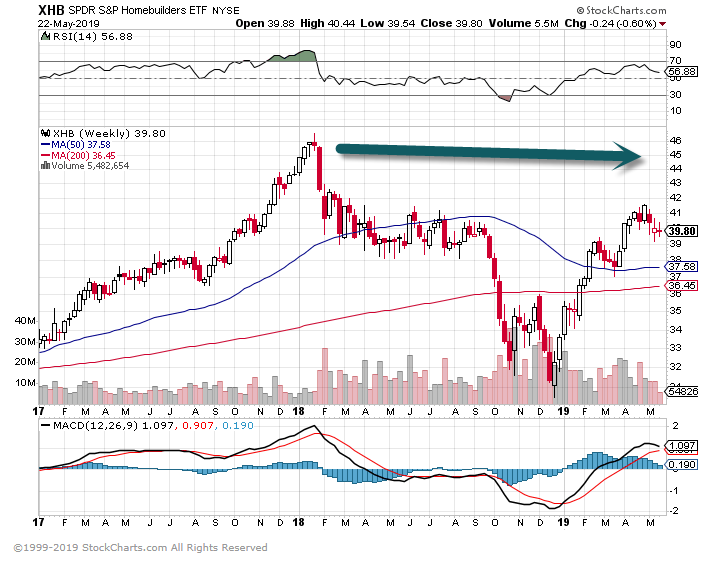
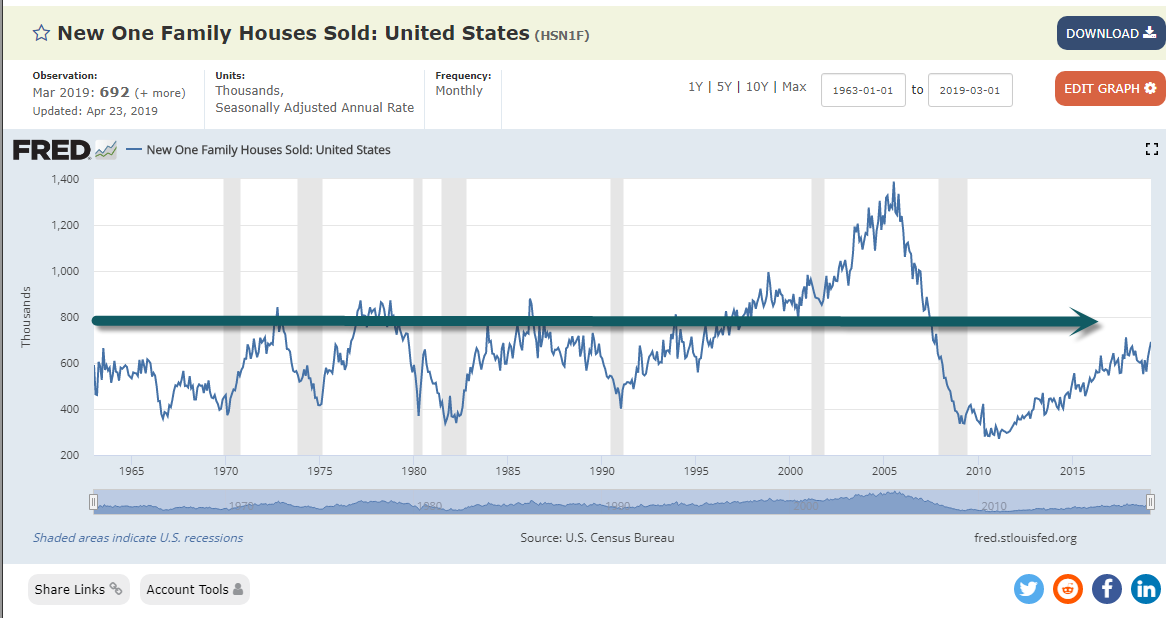
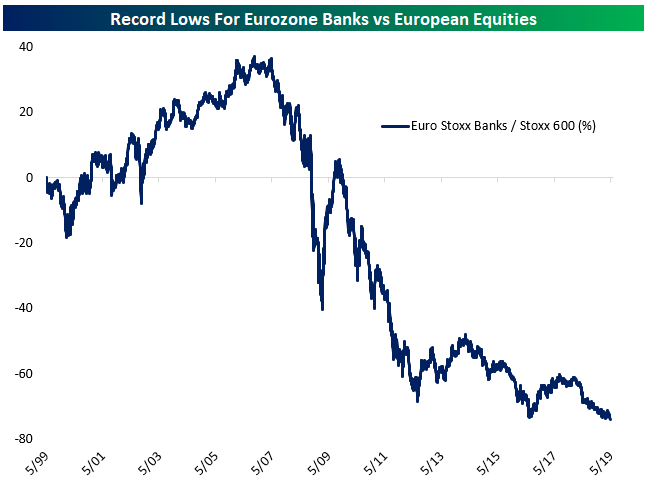
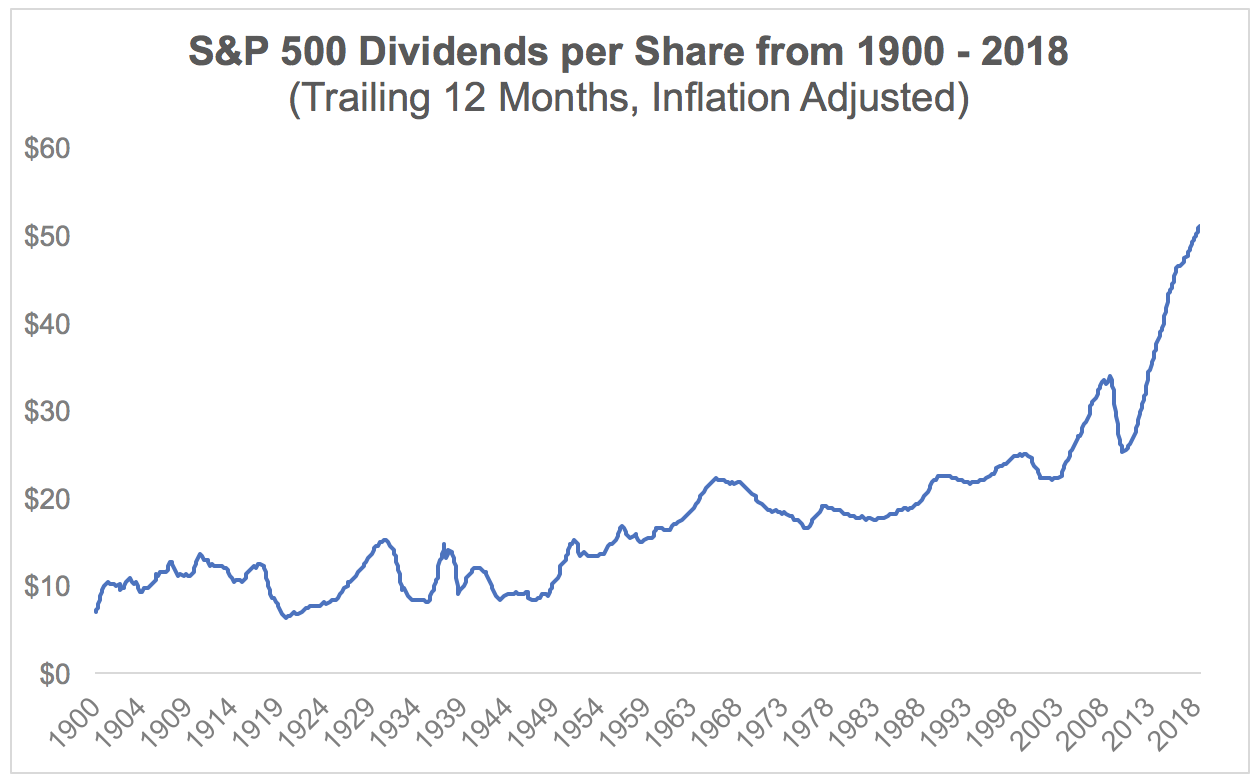
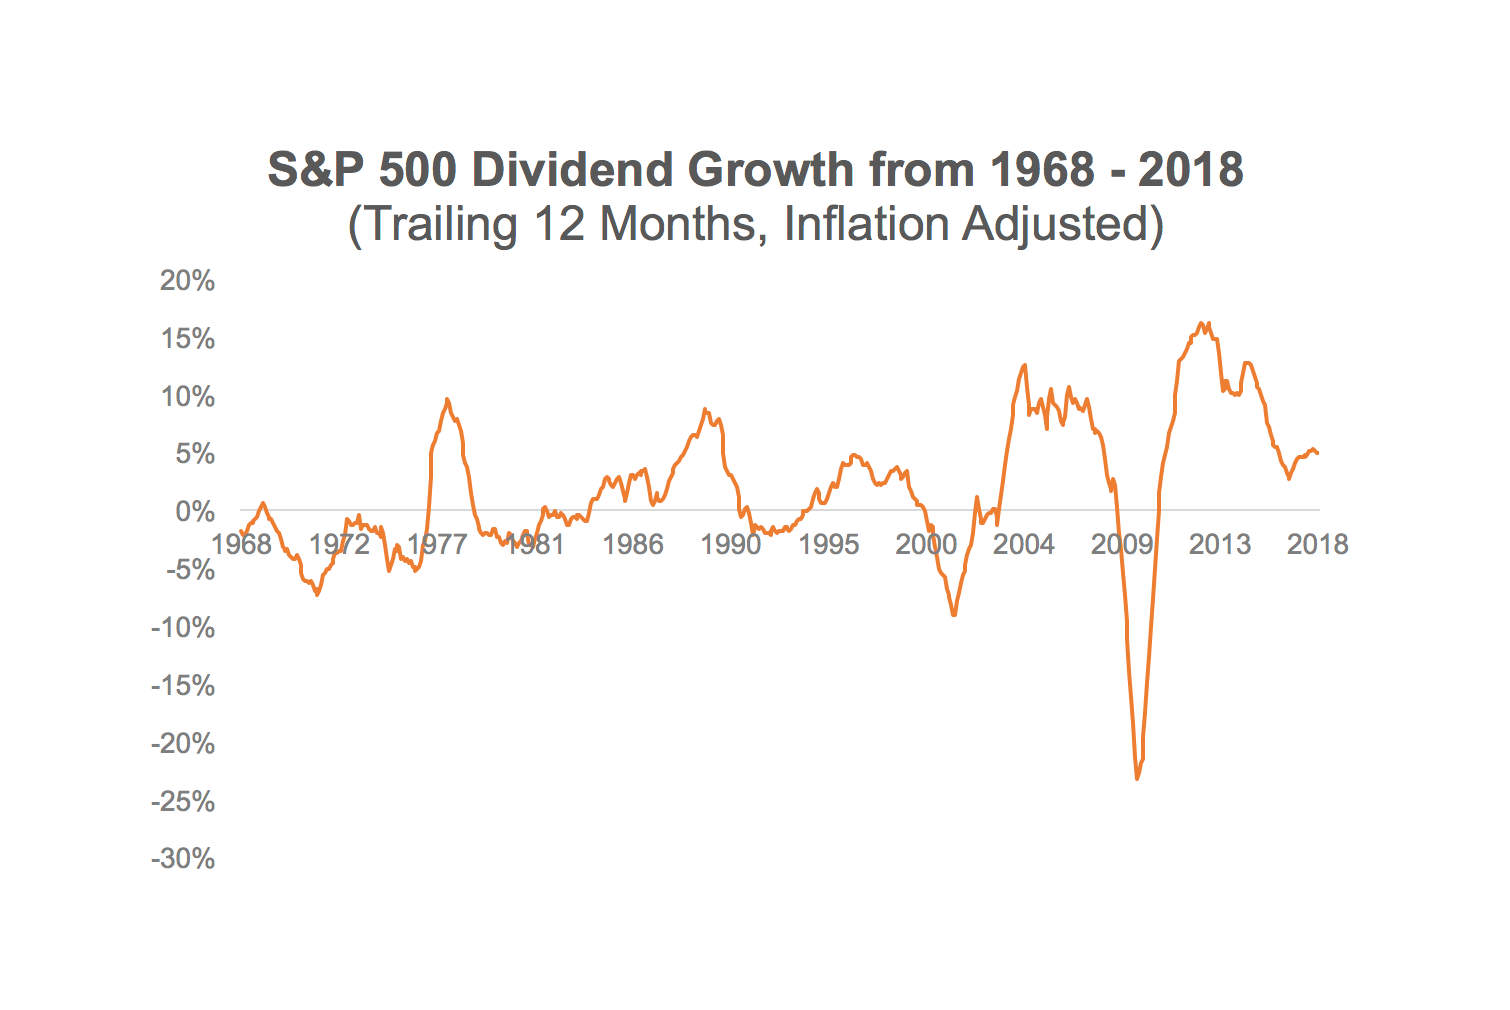
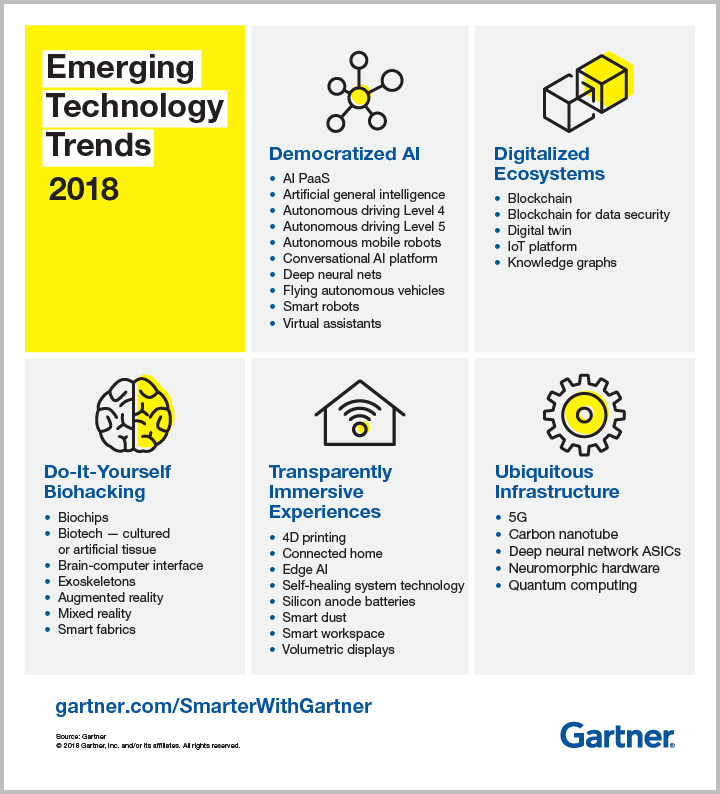
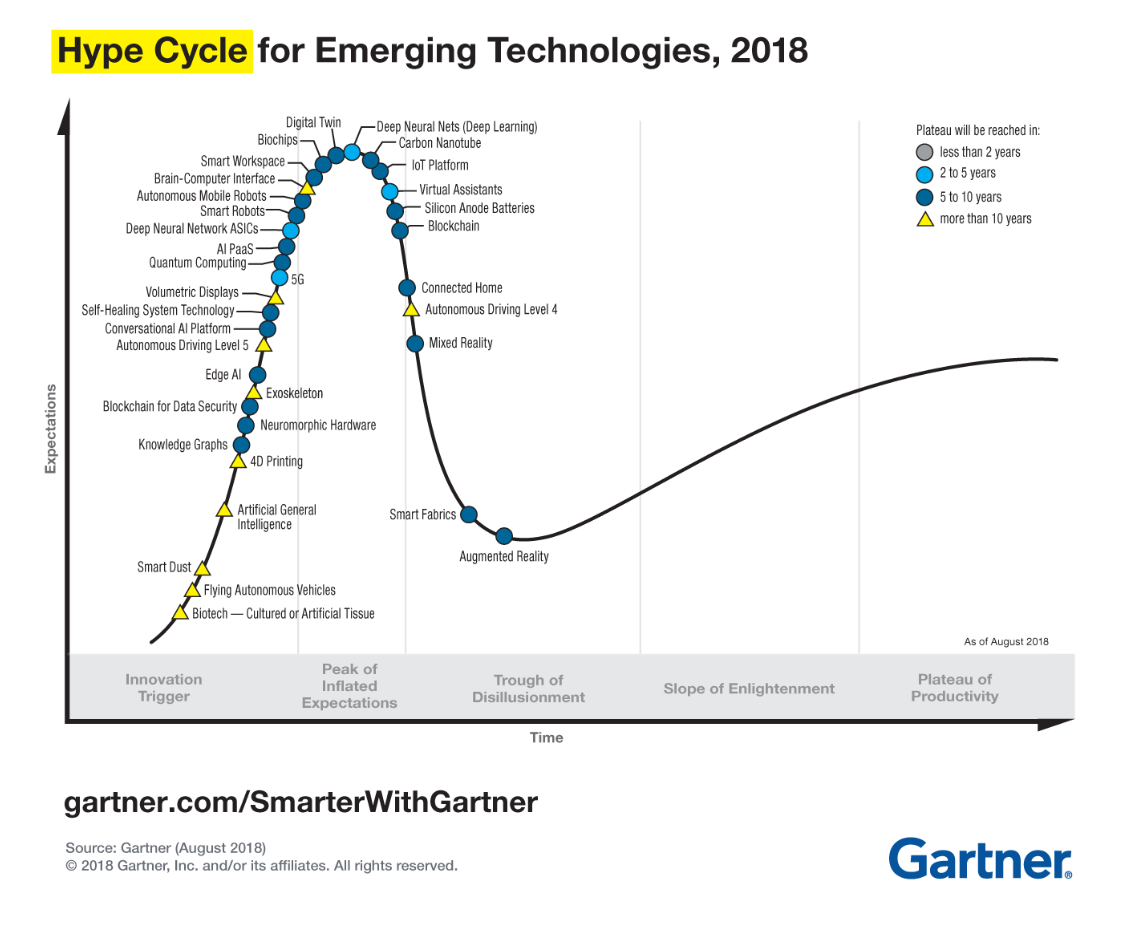
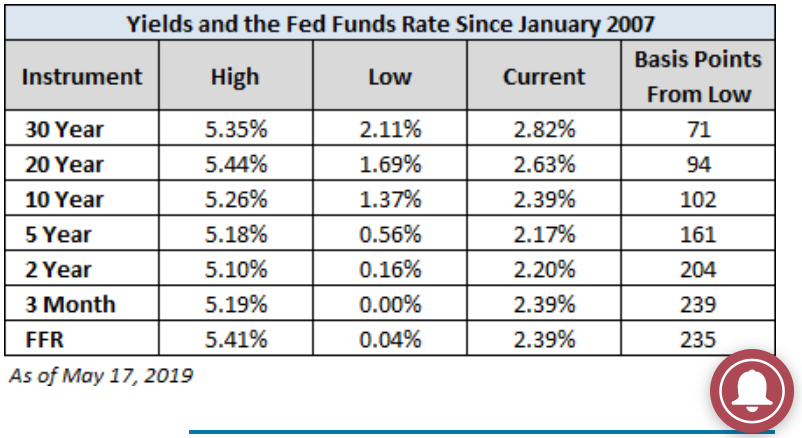
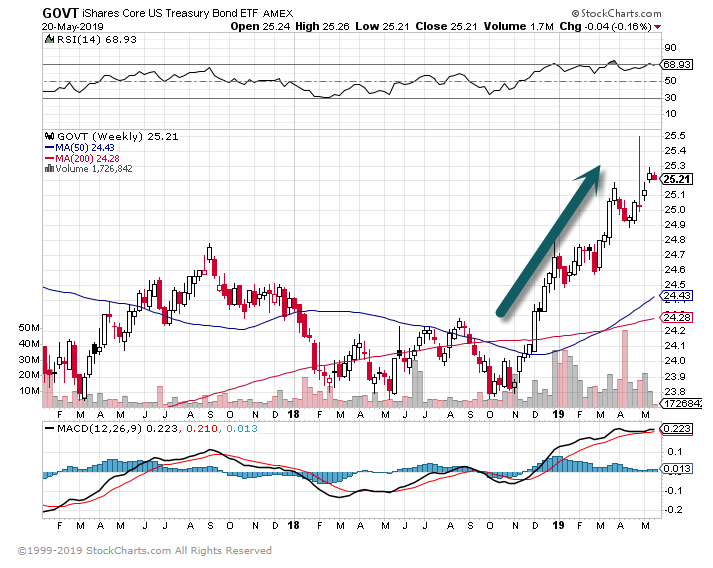

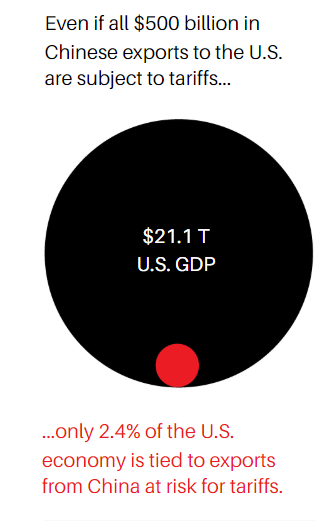
 The Trade War Will Make Stocks Scary. 5 Reasons Not to Panic. By
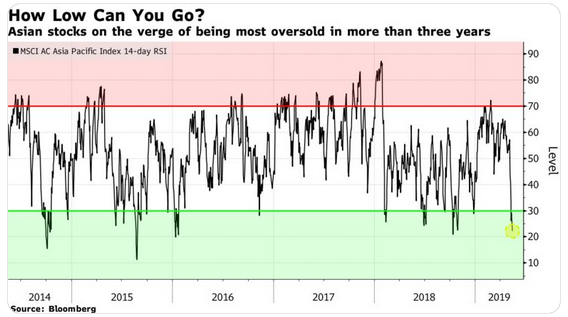
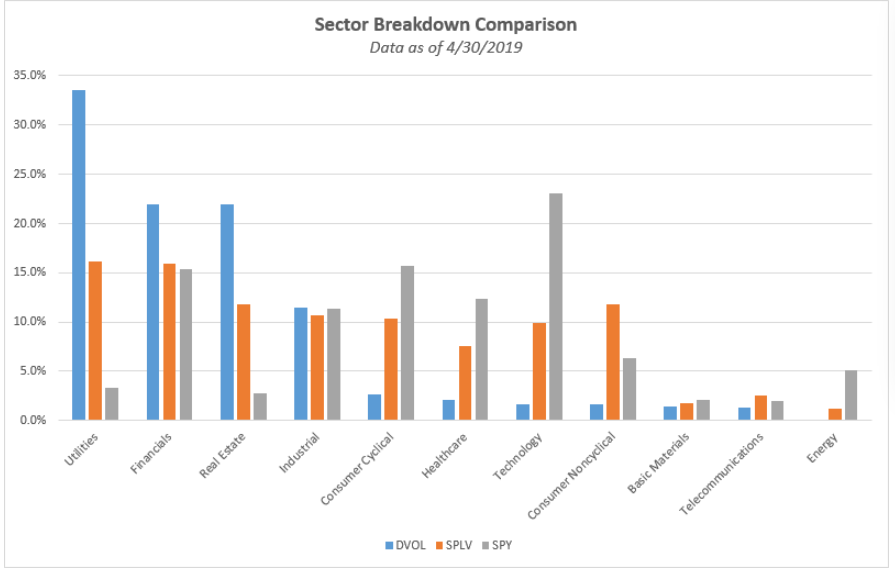
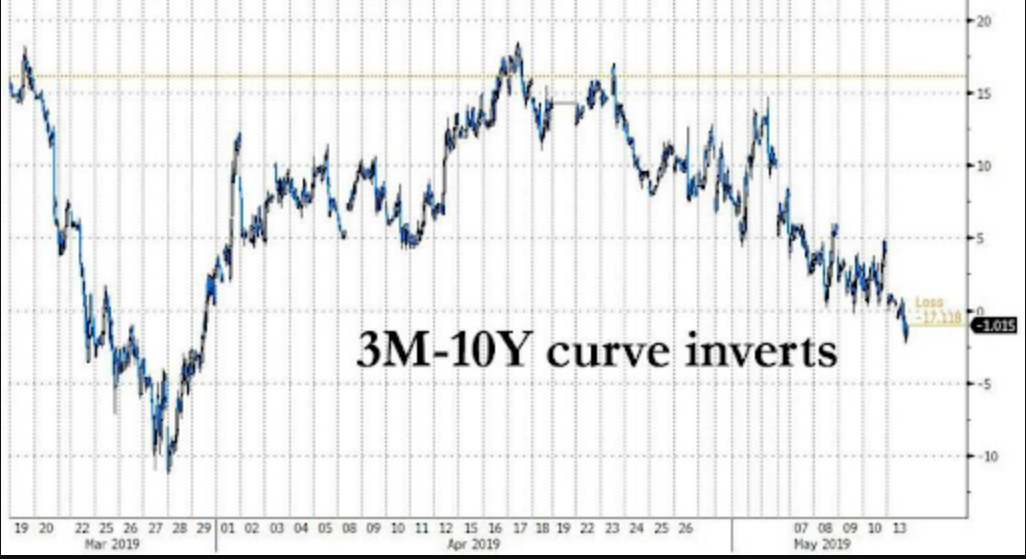
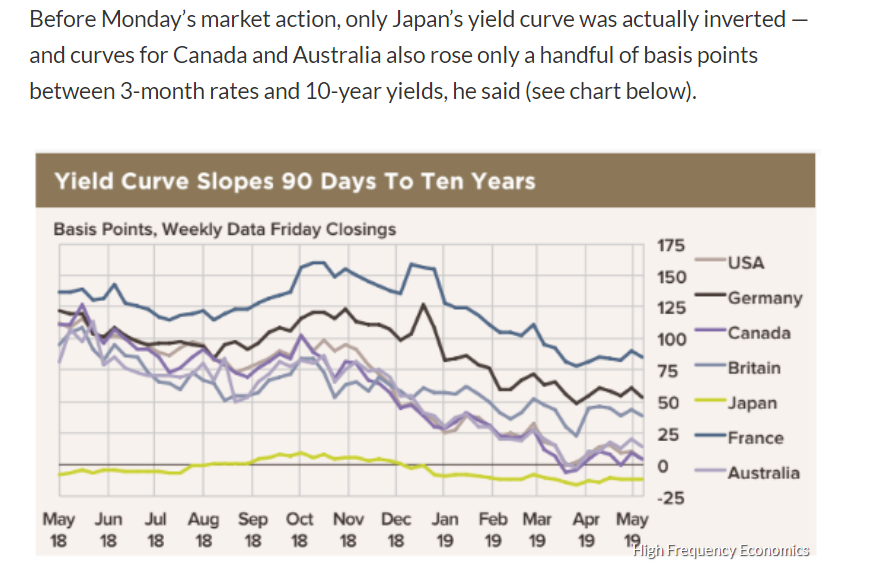 Stock-market bears say don’t forget about this yield-curve signal as trade fears sink equities