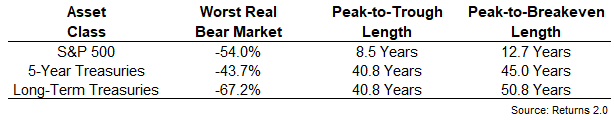Category Archives: Daily Top Ten

Topley’s Top Ten – April 9, 2019

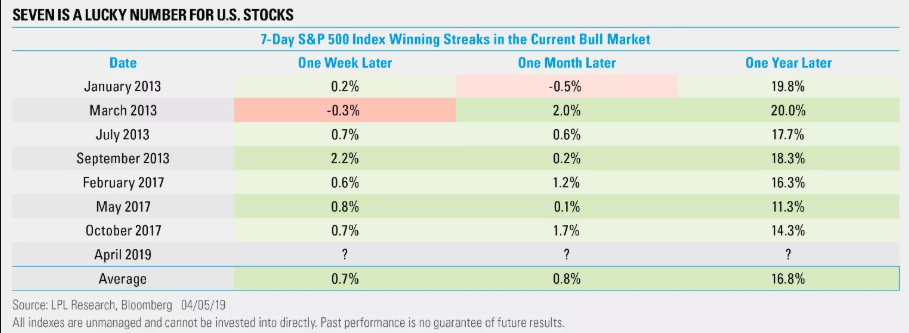
1.Seven Day Winning Streaks Historically Bullish One Year Out.

Seven has been a lucky number for U.S. stocks. The S&P 500 Index just notched its first seven-day winning streak since October 2017. As shown in the LPL Chart of the Day, this feat has occurred just seven other times in the current bull market.For the most part, each winning streak preceded both short-term and long-term gains.

https://lplresearch.com/2019/04/08/lucky-number-seven/#more-12513 Continue reading →

Topley’s Top Ten – April 5, 2019

1.Recovery Comparison of 4 Major U.S. Bear Market Recoveries.

The Four Totally Bad Bear Recoveries: Where Is Today’s Market?

by Jill Mislinski, 4/4/19

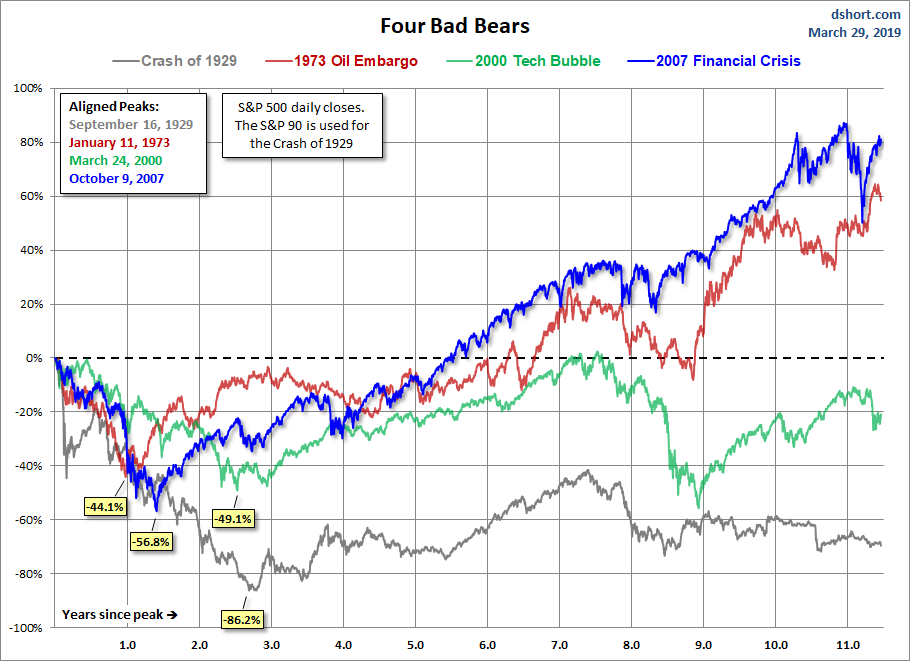
In response to a standing request, here is an updated comparison of four major secular bear markets. The numbers are through the Friday, March 29 close.

This chart series features an overlay of the Four Bad Bears in U.S. history since the equity market peak in 1929. They are:

  1. The Crash of 1929, which eventually ushered in the Great Depression,
  2. The Oil Embargo of 1973, which was followed by a vicious bout of stagflation,
  3. The Tech Bubblecrash and,
  4. The Financial Crisisfollowing the record high in October 2007.

The series includes four versions of the overlay: nominal, real (inflation-adjusted), total return with dividends reinvested and real total return. The starting point is the aligned peaks prior to the four epic declines. We’ve used an interval of 252 days for the x-axis as it is roughly the number of market days in a calendar year.

The first chart shows the price, excluding dividends for these four historic declines and their aftermath. As of the year-end close, we are now 2,887 market days from the 2007 peak in the S&P 500.

https://www.advisorperspectives.com/dshort/updates/2019/04/04/the-four-totally-bad-bear-recoveries-where-is-todays-market

  Continue reading →

Topley’s Top Ten – March 25, 2019

Top 10 will be off and on this week due to travel.

1.Story of Weekend…Yield Curve Inverted Friday.

The yield curve inverted — here are 5 things investors need to knowBy William Watts
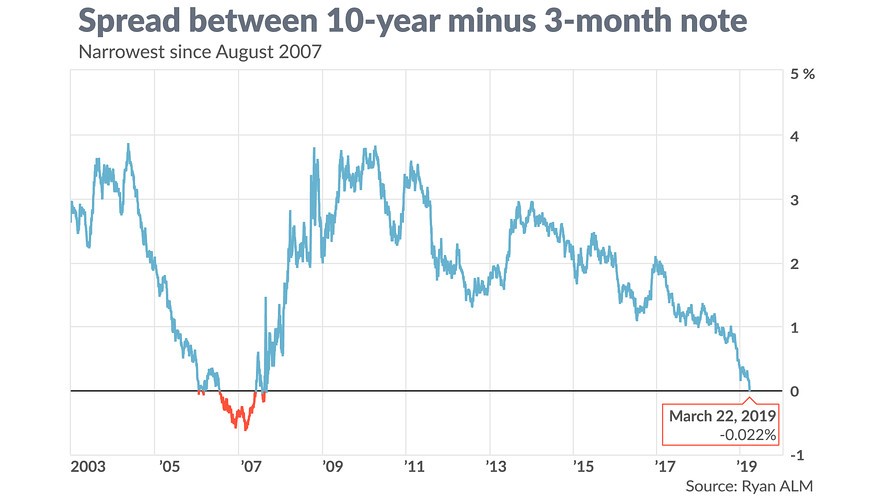
A closely watched measure of the yield curve briefly inverted Friday — with the yield on the 10-year Treasury note falling below the yield on the 3-month T-bill — and rattled the stock market by underlining investor worries over a potential recession.

But while that particular measure is indeed a reliable recession indicator, investors may be pushing the panic button prematurely. Here’s a look at what happened and what it might mean for financial markets.

What’s the yield curve?

The yield curve is a line plotting out yields across maturities. Typically, it slopes upward, with investors demanding more compensation to hold a note or bond for a longer period given the risk of inflation and other uncertainties. An inverted curve can be a source of concern for a variety of reasons: short-term rates could be running high because overly tight monetary policy is slowing the economy, or it could be that investor worries about future economic growth are stoking demand for safe, long-term Treasurys, pushing down long-term rates, note economists at the San Francisco Fed, who have led research into the relationship between the curve and the economy.

They noted in an August research paper that, historically, the causation “may have well gone both ways” and that “great caution is therefore warranted in interpreting the predictive evidence.”

What just happened?

The yield curve has been flattening for some time. On Friday, a global bond rally in the wake of weak eurozone economic data pulled down yields. The 10-year Treasury note yield TMUBMUSD10Y, +0.00%  fell as low as 2.42% and remains off nearly 9 basis points at 2.45%, falling below the three-month T-bill yield at 2.455%.

Why does it matter?

The 3-month/10-year version that is the most reliable signal of future recession, according to researchers at the San Francisco Fed. Inversions of that spread have preceded each of the past seven recessions, including the 2007-2009 contraction, according to the Cleveland Fed. They say it’s offered only two false positives — an inversion in late 1966 and a “very flat” curve in late 1998.

Is recession imminent?

A recession isn’t a certainty. Some economists have argued that the aftermath of quantitative easing measures that saw global central banks snap up government bonds may have robbed inversions of their reliability as a predictor. Since so many Treasurys are held by central banks, the yield can no longer be seen as market-driven, economist Ryan Sweet of Moody’s Analytics, recently told MarketWatch’s Rex Nutting.

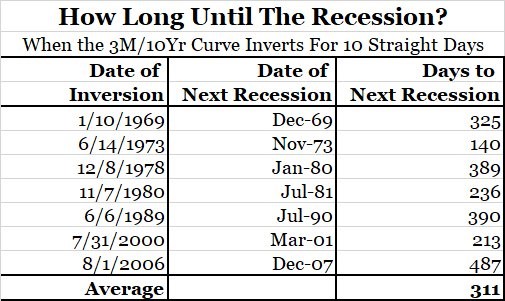
Meanwhile, recessions in the past have typically came around a year after an inversion occurred. Data from Bianco Research shows that the 3-month/10-year curve has inverted for 10 straight days six or more times in the last 50 years, with a recession following, on average, 311 days later

Replying to @alexandrascaggs

Per @biancoresearch the 10-year/3-month curve has inverted for 10 consecutive days or more 6 times in the last 50 years. On each of those occasions a recession has followed (on average 311 days later).

Bianco Research@biancoresearch
https://www.marketwatch.com/story/the-yield-curve-inverted-here-are-5-things-investors-need-to-know-2019-03-22?mod=mw_theo_homepage

Continue reading →

Topley’s Top Ten – March 6, 2019

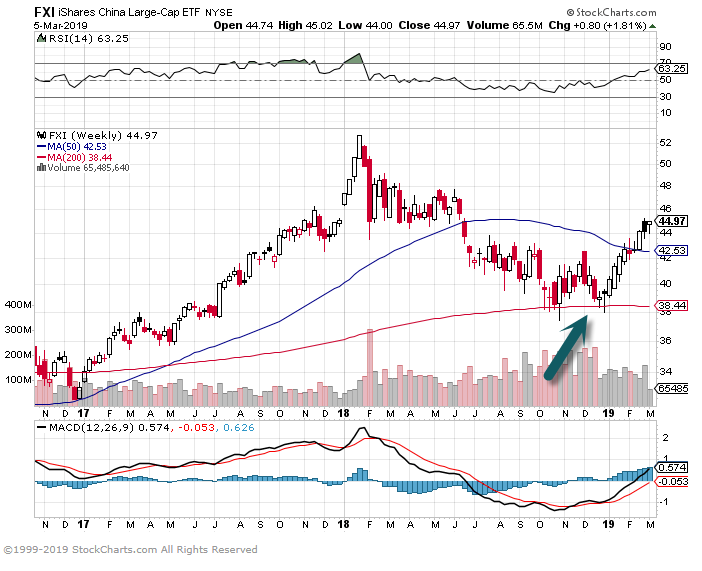
1.China stocks rally to a 9-month high after Beijing promises trade secret protection for foreign companies

  • -The Shanghai Composite Index is near a nine-month high on hopes of an end to the US-China trade war.
  • -China promised spending, tax cuts, and protection of foreign companies’ technology secrets.
  • -“A high degree of optimism [is] already baked into markets,” FXTM said.

https://www.businessinsider.com/stock-market-news-china-gains-on-foreign-ip-protection-stimulus-hope-2019-3

China ETF held 200 day on weekly chart.

China ETF daily chart 50day about to go thru 200 day to upside.

www.stockcharts.com

Continue reading →

Topley’s Top Ten – March 5, 2019

1. Kyle Bass-China has Stolen $2-$3 Trillion of IP from the U.S in the last Decade….The “ultimate arbiter” for China will be its Foreign Exchange Reserves.

Kyle Bass says trade deal with China must address IP theft: ‘They’re stealing our game from us’

“The U.S.’ No. 1 asset, in my view, is our ingenuity, our intellectual property, our ability to innovate,” Bass tells CNBC’s Brian Sullivan.

Hayman Capital Management founder Kyle Bass thinks any trade deal with China must include enforcement mechanisms against intellectual property theft for the U.S. to truly benefit from it.

“Over the last decade, they’ve stolen $2-to-$3 trillion in IP from us. The U.S.’ No. 1 asset, in my view, is our ingenuity, our intellectual property, our ability to innovate,” Bass told CNBC’s Brian Sullivan in a pre-taped interview that aired on “Worldwide Exchange.” “That’s our game and they’re stealing our game from us. It’s really important for this new agreement to be measurable and punishable.”

https://www.cnbc.com/2019/03/04/kyle-bass-us-china-trade-deal-needs-to-be-punishable-on-ip-theft.html

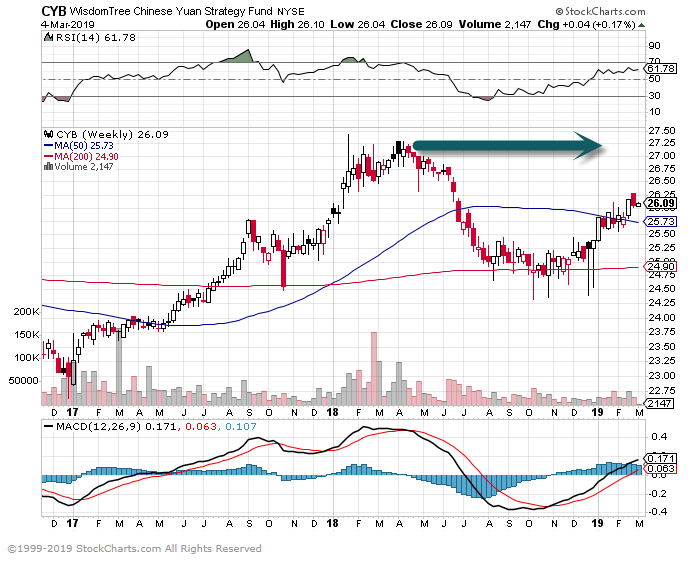
Chinese Yuan—Rally but below highs.

www.stockcharts.com

Continue reading →

Topley’s Top Ten – March 4, 2019

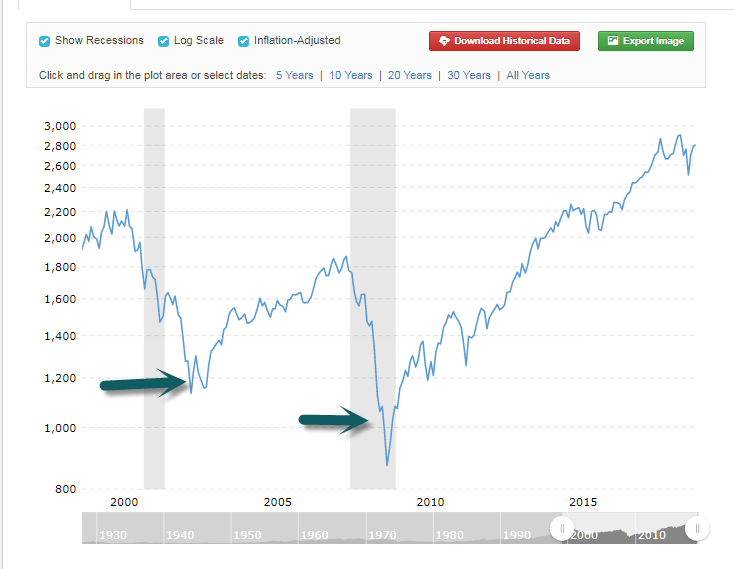
1.CAGR S&P 20 Years…5.52%

It’s Been a Rough 20 Years for Stocks. The Next 20 Should Be a Lot Better

Vito J. Racanelli

A higher-than-expected December payrolls number helped push the market up 3.4% on Friday. Yet stocks had their worst first two days of the year since 2000. Where the market will be in a year has little to do with where it is now. Twelve months ago, stocks were coming off a 22% return in 2017 and feeling fine, thank you very much—until September. Then, the wheels fell off.

Ironically, there is more certainty in picturing the market’s next 10 or 20 years. That’s the time frame investors should use. They rarely examine the trailing returns of past decades, but they should. There’s one number that explains a lot of things: 5.52%. Over the 20 years ended 2018, that’s been the nominal compound annual growth rate (CAGR) of the S&P 500.

It might not feel like it after a decade-long bull market, “but we are coming off 20 of the worst years for compounded returns since the Great Depression,” says Nicholas Colas, co-founder of DataTrek Research. The average trailing 20-year market CAGR since 1928 is 10.7%. Blame the two negative-35%-plus bear markets since 2000.

This low return has given birth to, among other things, the rise of passive investing and the growth of exchange-traded funds. It has forced commissions down and encouraged the use of automation to further reduce broker expenses. Institutional investors, pension funds, and sovereign-wealth funds have taken on more risk—shoveling money to venture capital and private equity—to make their required rates of return, typically 7% to 10%, Colas says.

It is hard to imagine our most recent big winners, theAmazon.com s (ticker: AMZN), Alphabet s (GOOGL), andApple s (AAPL) of the world doubling their market capitalizations in the next 10 years (a 7% CAGR). To start seeing better long-run returns, the market needs lots of new blood, he says, a fresh crop of disruptive tech companies, to come public. The good news is that some, like Uber Technologies and Lyft—and potentially Airbnb and others—are preparing to do so.

The best thing about sitting at the low end of a historical range is that mean reversion should start to kick in, Colas says, and the next 10 to 20 years from here will likely be pretty good. Happy now? As for 2019, tell me if there will be a recession, and I’ll tell you where the market is going

S&P 20 Year Chart…2 35% Drawdowns.

https://www.macrotrends.net/2324/sp-500-historical-chart-data

  Continue reading →

Topley’s Top Ten – February 28, 2019

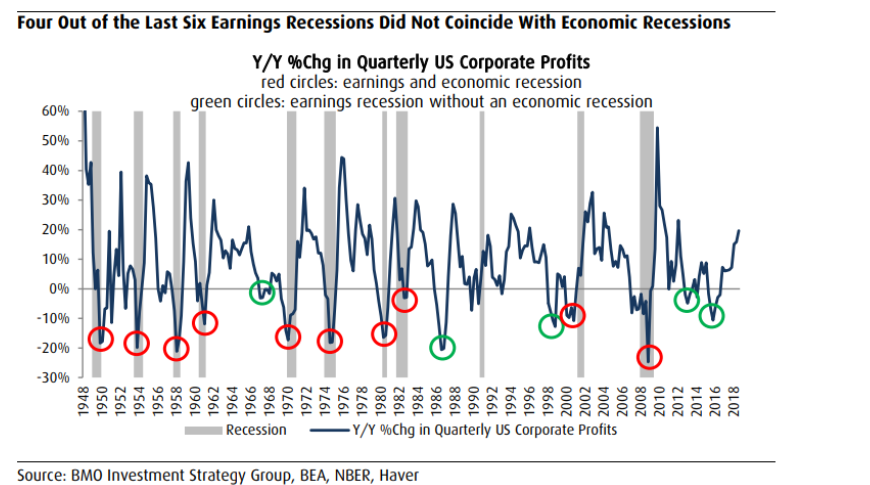
1.Earnings Recession Does Not Necessarily Mean Economic Recession

The idea is that an earnings recession would lead to a conventional economic downturn, with rising unemployment, falling consumption and even broader downward pressure on profits — but that’s not actually true, Belski said in an interview.

Indeed, an earnings recession has happened six times since 1987 — but a real recession has followed only twice, Belski said. That alone should mitigate any fears that an earnings slowdown would come back to bite the market, he said.

Furthermore, when earnings downturns happen and economic recessions don’t follow, the S&P has risen an average of 17.6% over the next year, he said, citing the five times this has happened since 1967

Opinion: What ever happened to that earnings recession?By Tim Mullaney

https://www.marketwatch.com/story/what-ever-happened-to-that-earnings-recession-2019-02-27

Continue reading →

Topley’s Top Ten – February 25, 2019

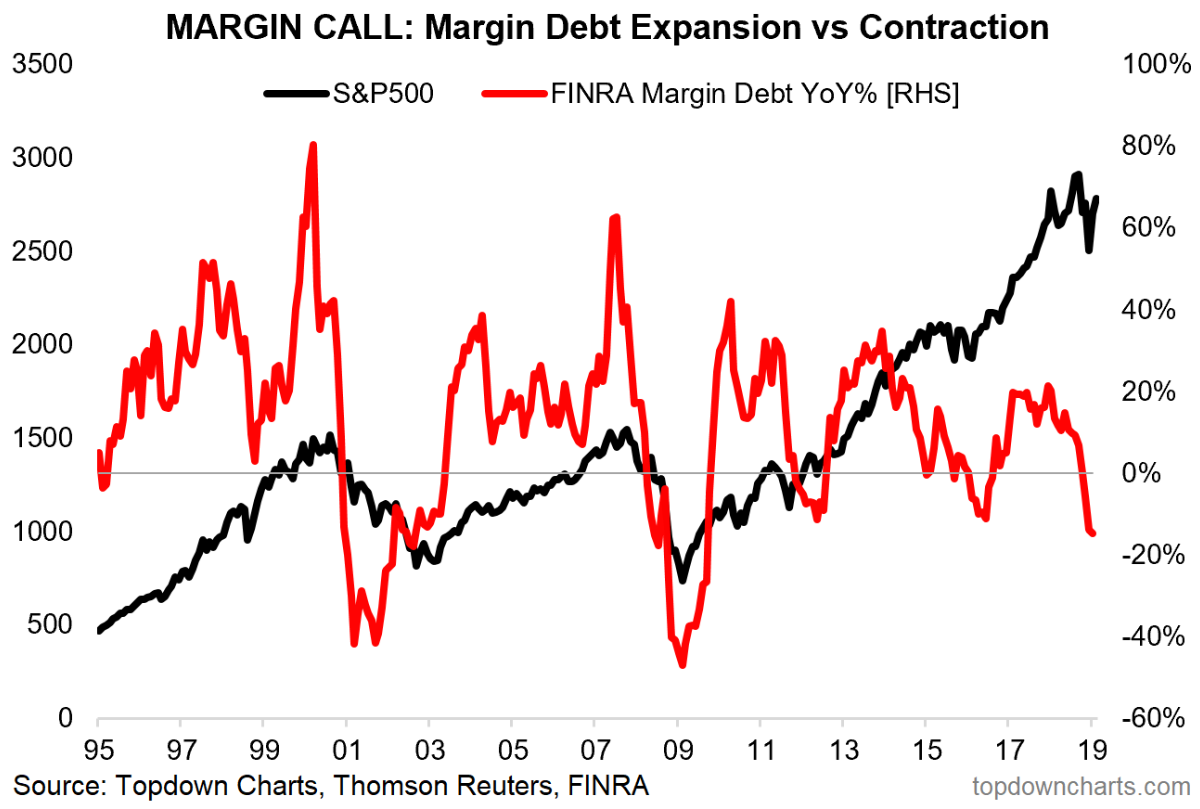
1.Historical Margin Chart.

Margin Call — Margin Debt Accelerometer:  Here’s an interesting chart, basically a bear market warning indicator; the year over year change in US margin debt [note it used to be called NYSE margin debt, but now FINRA publishes a broader set of data].  The basic concept is that when margin debt is contracting on an annual basis it can serve as a bear market warning signal (margin calls and lower risk appetite).  Only thing I would add is that in the 2000 & 2008 experiences there was a substantial acceleration in margin debt growth before the contraction signal was triggered, so one might argue the lack of that acceleration weakens the signal this time around…


Continue reading →

Topley’s Top Ten – February 22, 2019

1.Domino’s vs. Google.

Pizza Pays — Domino’s Delivers Over Google

Feb 21, 2019

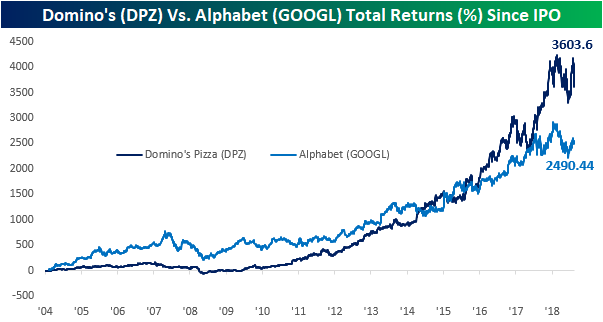
If you were sent back in time to 2004 and had the choice to buy Domino’s Pizza (DPZ) or Alphabet (GOOGL) at their IPO, which would have been the better choice?  Due to the epic size and influence of its business, impulse would probably have you choose Alphabet.  But DPZ has actually seen significantly better returns than GOOGL since the companies’ IPO dates. Since inception, DPZ has seen a total return of 3,604% even after today’s 9.03% decline in the stock in reaction to an earnings miss this morning.  Not that GOOGL’s 2,490% return is something to turn your nose at, but it is dwarfed by DPZ’s returns.  For the stocks’ first decade, up until 2014, this was not the case though.  GOOGL had actually outperformed DPZ for much of their lifespans as public companies.  From then up until early 2016, the two stocks alternated between being the leader, but in the last two years, Domino’s ran away with things.  Part of the reason for this is DPZ has fairly consistently paid a dividend since 2004 which is why returns for the stock have been considerably better over the long term.

https://www.bespokepremium.com/think-big-blog/

Continue reading →

Topley’s Top Ten – February 21, 2019

1.Record Selling of U.S. Stocks and Bonds in December of 2018

Torston SLok

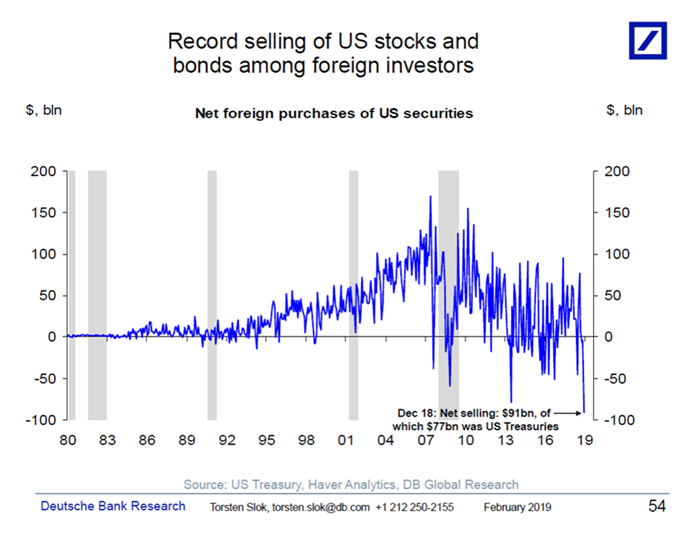
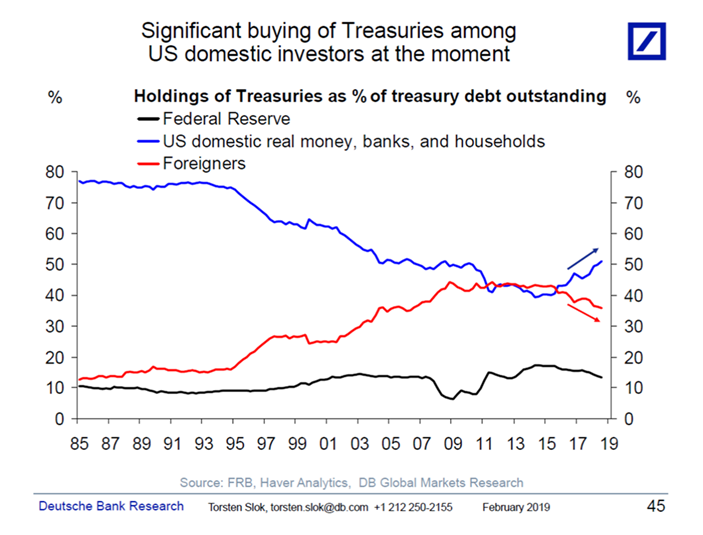
In December foreigners sold a record $91bn in US stocks and bonds, see chart below. Roughly 85% of this amount, or $77bn, was the rest of the world selling US Treasuries. Despite this significant upward pressure on US rates during the stock market rout in December 10-year rates still went from 3.20% in November to 2.60% in early January. This reveals how strong the domestic bid is from pension funds and banks for US Treasuries at the moment, see also the second chart below. For more on the rates outlook see also our latest Fixed Income Weekly here.

Continue reading →

Topley’s Top Ten – February 13, 2019

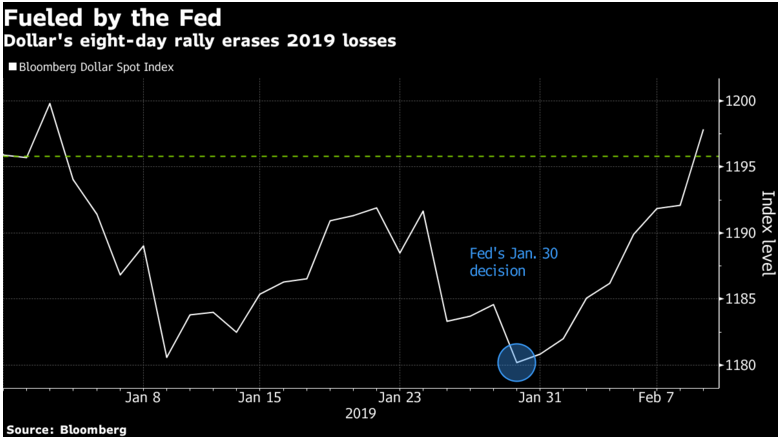
1.Dollar Back to Even for the Year….Recouped All Early Year Losses.

“The dollar’s not weakening, and the reason for that is that the Fed is just the beginning, in the sense that all other central banks are most likely going to become dovish,” said Momtchil Pojarliev, head of the currencies group.

The greenback climbed 0.5 percent Monday to recoup its year-to-date losses, and is enjoying its longest winning streak since January 2016. The currency’s surprising strength has upended forecasts across Wall Street, with firms such as Morgan Stanley and Nomura having called for dollar losses. It’s also put a chill on U.S. corporate earnings.

While the Fed’s about-face would typically vindicate those calls, the darkening outlook for the dollar’s peers should support it in the days ahead, according to Kit Juckes, a Societe Generale SA global fixed-income strategist. The euro is a case in point: A lurch lower in German yields and sputtering European growth saw the common currency touch its lowest level since November on Monday.

“The problem for dollar bears is that there is a chronic shortage of currencies to like,” Juckes said. “Lower bund yields, not to mention weak growth, political uncertainty and Brexit, make a good set of reasons to hate the euro as much as you hate the dollar.”

https://www.bloomberg.com/news/articles/2019-02-11/panicking-doves-add-fuel-to-dollar-s-longest-rally-in-3-years

Continue reading →

Topley’s Top Ten – January 21, 2019

1.China posts slowest economic growth since 1990

LINGLINGWEI
BEIJING– China’s economic expansion languished to its slowest pace in nearly three decades last year, as a bruising trade fight with the U.S. exacerbated weakness in the world’s second-largest economy.

The 6.6% growth rate for 2018 reported Monday is the slowest annual pace that China has recorded since 1990. The economic downturn, which has been sharper than Beijing expected, deepened in the final months of 2018, with fourth quarter growth rising 6.4% from a year earlier.

Adding to the gloom was the trade conflict with Washington. The uncertain outlook for Chinese exporters caused companies to delay investing and hiring and in some cases even to resort to layoffs–a practice that is often discouraged by China’s stability-obsessed Communist Party rulers. The official jobless rate ticked up to 4.9% last month from 4.8% in November.

In the southern technology and export-manufacturing center of Shenzhen, for instance, many private makers of electronics, textiles and auto parts furloughed workers more than two months before the Lunar New Year holiday, which begins in February, according to business owners and local officials. The neighboring city of Guangzhou saw growth slump to 6.5% last year–well short of the 7.5% annual target set by the city government–as trade tensions hit the city’s manufacturing sector hard.

Some economists and investors have said China’s economy is far more anemic than the government’s 6.6% rate of expansion for 2018. They note the government’s move on Friday, just ahead of Monday’s data release, to cut the 2017 growth rate to

“The economy faces downward pressure,” said Ning Jizhe, head of the National Bureau of Statics, at a news conference Monday. In particular, Mr. Ning pointed to “complicated and severe external environment.”

Write to Lingling Wei at lingling.wei@wsj.com

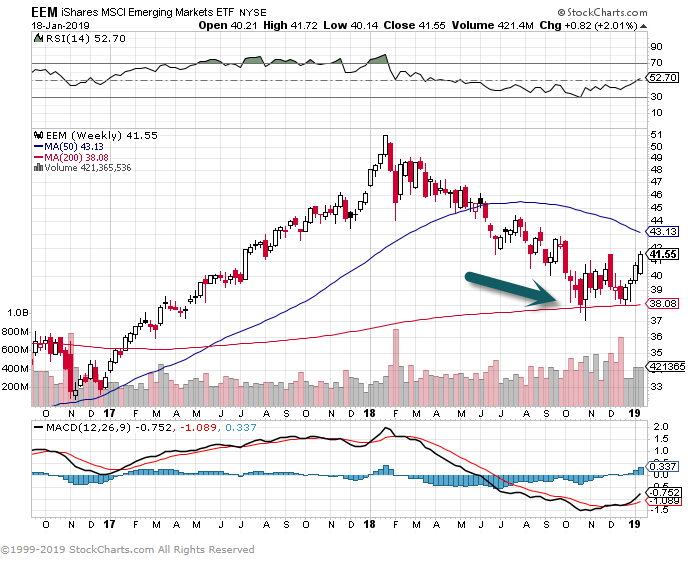
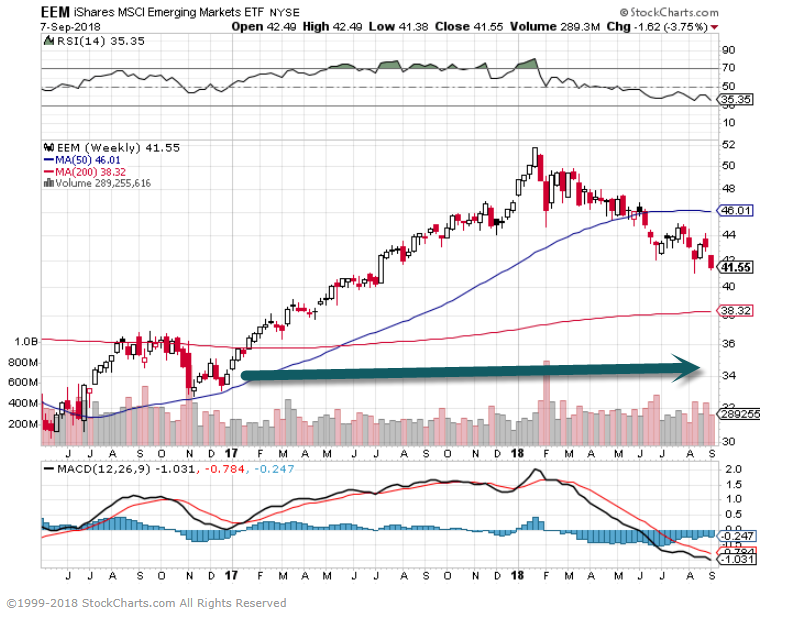
EEM-Emerging Markets ETF traded to 200day twice and held on long-term weekly chart.

www.stockcharts.com

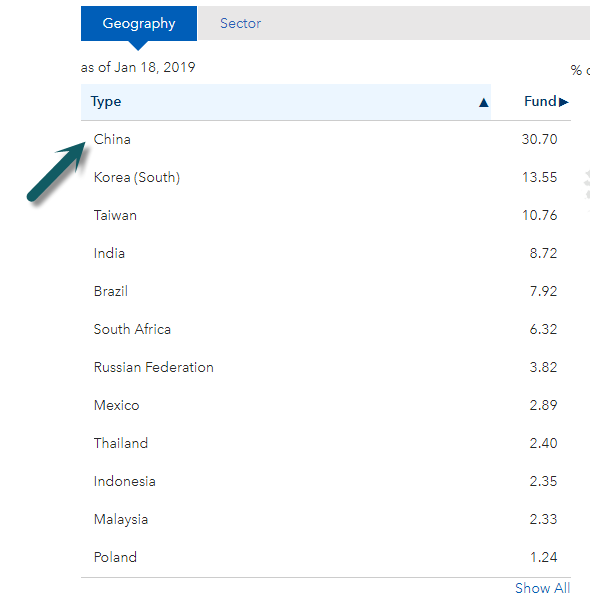
China 30% of Fund

https://www.ishares.com/us/products/239637/ishares-msci-emerging-markets-etf

  Continue reading →

Topley’s Top Ten – January 18, 2019

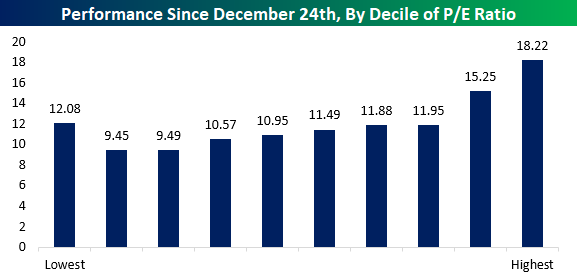
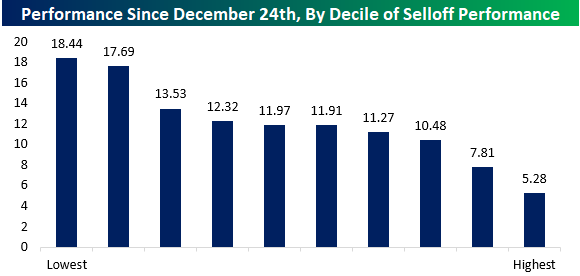
1.Performance Based on Valuations Since Dec. 24th Lows.

Bespoke

The first chart below shows the performance of S&P 500 stocks based on their valuations as of 12/24 with the most attractively valued (lowest P/E ratios) stocks to the left and the most expensive (highest P/E ratios) on the right.  The best performing decile by far was the one containing the stocks with the highest P/E ratios, and for the most part, performance steadily declined as you moved left towards the more attractively valued stocks.  The second chart shows performance since the lows based on stocks grouped according to how they performed during the market decline.  Here, the best-performing stocks were the ones that were originally down the most, while the worst performing stocks were the ones that held up the best during the decline.

In both cases, these performance results make perfect sense.  During market sell-offs, as investors become more risk averse it is typical to see stocks with the most aggressive valuations sell-off the hardest while more reasonably priced stocks hold up better.  However, when the market turns around and investors become less risk-averse, they flock to the more aggressive high growth/high valuation stocks.  Likewise, when the market shifts its tone from a defensive posture (during a sell-off) to a more offensive tone (rally) it is only natural that the stocks that held up the best during the defensive phase (like Utilities) underperform during the next more aggressive phase.  Anything else would be contrary to the norm.

Start a two-week free trial to Bespoke Premium to see today’s full Morning Lineup report. You’ll receive it in your inbox each morning an hour before the open to get your trading day started.

https://www.bespokepremium.com/think-big-blog/

Continue reading →

Topley’s Top Ten (Short Version) – January 15, 2019

Click Here for Quarterly letter

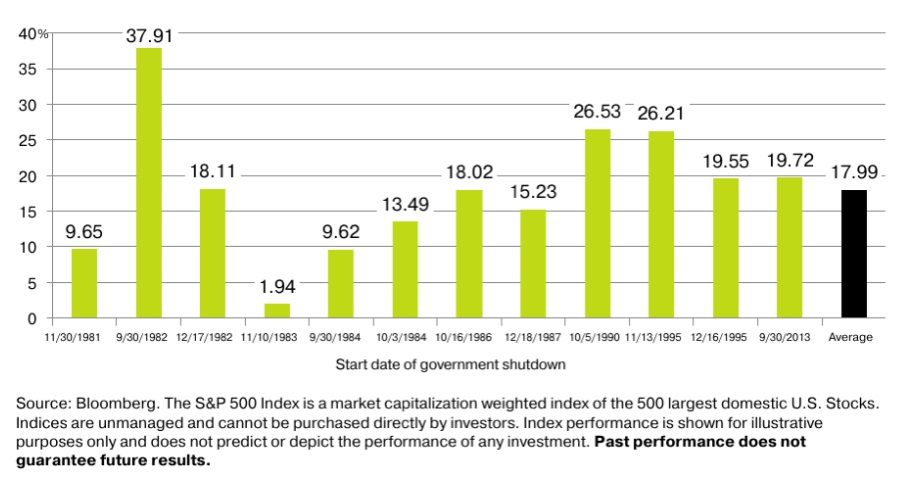
1.Aggregate S&P Total Return 12 Months Post-Shutdown.

Renmac Research

Without much certainty of a potential end to the political gridlock, we look to factors such as the aggregate S&P 500 index total return 12 months post-shutdown. To receive updates from our Washington Policy Analyst Steve Pavlick & the full team, connect here: http://qoo.ly/uj4xx

https://www.linkedin.com/company/renaissance-macro-research/

Continue reading →

Topley’s Top Ten – January 14, 2019

1.Quarterly Letter.

As Springsteen Takes Off on Broadway, Investors Got Blinded By the Light

January 9, 2019

Matt Topley
4th Quarter, 2018

 “She Got Down But She Never Got Tight She’s Gonna Make It Through the Night”

Blinded by the Light

Blinded by the light
Revved up like a deuce
Another runner in the night

She got down but she never got tight
She’s gonna make it through the night

Songwriters: Bruce Springsteen
Blinded by the Light lyrics © Downtown Music Publishing

Springsteen’s off-Broadway

I recently watched Springsteen’s fabulous Broadway performance on Netflix, having seen The Boss over 20 times myself, it still was unreal to hear him tell personal stories around growing up and his career.  As I watched one of the most volatile stock market year ends in history, I couldn’t help but apply investors psyche to a Springsteen song.  Most investors got Blinded by the Light, it was just too easy, buy FANG stocks, buy S&P index, buy anything.  After 2017 being one of the least volatile years in market history including no drawdown of S&P over 3% versus historical annual average drawdown of 14%, the market sent a giant wake-up call that investing is always emotional including an all-time record almost 3% Christmas Eve smack down.  Here’s the good news, it seems she (market) is going to make it through the night as she always does, it’s not 2008 or anything close, we have some wood to chop in the short-term but valuations are reverting to mean.

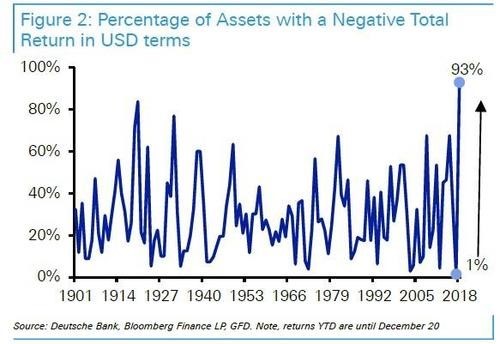
2018 was a historic year for financial markets in more ways than one-first time in 27 years that stocks and bonds were both negative in the same year, worse stock market December since 1931, over 90% of investable assets were negative in 2018, and no asset class returned over 5% for the first time since 1974.

A Record Share of Asset Classes Posted a Negative Return in 2018

Investors felt pain this year across the board as diversified portfolios were nowhere to hide, in fact some well diversified holdings returned less than the S&P due to exposure to bonds, commodities, international stocks and U.S. small cap stocks.  Three of these groups were down more than the S&P and most bonds were flat to negative.  The tradtional 60/40 model was negative for the year with returns coming in 13% below historic median, if you’re 60/40 was global returns were even lower.  Target Date funds are popular and growing especially in 401k plans, see below as they are posting first negative returns in 10 years.

Read Full Letter
Continue reading →

Topley’s Top Ten (short version) – January 11, 2019

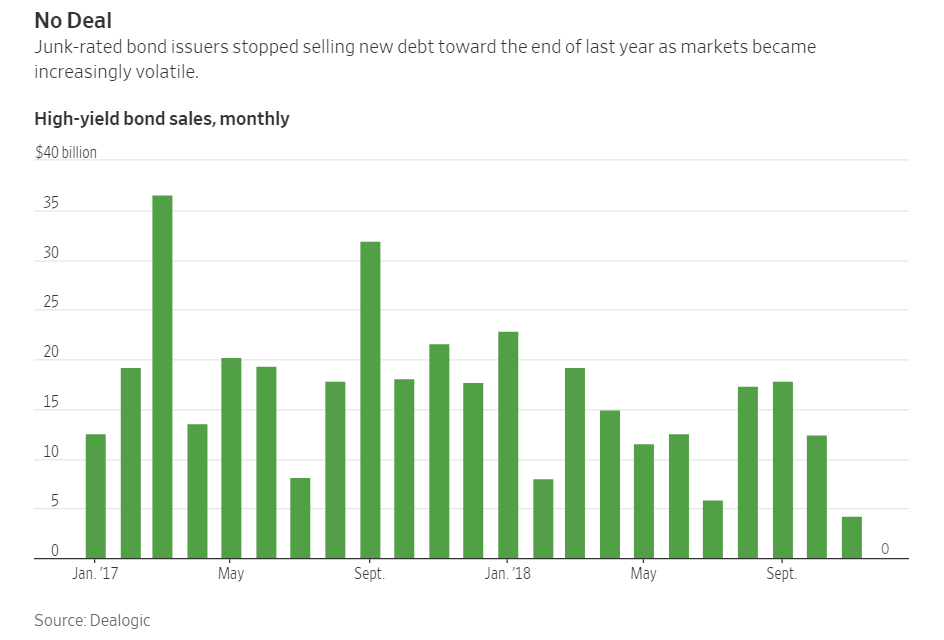
1.Junk Bond Sales Dried Up at End of 2018.

Slack investor demand recently lifted to the highest level in more than two years the premium, or spread, that companies with junk credit ratings must pay over risk-free government debt. The corresponding fall in high-yield bond prices last quarter erased investors’ gains in what had been one of the few bright spots in the bond market in the first nine months of 2018.

Junk-rated companies haven’t been completely absent from the debt markets. Issuance of so-called leveraged loans totaled $25 billion in November and December, according to LCD, a unit of S&P Global Market Intelligence. But that was still a significant slowdown from prior months.

Junk-Bond Sale Ends 40-Day Market Drought

Deal follows record dry spell that began in November, suggesting an improving corporate-debt market

By
Daniel Kruger and Sam Goldfarb

https://www.wsj.com/articles/a-junk-bond-drought-is-making-investors-nervous-11547116200 Continue reading →

Topley’s Top Ten – December 10, 2018

1.$Trillion Dollars in Stock Buybacks…Record.

Buybacks certainly helped in the afternoon – With today’s buyback announcements, value announced so far this year now above $1 trillion, highest yearly figure ever … even backing out Apple’s $100 billion announcement this year, 2018 is still the highest on record

From Dave Lutz at Jones Trading.

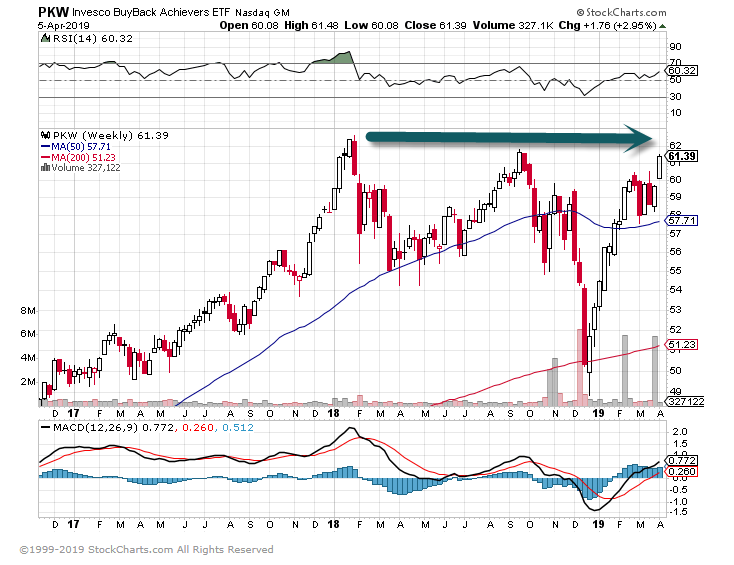
BUYBACK ETF PKW Trailed S&P All Year.

www.yahoofinance.com

Continue reading →

Topley’s Top Ten – November 19, 20185

1.Thanksgiving Market Returns

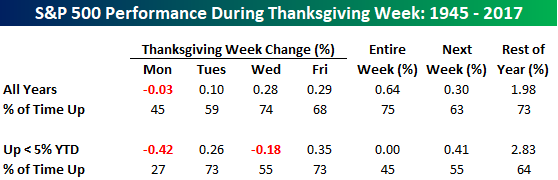
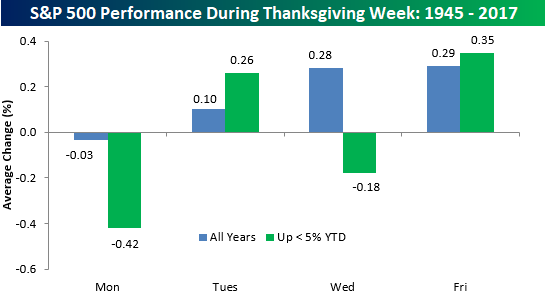
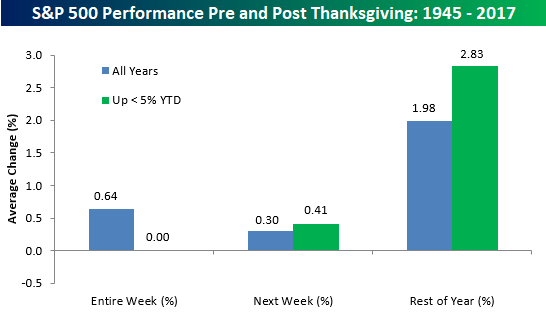
Thanksgiving week has historically been a positive time for the equity market.  Since WWII, the S&P 500 has averaged a gain of 0.64% during Thanksgiving week with gains three-quarters of the time.  Market trends heading into this Thanksgiving aren’t as positive for the bulls, though.  As shown in the table below, during years where the S&P 500 was positive but up less than 5% YTD heading into Thanksgiving week, the index’s average change during the week has been 0.00% with gains less than half of the time.

On a day to day basis, for both all years since WWII and in years where the S&P 500 was up less than 5% heading into Thanksgiving week, Monday has been the worst trading day as it is the only day of the week with negative average returns and positive returns less than half of the time.  Tuesdays and Friday, however, have been positive days, though, with average gains of 0.10% and 0.29%, respectively.  Additionally, for those years where the S&P 500 was up YTD but up less than 5%, Tuesdays and Fridays have been even stronger with average gains of 0.26% and 0.35%, respectively.

As we move past Thanksgiving, though, seasonal trends for the market based on this year’s performance so far improve.  In those years where the S&P 500 was up less than 5% YTD heading into Thanksgiving week, the average gains the week after Thanksgiving was 0.41% with positive returns 55% of the time.  For the remainder of the year, average returns were even stronger at +2.83%.  Not bad for a period of just over five weeks!

https://www.bespokepremium.com/think-big-blog/

Continue reading →

Topley’s Top Ten – November 15, 2018

1.Earnings…Positive Sales Surprise Slow Down.

Jefferies

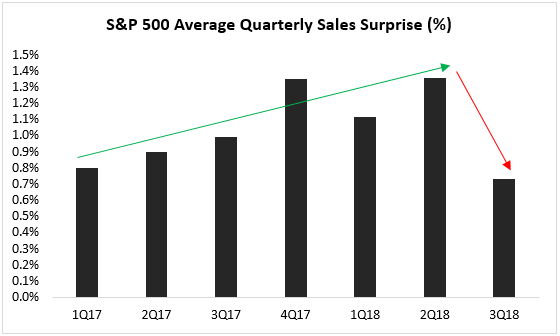
3Q earnings did not materialize as the positive catalyst investors were hoping for following Powell PBS, Pence China speech & US-China sentiment deterioration, PPG pre-announcement, IMF global growth downgrade, etc – all in early October.

The qualitative commentary from Q3 included slowing demand in China/EM/Europe (particularly auto), margin pressure, and trade war impact.

The average sales surprise was the lowest going back to 1Q17 – breaking a largely positive surprise trend over the prior 6 quarters.

Source: Jefferies Trading Desk

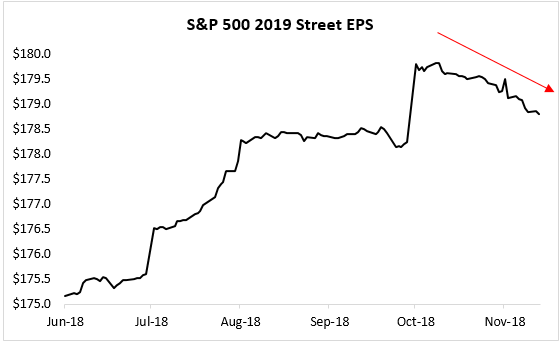
Through and following Q3 earnings, 2019 consensus EPS has been revised lower.

Again, the trend is more worrisome than the dollar amount – thus far – reduced.

Source: Jefferies Trading Desk
Percy Allison vix
Equity Trading, Desk Strategist
Jefferies LLC

Continue reading →

Topley’s Top Ten – November 13, 2018

1.Who Is Going to Buy $1.3 Trillion in New U.S. Government Debt?

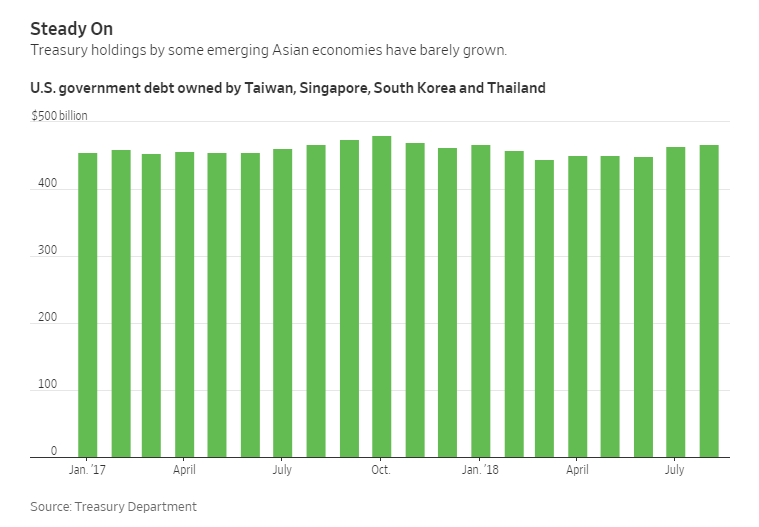
Asian investors are proving less and less eager to buy U.S. government bonds, even as the Treasury Department prepares to sell $1.3 trillion of new debt in the new fiscal year.

Foreigners increased their holdings of Treasurys by $78 billion in the first eight months of this calendar year, according to the Treasury. That is just over half of what they bought in the same period last year.

Holdings have particularly stagnated in a number of emerging Asian economies—including South Korea, Singapore, Thailand and Taiwan—which have prized U.S. government debt as a capital bulwark since the 1997 Asian currency crisis.

Many observers assume the U.S. has no trouble finding demand for its debt in the vast pool of world-wide governments, financial institutions, mutual funds and individual investors who want to own the world’s major risk-free asset. Yet the Treasury is finding fewer buyers in some parts of the world, leaving domestic investors such as mutual funds to pick up the slack.

Where to Find Treasury Buyers? Not Asia

The erosion of demand in emerging Asian markets reflects their maturation into more stable economies

https://www.wsj.com/articles/where-to-find-treasury-buyers-not-asia-1541422801?reflink=e2twmkts.\

Continue reading →

Topley’s Top Ten – November 12, 2018

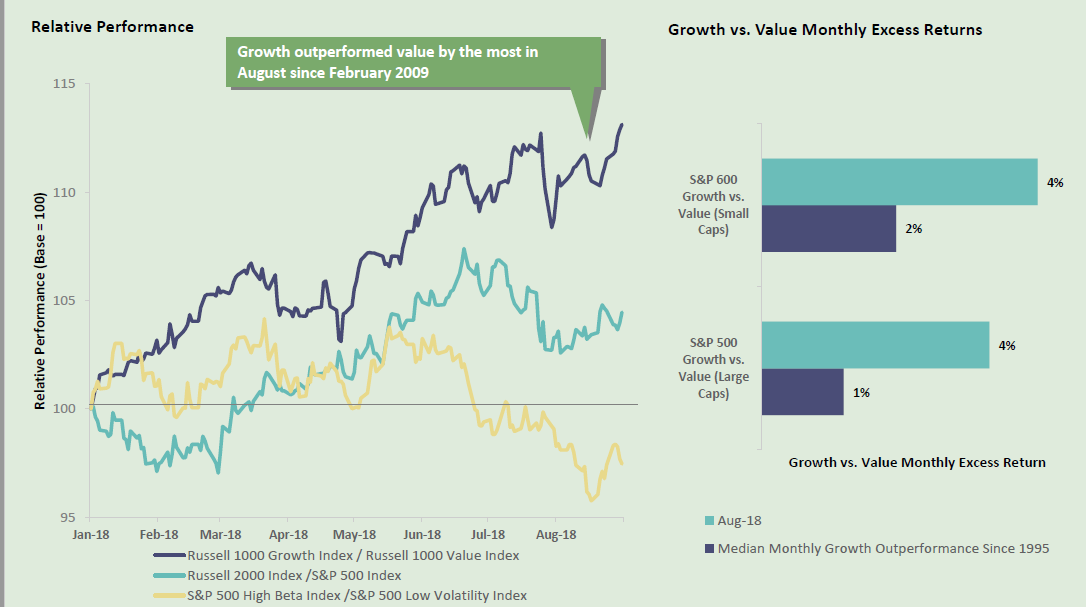
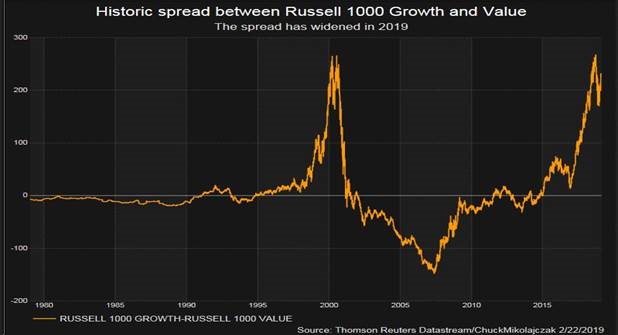
1.Growth Continues To Crush Value This Year For US Equity Factors

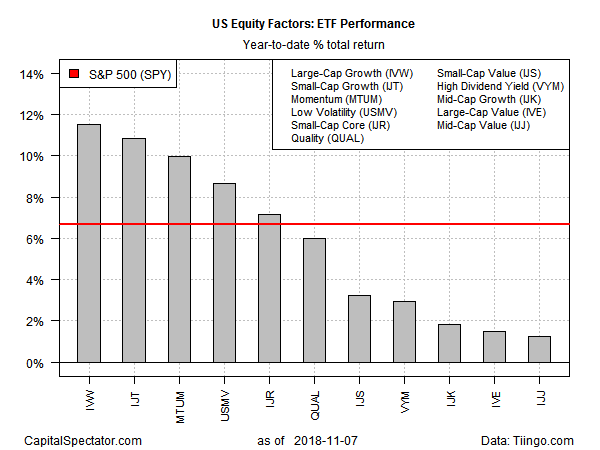
The sharp swings in the stock market in recent weeks haven’t dented the year-to-date performance edge that’s prevailed for large- and small-cap growth stocks in the US over their value counterparts, based on a set of exchange-traded funds through yesterday’s close (Nov. 7).

Large-cap growth still holds the lead for The Capital Spectator’s set of US equity factor ETFs so far in 2018. The iShares S&P 500 Growth (IVW) is up a strong 11.5% year to date. Running slightly behind in second place is iShares S&P Small-Cap 600 Growth (IJT), which is ahead by 10.9% so far in 2018.

Value, by comparison, is far behind in this year’s equity factor horse race. Dead last for year-to-date results at the moment: iShares S&P Mid-Cap 400 Value (IJJ), currently posting a slight 1.3 gain. The second-weakest performance this year: iShares S&P 500 Value (IVE), which is ahead by 1.5%.

Meanwhile, the broad market this year is up 6.7%, based on the SPDR S&P 500 (SPY).

The Capital Spectator
https://www.capitalspectator.com/growth-continues-to-crush-value-this-year-for-us-equity-factors/

Continue reading →

Topley’s Top Ten – November 5, 2018

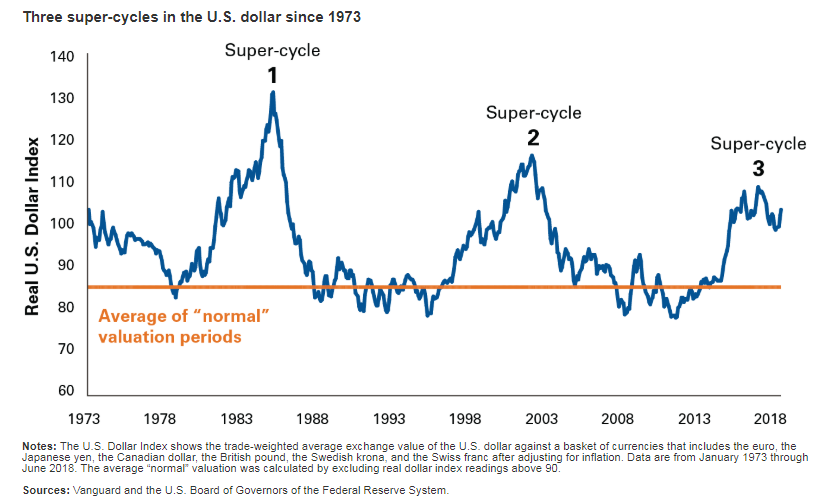
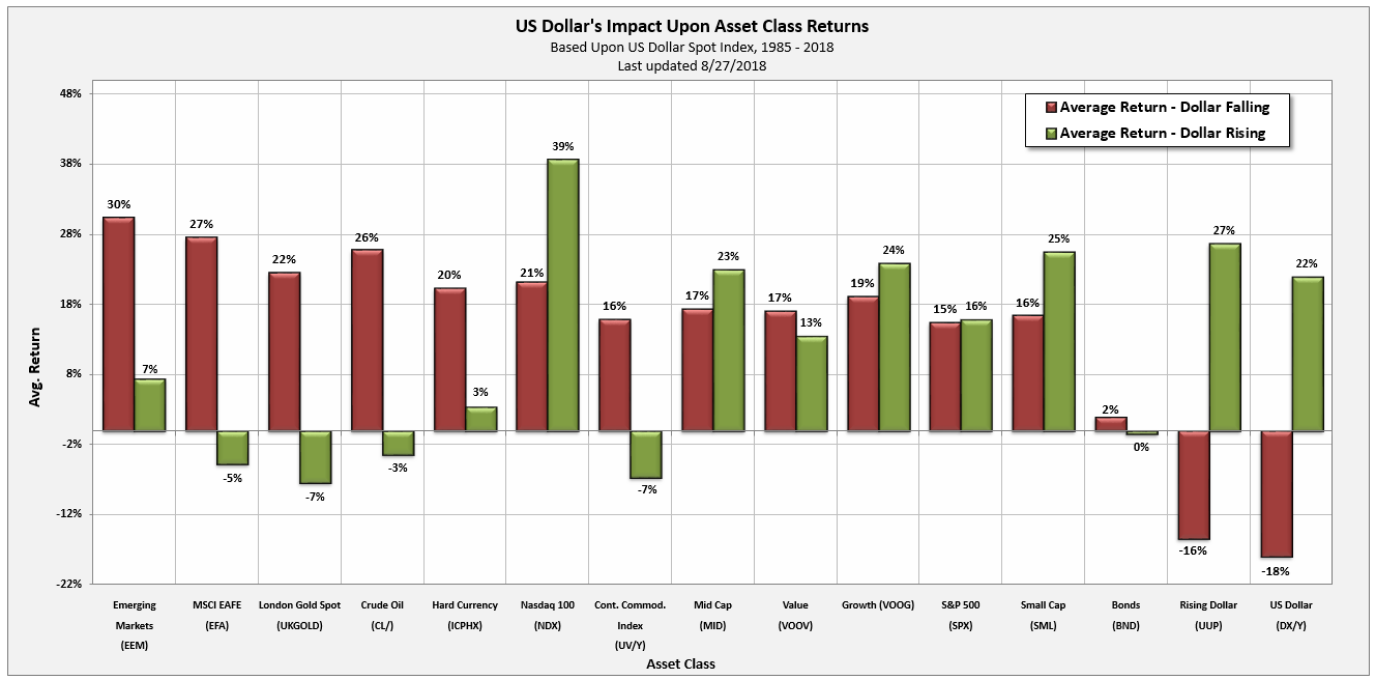
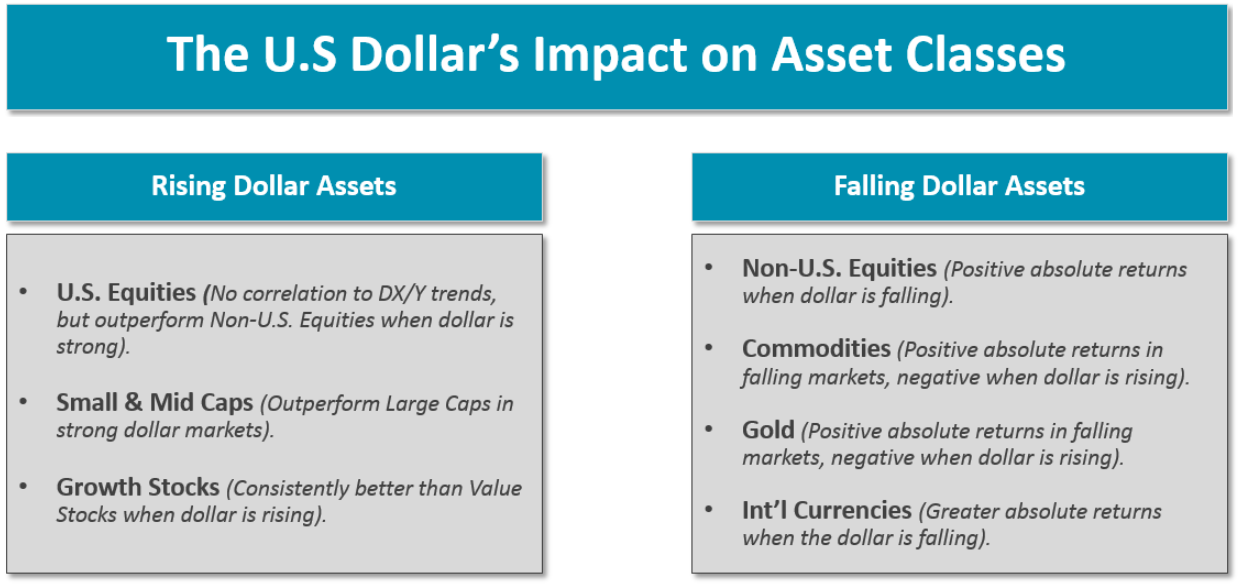
1.We are in Third Dollar Super Cycle Since 1973

Vanguard.

If past is prologue, the dollar will weaken

We can therefore expect the dollar super-cycle to come to a close over the next few years. Here are 4 fundamental factors, not mutually exclusive, that I’ll be watching for:

  1. Narrower growth differentials between the U.S. and other countries.The U.S. economy is much further along in the business cycle than other developed markets are, its labor market is much tighter, and inflation is much closer to the central bank’s target, which in the U.S. is 2%. Since economic growth normally slows late in the cycle, current growth differentials between the U.S. and other economies are expected to shrink. The next slowdown in the U.S. may be exacerbated when the recent fiscal stimulus wears off. We estimate that the stimulus, injected through the tax cuts and spending bill enacted at the beginning of the year, will deliver an extra push to U.S. economic growth of about 40 basis points this year and next.
  2. Higher U.S. bond yields, but narrowing interest rate differentials. Higher bond yields in the U.S. today imply depreciation in the U.S. dollar relative to other major currencies in the future. This market expectation may come to pass in the current global monetary cycle as the gap in rates between the U.S. and other major markets narrows. The Fed may stop raising rates as soon as 2019 while other central banks (notably the European Central Bank and the Bank of England) continue to play catch-up.
  3. Higher inflation in the U.S.Higher inflation in the U.S. relative to other developed markets could put downward pressure on the nominal U.S. dollar exchange rate.
  4. A larger U.S. trade deficit.For all the noise about tariffs and trade deficits, the natural way for trade imbalances to correct over time is through market-driven currency adjustments. Widening U.S. trade deficits translate into higher demand for foreign currency (to pay for the additional imports), which exerts downward pressure on the dollar. The trade deficits themselves are caused in part by rising government budget  shortfalls, which spill over to more foreign purchases of U.S. debt, and in part by strong U.S. consumer spending, which, bolstered by tax cuts, results in more purchases of imported goods, given that they constitute about 18% of the typical consumer basket.

What’s behind the latest surge in the dollar?Roger Aliaga-Diaz

https://vanguardblog.com/2018/09/04/whats-behind-the-latest-surge-in-the-dollar/

Continue reading →

Topley’s Top Ten – October 29, 2018

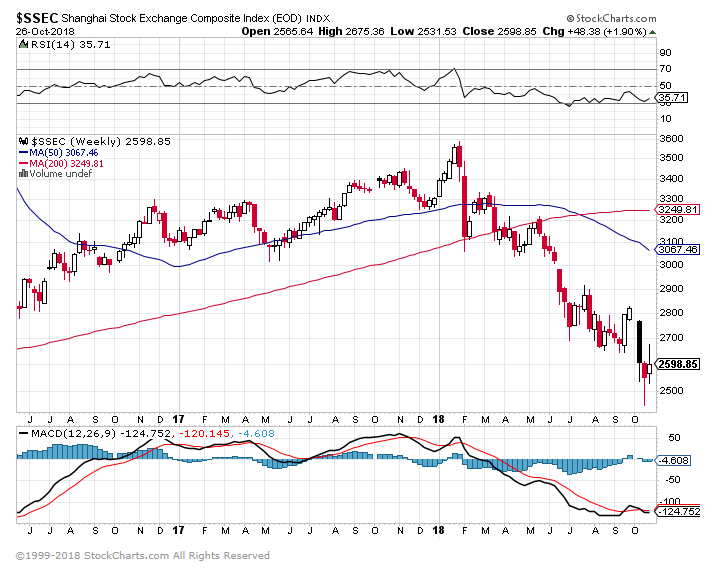
1.Shanghai Composite Down $3 Trillion in Market Cap…Back to 2008 Levels.

China’s economy has grown in size 34.5 times, or an average of 9.5% a year, in the 40 years since the nation started producing modern economic statistics. It has never experienced a year of economic decline.
https://www.barrons.com/articles/the-tariff-battle-wont-dent-chinas-economy-or-americas-1540588257

Shanghai Stock Exchange Composite Back to 2008 Levels.

www.stockcharts.com

Continue reading →

Topley’s Top Ten – October 19, 2018

1.Great Read on Bond Bear Markets.

The Worst Kind of Bear Market

Posted October 16, 2018 by Ben Carlson

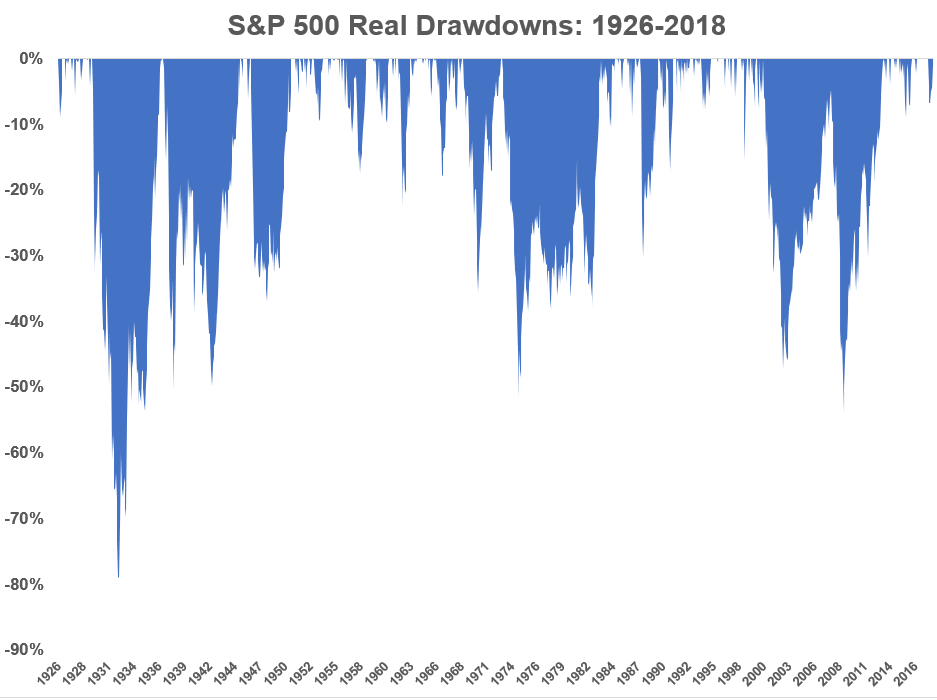
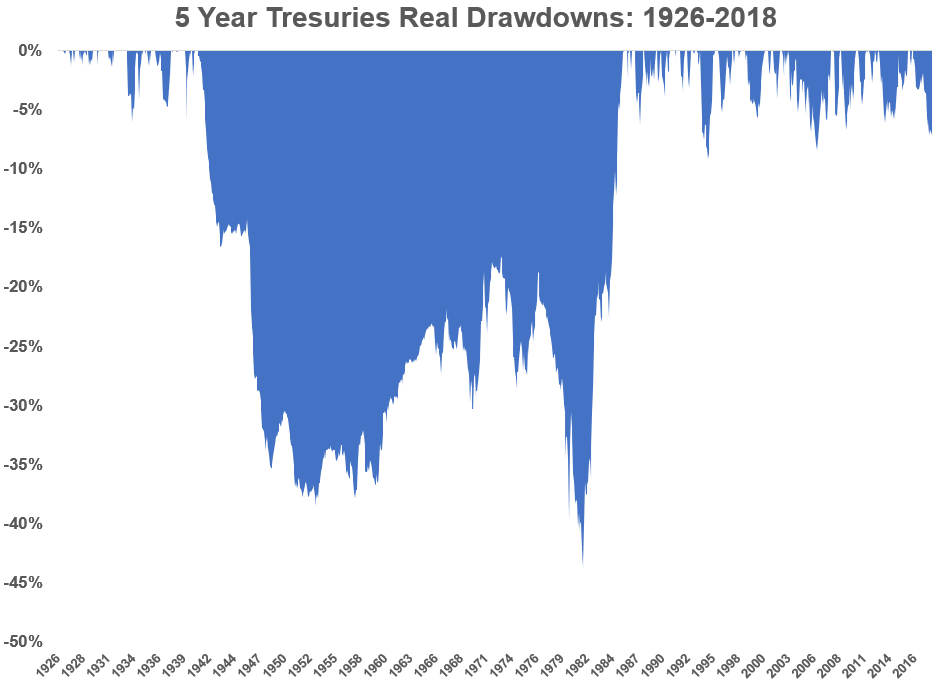
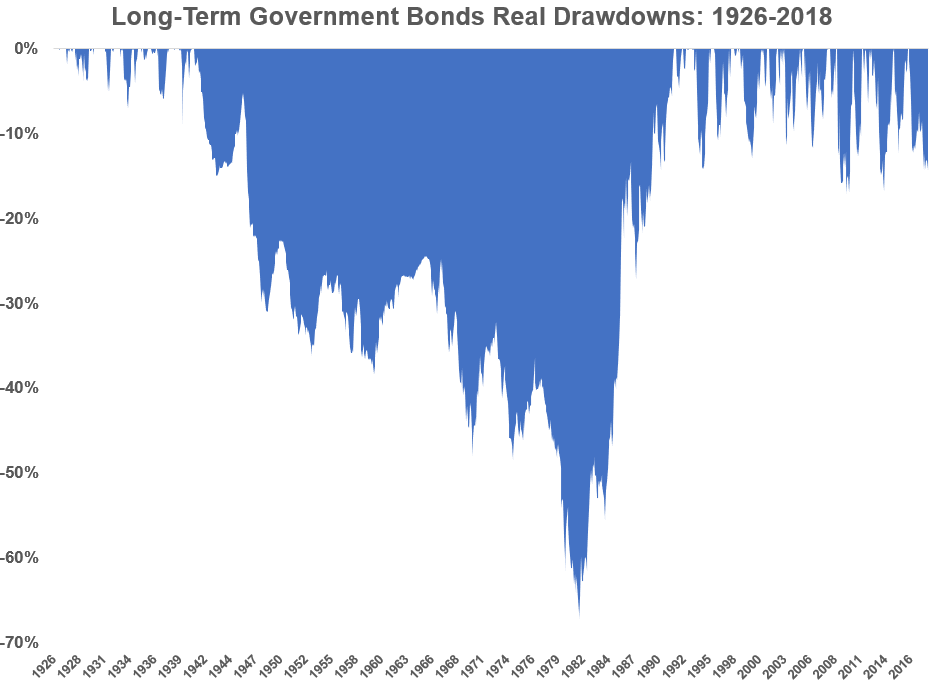
On a recent episode of his show, Behind the Markets, WisdomTree’s Jeremy Schwartz made a comment about a stat from one of Jeremy Seigel’s books. He discussed how in real terms, bonds in the U.S. have actually experienced a much longer bear market than anything witnessed in the stock market.

This makes sense when you realize the biggest risk for stock market investors is generally a crash while the biggest risk for bond market investors is sky-high inflation.

I decided to run the numbers to put some more meat on the bones of this one to gauge the length of bear markets in both stocks and bonds on an after-inflation basis.

This is the historical real drawdown chart for the S&P 500:

I didn’t know which route to choose for a bond proxy so I decided to look at both 5-year treasuries and long-term treasuries. Here’s the chart for the 5-year bond:

And these were the drawdowns for long-term bonds:

Here’s what the stats look like for the longest bear markets for each since 1926:1

https://awealthofcommonsense.com/2018/10/the-worst-kind-of-bear-market/ Continue reading →

Topley’s Top Ten – October 17, 2018

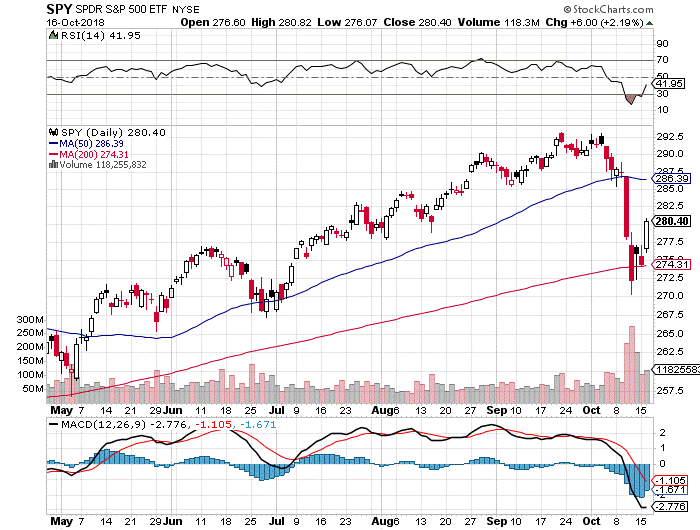
1.S&P Bounces at 200 Day….250 Names Were Down 20% or More in this Correction.

Here are some interesting numbers about the S&P 500, according to data provided by FactSet.

  • Among the S&P 500, 250 stocks were down 20% or more from their all-time closing highs (adjusted for splits and spin-offs) as of the close on Oct. 15.
  • 162 were down at least 30% from their all-time highs.
  • 113 were down at least 40% from their all-time highs.
  • 69 were down at least 50% from their all-time highs.

You may be surprised at how many S&P 500 stocks have fallen at least 50% from record highs

Philip van Doorn

https://www.marketwatch.com/topics/journalists/philip-van-doorn

SPY bounce at 200 day

www.stockcharts.com

  Continue reading →

Topley’s Top Ten – October 15, 2018

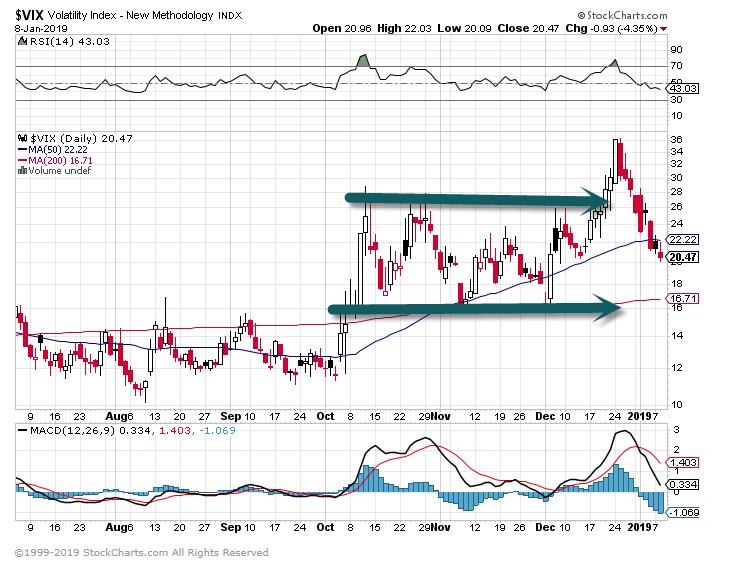
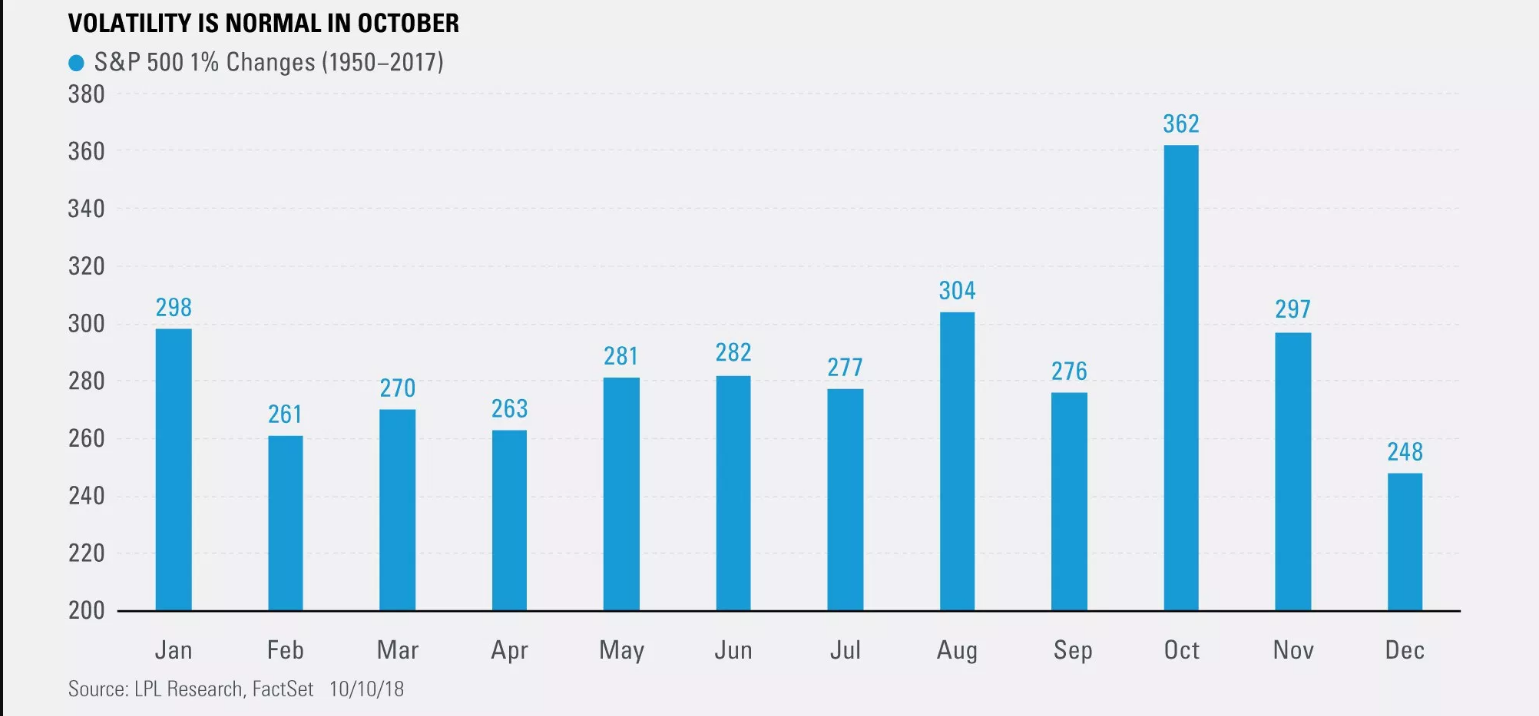
1.Volatility Very Normal in October.

Thoughts on the Market Sell-Off

Posted by lplresearch

  • The S&P 500 Index had one of its least volatile third quarters in history.In fact, it was the first year since 1963 that the index’s usually volatile third quarter didn’t have a single 1% change (up or down). The S&P 500 had gone 74 consecutive days without a 1% move—the 10th longest streak in history. The bottom line is: Equity markets were wound tight and some type of volatility was likely.
  • October has historically had above-average volatility and average returns.October is known for spectacular crashes (1929, 1987, and 2008), but in reality it’s about average in terms of returns. What it really should be known for is volatility. Incredibly, no month has seen more 1% changes (up or down) than the month of October for the S&P 500 going back to 1950.

https://lplresearch.com/2018/10/11/thoughts-on-the-market-sell-off/

Continue reading →

Topley’s Top Ten – October 10, 2018

1.Interesting Comments on Market Breath….Narrow Leadership.

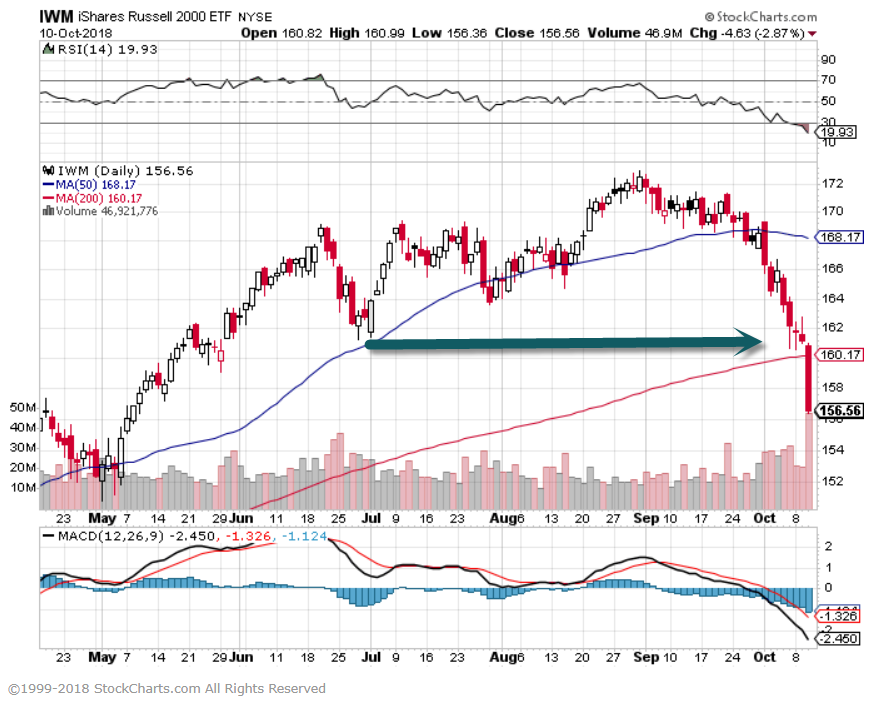
Average Small Cap Stock in “Bear Market” Territory

Oct 9, 2018

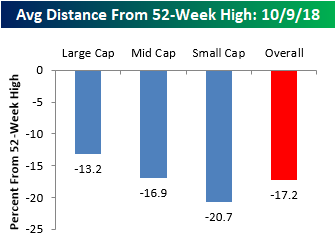
Most people watching have noticed that the recent weakness in equities has been especially tough on the small-cap space, and another illustration of that trend is to look at the distance that stocks are currently trading from their 52-week highs.  Within the large-cap S&P 500, the average stock is currently 13.2% below its 52-week high.  Moving down the market cap spectrum, though, the numbers get progressively worse.  In the S&P 400 mid-cap space, the average spread is 16.9%, while members of the S&P 600 Small Cap index are down an average of 20.7%.  Using the standard bear market definition of a 20% decline from a high, the average small-cap stock is in a bear market!

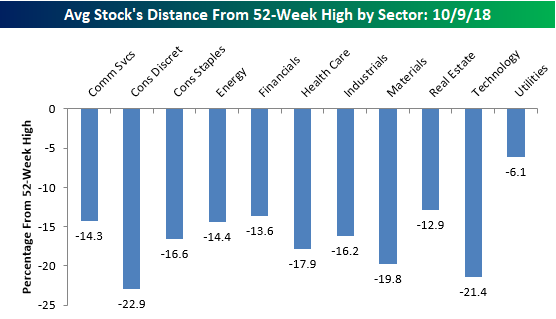
Looking at the spreads between current prices and 52-week highs, stocks in the Consumer Discretionary sector are further from their highs than any other sector (-22.9%), but Technology isn’t far behind at 21.4%.  For two sectors that were market leaders, Tech and Discretionary have certainly seen a good deal of profit-taking lately.  Outside of these two, other sectors where the ‘average’ stock has seen a pretty sizable pullback from its 52-week high include Materials (-19.8%), Health Care (-17.9%), and Consumer Staples (-16.6%).  On the other end of the spectrum, Utilities (-6.1%) is the only sector where stocks are currently down by an average of less than 10% from their 52-week highs.

https://www.bespokepremium.com/think-big-blog/

Continue reading →

Topley’s Top Ten – October 3, 2018

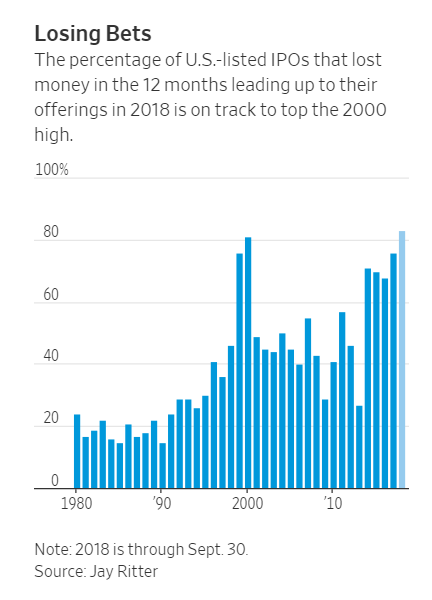
1.More Money Losing IPOs than 2000. 

Stock investors are welcoming money-losing companies into the public markets this year with open arms.

About 83% of U.S.-listed initial public offerings in 2018’s first three quarters involve companies that lost money in the 12 months leading up to their debut, according to data compiled by University of Florida finance professor Jay Ritter. That is the highest proportion on record, according to Mr. Ritter, an IPO expert whose data goes back to 1980.

IPO Market Has Never Been This Forgiving to Money-Losing Firms

Money-losing companies are going public at a record rate as investors hunger for new issues

https://www.wsj.com/articles/red-ink-floods-ipo-market-1538388000?tesla=y

Continue reading →

Topley’s Top Ten – September 27, 2018

1.Nasdaq Up 9 Quarters in a Row…Again

Sep 26, 2018

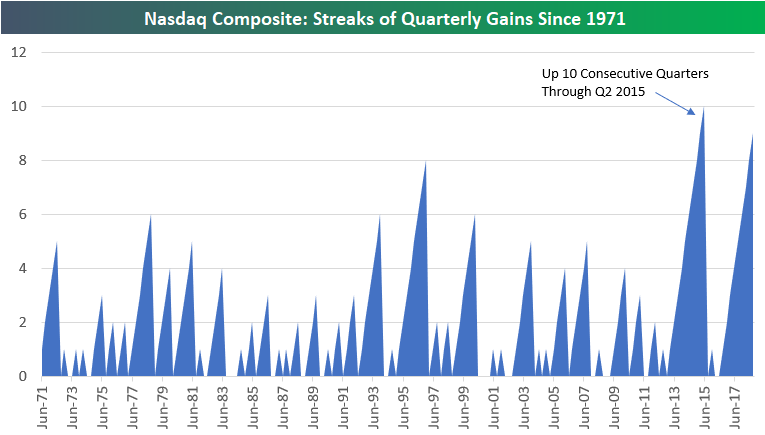
The Nasdaq Composite is set to finish higher for the 9th consecutive quarter when exchanges close this Friday, September 28th.  (With a QTD gain of more than 6%, it would take a dramatic plunge over the next two trading days for the quarter to end in the red.)

Below is a chart showing streaks of quarterly gains for the Nasdaq Composite since its inception in 1971.

Nine quarters of gains is not quite the longest streak on record, and it’s not even the longest streak of the last six years!  The longest stretch of quarterly gains made it to ten from Q1 2013 through Q2 2015.  Prior to that, the record was 8 quarters back in the mid-1990s (Q1 1995 through Q4 1996).  Not even during the Dot Com boom of the late 1990s did we see such consistency of gains for the Nasdaq.

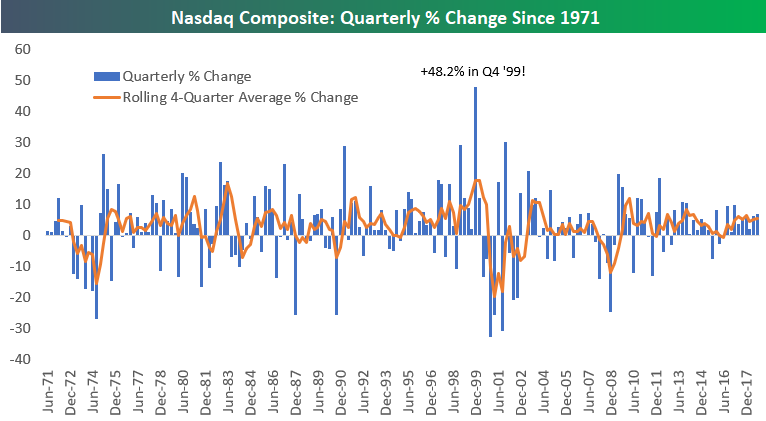
While the Nasdaq has been more consistent to the upside during this bull market than it was during its epic late-1990s rally, the size of the quarterly gains seen this time around don’t come close to matching the rallies seen back then.  In the chart below, we show the quarterly price change for the Nasdaq going back to 1971.  Yes, we’ve seen very nice quarterly gains of 5-10% many times during the current bull, but from 1997 through Q1 2000, the Nasdaq posted seven double-digit quarterly percentage gains, including a gain of 29.5% in Q4 1998 and a ridiculous 48.2% gain in Q4 1999.  This period is nothing like the 1990s.


https://www.bespokepremium.com/think-big-blog/nasdaq-up-9-quarters-in-a-row-again/?utm_source=sumome&utm_medium=linkedin&utm_campaign=sumome_share

Continue reading →
Topley’s Top Ten – September 24, 2018

1.Presidential Cycle Seasonality

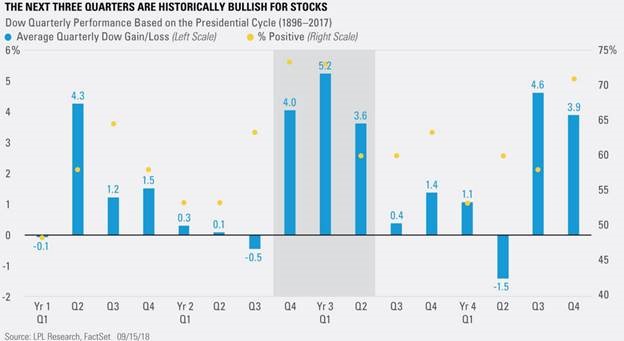
LPL notes the next three quarters are historically some of the strongest out of the entire four-year presidential cycle – “going all the way back to when the Dow started trading in 1896, each of the next two quarters have closed higher 73.3% of the time—no other quarter is up more often. In addition, the average returns over the next three quarters have been 4.0%, 5.2%, and 3.6%—again some of the strongest in the four-year cycle”

From Dave Lutz at Jones.

Continue reading →
Topley’s Top Ten – September 20, 2018

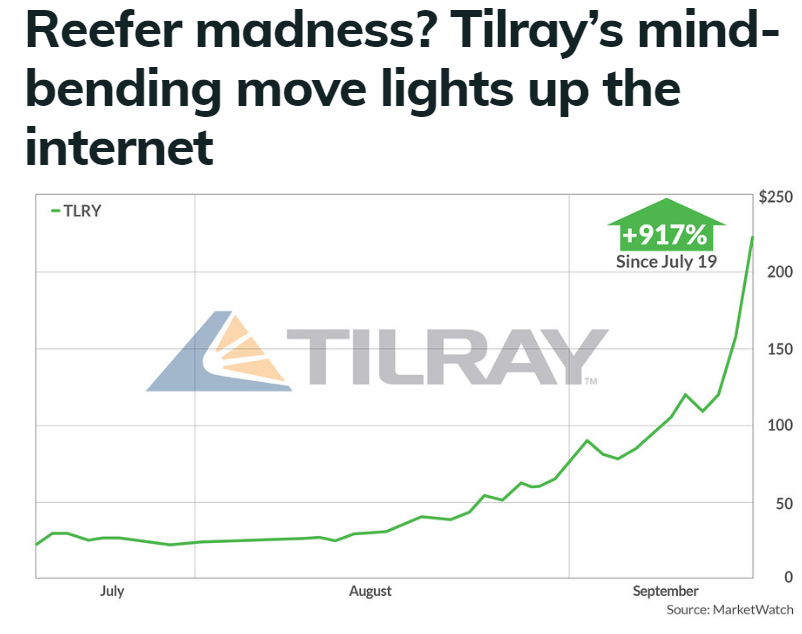
1.Bitcoin Speculators Switch to Weed.

https://www.marketwatch.com/

I Started My Trading Career in 1997 So Witnessed the Internet Bubble First Hand….This is Textbook 1999 CEO Interview on Jim Cramer…Stock Spikes 90% and Gets Held 5 x in One Day….Bigger Market Cap than General Mills

Tilray’s Wild, Wild Day

If you didn’t know about Tilray before, you definitely do now.

Earlier this week, the Canadian marijuana producer earned approval from the U.S. government to import medicinal cannabis into the U.S. for clinical trials. On Tuesday night, Tilray CEO Brendan Kennedy gave a chest-thumping interview to Jim Cramer.

Then, all hell broke loose.

Yesterday, shares skyrocketed ~90% before erasing most of those gains and briefly dipping into the red. Couple notes:

  • The stock was halted from trading five times by Nasdaq due to volatility.
  • It ended up 38% for its best day yet as a public company.

Clearly, Tilray has the munchies

During its mega-surge, Tilray at one point yesterday had gobbled up the market cap of food conglomerate General Mills.

Bottom line: Tilray finished the trading day bigger than American Airlines and Clorox, with a market cap close to $20 billion. Look out, Apple. Someone’s coming for that $1 trillion crown.

https://www.morningbrew.com/

Continue reading →
Topley’s Top Ten – September 18, 2018 (Short Version)

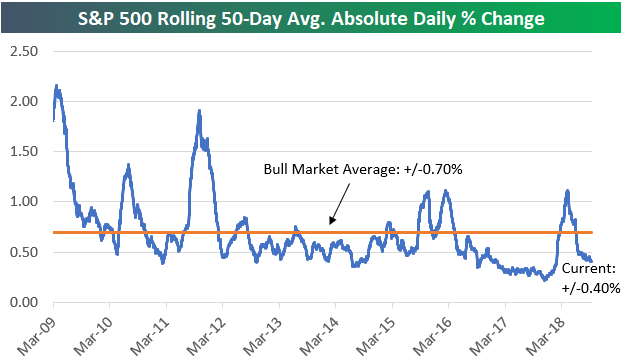
1.Zero Volatility in Market.

S&P 500 Average Daily Change Down to +/-0.40%

Sep 17, 2018

2017 was one of the least volatile years ever for the US equity market.  The S&P 500 averaged an absolute daily change of just 0.30% last year.

Due to a pick-up in volatility during the S&P’s correction in the first quarter, the average absolute daily change for the index is more elevated this year at +/-0.64%, but more recently we’ve seen a pretty big drop in the action.  As shown in the chart below, the S&P has averaged an absolute change of just +/-0.40% over the last 50 trading days, which is well below the average of 0.70% seen throughout the current bull market.

From a seasonal perspective, September and October have historically been the most volatile months of the trading year, but so far this September, the S&P has averaged a daily move of less than 0.24%.  It’s starting to feel like 2017 all over again!

https://www.bespokepremium.com/think-big-blog/

Continue reading →
Topley’s Top Ten – September 7, 2018

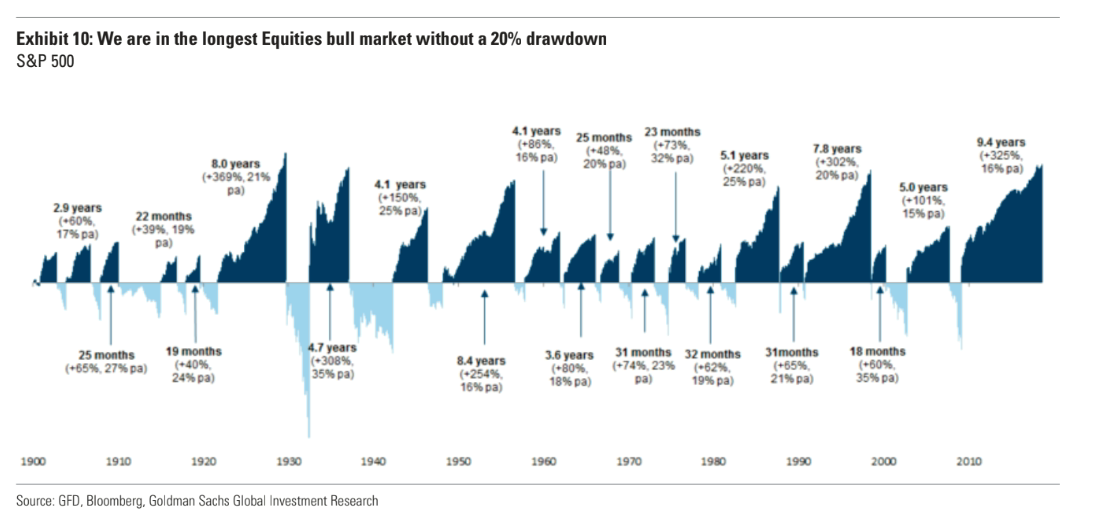
1.Longest Equity Bull Ever Without 20% Correction.

A 20% decline for the market, representing the typical definition of a bear market for an asset, hasn’t occurred in years (see chart below), according to Goldman, and may be halting for investors that have grown accustomed to this current phase of mostly levitating markets.

A stock-market bear signal is at a more-than-4-decade high, says Goldman
Mark DeCambre
https://www.marketwatch.com/story/a-stock-market-bear-signal-is-at-a-more-than-4-decade-high-says-goldman-2018-09-06

Continue reading →
Topley’s Top Ten – September 4, 2018

1.Momentum Continues to Lead…Winners Keep Winning.

August a Continuation of Trend

Aug 31, 2018

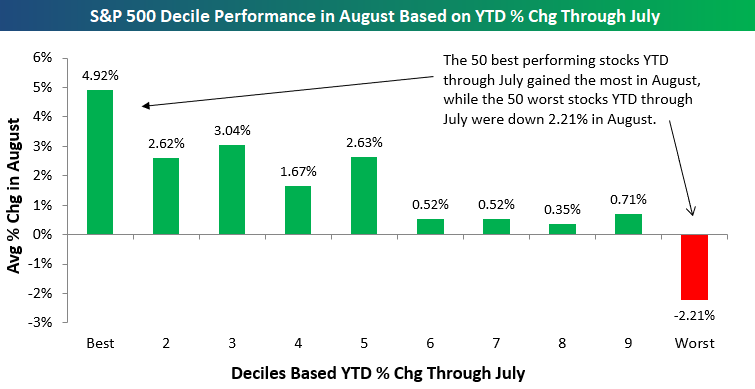
Below we show our decile analysis of S&P 500 gains in August. To construct these analyses, we show how each 10% bucket of stocks in the S&P 500 (50 per bucket) by a given metric performs. In this example, we’ve broken the S&P 500 into deciles based on their percentage change in the first 7 months of the year through July. Over the course of August, performance in the other 7 months was highly correlated to performance this month. As shown in the chart below, the 50 best performing stocks YTD through July were up almost 5% in August, with the 2nd through 5th deciles also performing quite well. The bottom half of the market in terms of YTD performance through July generally didn’t do as well in August. That was most true for the 50 stocks that performed the worst through July, which dropped on average 2.2% in the month of August. Owning winners is often derided by contrarians as a way to underperform, but the decile analysis below is one example of momentum begetting more momentum in financial markets.

https://www.bespokepremium.com/think-big-blog/

Continue reading →
Topley’s Top Ten – August 28, 2018

1.New Highs are Bullish and Long Waits Between New Highs More Bullish.

Finally

Posted by lplresearch

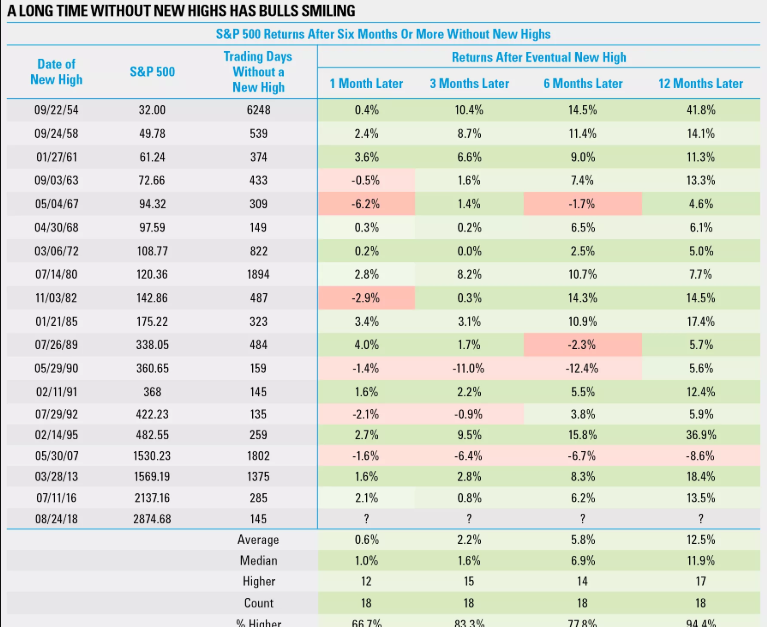
It took nearly seven months, but the S&P 500 Index finally closed at a new all-time high on Friday. Many clues along the way suggested new highs could eventually come, like strong overall market breadth and excellent earnings growth. Still, the big question now is, what happens next?

“Investors have been patiently waiting for new highs in the S&P 500, even while small caps and technology have been making new highs for months now. Here’s the good news: When the S&P 500 has gone at least six months without a new high, the index has been higher a year after the next new high in 17 out of the past 18 instances, going back to 1950,” explained Senior Market Strategist Ryan Detrick.

As our LPL Chart of the Day shows, long waits between new highs tend to foreshadow strong outperformance in the subsequent year.

https://lplresearch.com/2018/08/27/finally/#more-10551

Continue reading →
Topley’s Top Ten – August 27, 2018

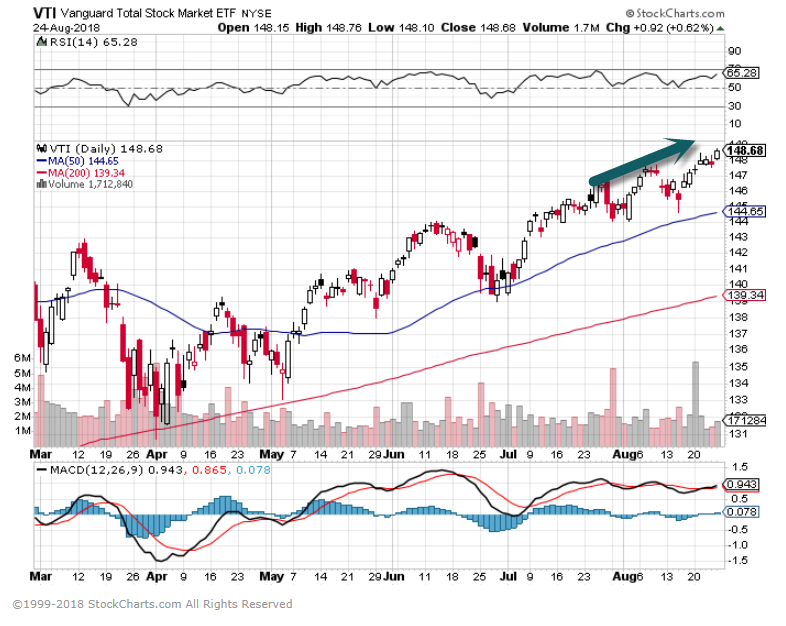
1.Small Mid and Large Hit New Highs..

The Interminable Bull

U.S. Investment Policy Committee Notes
by CFRA

Aug. 22: In a classic example of ignoring the headlines and focusing on the bottom line, investors brushed aside seemingly damaging political outcomes and pushed the S&P 500 not only to a record duration, but also a new intraday, all-time high. The question du jour is now, “How long?”

We think bull markets don’t die of old age, they die of fright and are most afraid of recession. However, we don’t see a recession on the horizon, since the global economy is expected to maintain its upward growth trajectory, interest rates and inflation are projected to stay low, and S&P 500 profits are seen adding 10% in 2019 to the near-23% 2018 growth forecast.

Besides, history shows that after a trifecta of all-time highs for the S&P 500, MidCap 400, and SmallCap 600, the 500 was higher in price by an average of 4.8% six months later and up 77% of the time versus the average gain of 4.5%. During all rolling six-month periods, it was up 73% of the time.

–Sam Stovall

www.stockcharts.com

Continue reading →
Topley’s Top Ten – August 22, 2018

1.Earnings..Highest Beat Rate and Lowest Miss Rate in 5 Years.

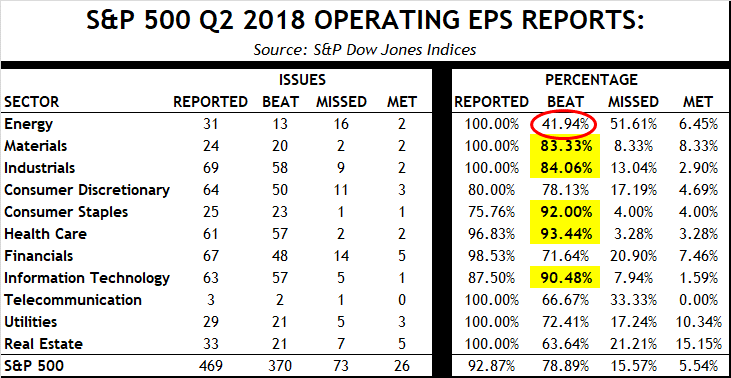
Meanwhile, U.S. based investors continue to benefit from rising corporate earnings.  As of August 16th, 469 of the S&P 500 Index companies have reported Q2 earnings, of which 370 have beaten earnings (78.89%) and only 73 have missed (15.57%) earnings estimates.  In fact, this would be the highest beat rate and lowest miss rate in the past 5 years and well above the averages over the past five years (69.25% Beat rate and 21.51% Miss Rate).  Also, there are five sectors in which at least 80% of companies has beaten EPS estimates thus far.


Bluestone
Rich Farr, Chief Market Strategist
http://www.bluestonecm.com/

Continue reading →
Topley’s Top Ten – August 20, 2018

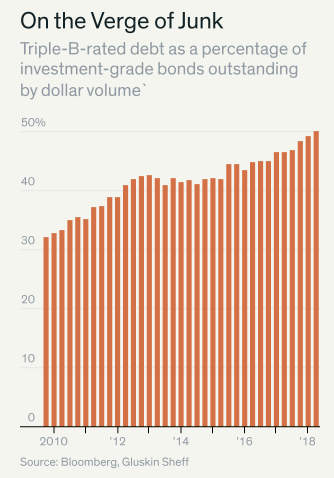
1.Read of the Weekend…$700B BBB Bonds in 2008…$3Trillion 2018

Barrons

Ray Kennedy, a high-yield portfolio manager at Hotchkis & Wiley, notes that when BBB debt—more than twice the size of the $1.2 trillion in junk debt—falls, the high-yield market expands. Some investors, such as certain insurance companies, aren’t allowed to hold junk and will become “forced sellers,” he says, intensifying the downdraft. Only 10% of the junk market is composed of bonds that originally were investment-grade but later were downgraded to junk. That’s far below the median of 15.5% and the historical peak of 32% in 2002-03. So, a large influx of fallen angels would be far from unprecedented.

In a crunch, investors trying to go up the ratings scale would “have a limited pool of choices,” warns Joseph Kalish, chief global macro strategist at Ned Davis Research Group. Higher-quality credits, such as AA or AAA-rated bonds are now just some 10% of the investment-grade universe, versus 20% to 25% in 1999-2000, he says. Investors could turn to U.S. Treasuries but would have to give up over one percentage point of yield. That’s significant in the fixed-income world.

Where the Bond Market’s Next Big Problem Could Start

By
Vito J. Racanelli
https://www.barrons.com/articles/where-the-bond-markets-next-big-problem-could-start-1534536183

Continue reading →
Topley’s Top Ten – August 13, 2018

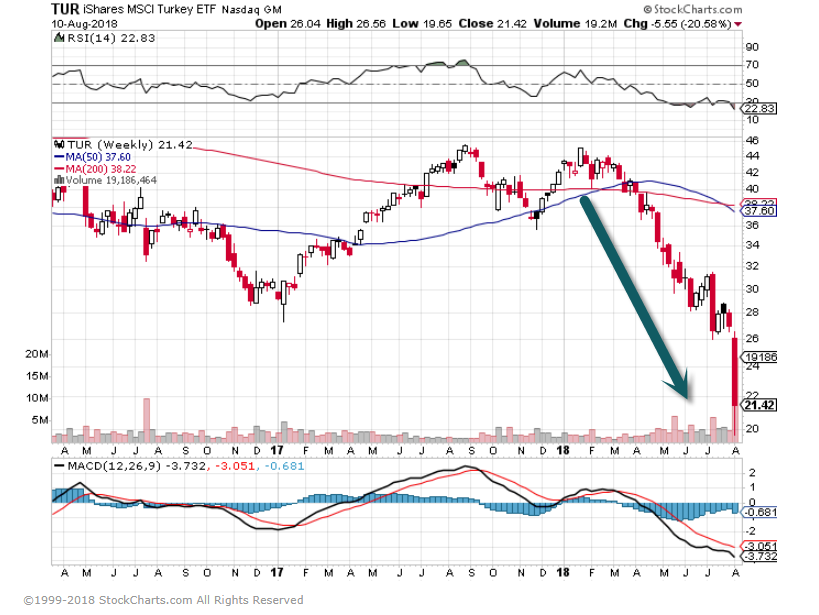
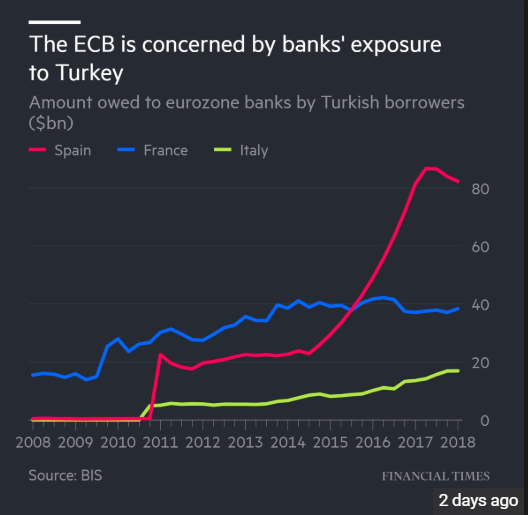
1.Turkey ETF -40% YTD

The roots of Turkey’s travails are no mystery. Erdogan pumped a congenitally volatile economy full of steroids in the election run-up, restraining interest rates and pushing a large guaranteed loan program through the banks. That jolted gross domestic product growth north of 7%, but fueled a vertiginous current-account deficit at 6% of GDP. Stress is focused on the banking system, whose clients owe $180 billion in short-term foreign-currency debt, figures Timothy Ash, senior emerging markets sovereign strategist at BlueBay Asset Management. That gets more expensive in lira by the day. “Turkey’s Achilles’ heel is that its banking system is used to intermediate large-scale foreign-currency borrowing,” says Robin Brooks, chief economist at the Institute for International Finance in Washington.

Erdogan compounded his problems by stumbling into conflict with President Donald Trump’s administration over Andrew Brunson, a U.S.-born, Turkey-based Protestant pastor arrested two years ago on charges of colluding with Kurdish terrorists.

Turkey Pays a Financial Price for Its Politics

By
Craig Mellow
https://www.barrons.com/articles/turkey-pays-a-financial-price-for-its-politics-1533916009


Continue reading →
Topley’s Top Ten – August 9, 2018

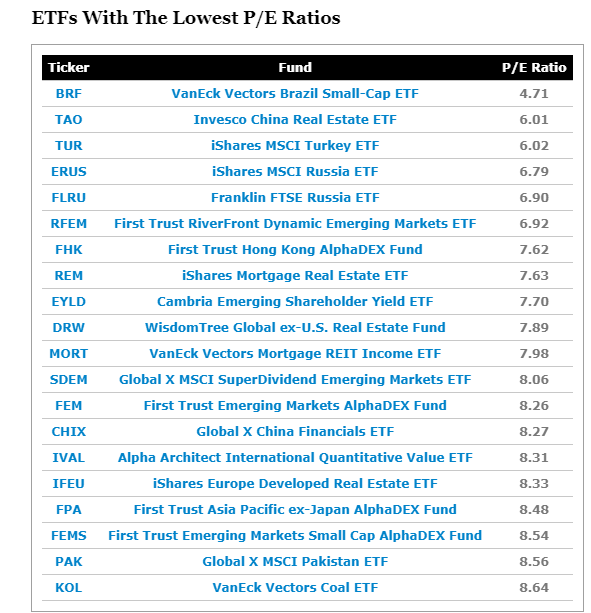
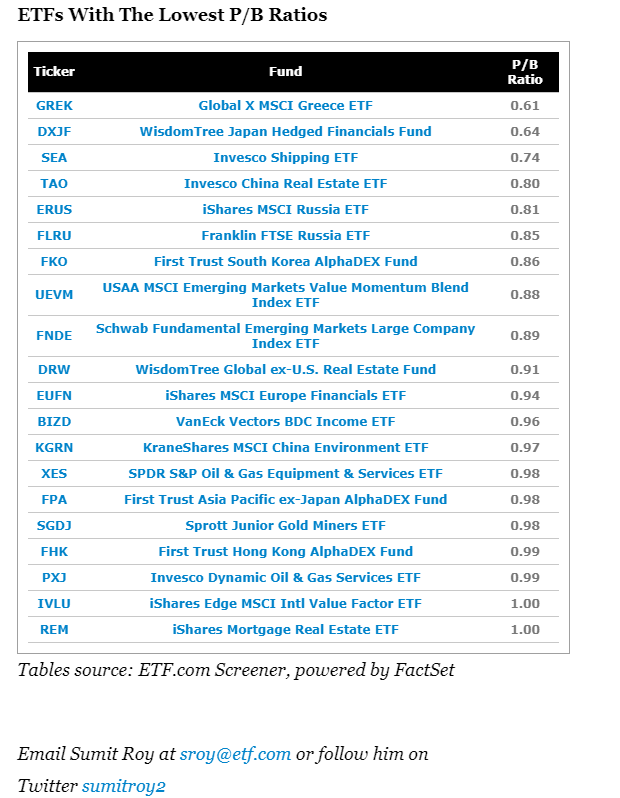
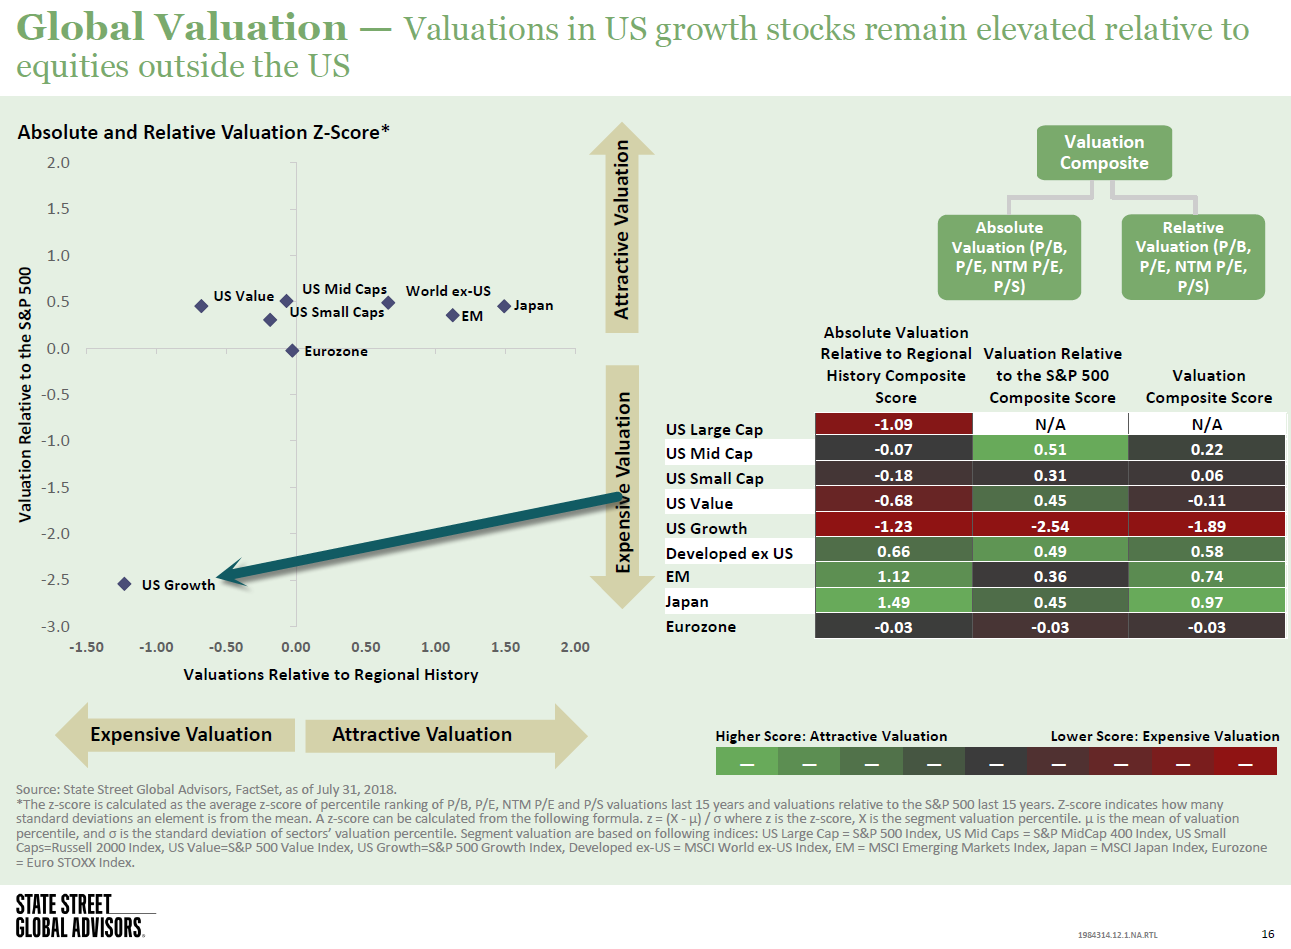
1. ETFs With The Lowest Valuations

Bargains Abroad

Instead, most of the bargains are found in ETFs that focus on equities outside the U.S. Of the 20 cheapest funds by valuation, the vast majority target international equities, and emerging market stocks in particular.

Of course, an ETF with a low P/E ratio doesn’t necessarily mean it’s a great investment. It simply means most of the stocks in the fund are trading at low prices compared to their recent earnings.

It’s a good starting point for value investors, but it’s just the first step in a more comprehensive due diligence process.

https://www.etf.com/sections/features-and-news/etfs-lowest-valuations?nopaging=1

Continue reading →
Topley’s Top Ten, Short Version – August 8, 2018

Sorry to all Subscribers – we experienced some technical difficulties during the past week.  All notifications and posts will now resume as normal.


Thank you!
View From the Top Team


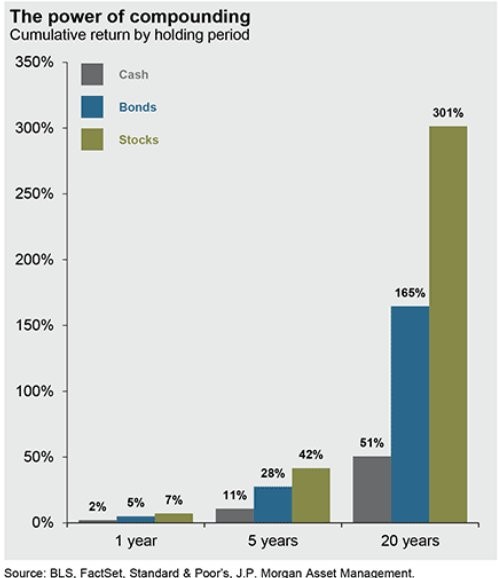
1.The Power of Compounding….Holding through 2 Massive Bear Markets.

In the past 20 years, equity investors have suffered through the two largest bear markets since the 1930’s yet ended up 300% ahead

https://twitter.com/ukarlewitz

Continue reading →
Topley’s Top Ten – August 3, 2018

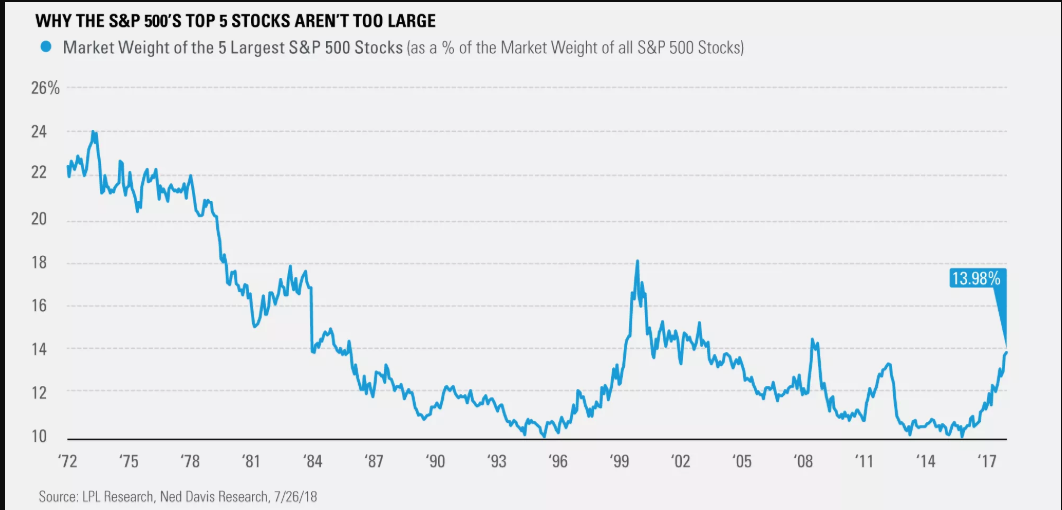
1.Current Weight of Top 5 Stocks in S&P Actually Lower Than Long-Term Average.

Counter Argument to 5 Stocks Providing Most of the Performance

Are Only a Few Stocks Really Leading Us Higher?

Posted by lplresearch

One of the more popular narratives we’ve heard this year is that only a few large stocks are pulling the overall market higher. We don’t agree with this assessment, and have cited several metrics over the last few months that showed market participation has been broad and eventual new highs in the S&P 500 Index were likely. Remember, when more stocks are moving higher, the bull market’s momentum increases.

Below are a few reasons why we still see broad participation and a continuation of the bull market:

  • The Advance/Decline (A/D) lines for the NYSE and S&P 500 both closed at all-time highs last week.
  • The Dow A/D line made new highs earlier this week.
  • The Value Line Geometric Index is less than 2% from its all-time high. This index equally weights all stocks and is a good gauge for how the median stock is performing.
  • The Technology Equal Weight Index made a new high last week.
  • The Nasdaq 100 Equal Weight Index made a new all-time high last week.

“The one constant that has suggested higher equity prices this year has been market breadth. Tariffs, tweets, and rate worries might be in the headlines, but we’ve been comforted by the fact that many market measures of breadth have suggested eventual new highs and we are happy to report this is still the case today,” explained LPL Research Senior Market Strategist Ryan Detrick.

There has been a lot of news coverage around the five largest companies now being worth more than the bottom 250 in the S&P 500. Thanks to data from our friends at Ned Davis Research (NDR), the top five stocks in the S&P 500 account now for 13.98% of the total index. As our LPL Chart of the Day shows, the current weight of the top five stocks is actually beneath the average of 14.33% using NDR’s data going back to 1972.

This is another sign that investors should ignore the narrative that only a few stocks are leading us higher and that the market is doomed.

https://lplresearch.com/

Continue reading →
Topley’s Top Ten – July 31, 2018

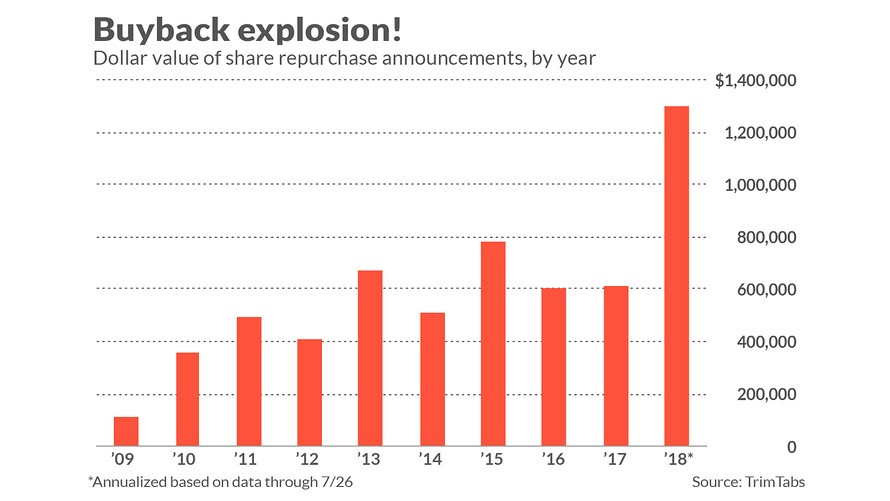
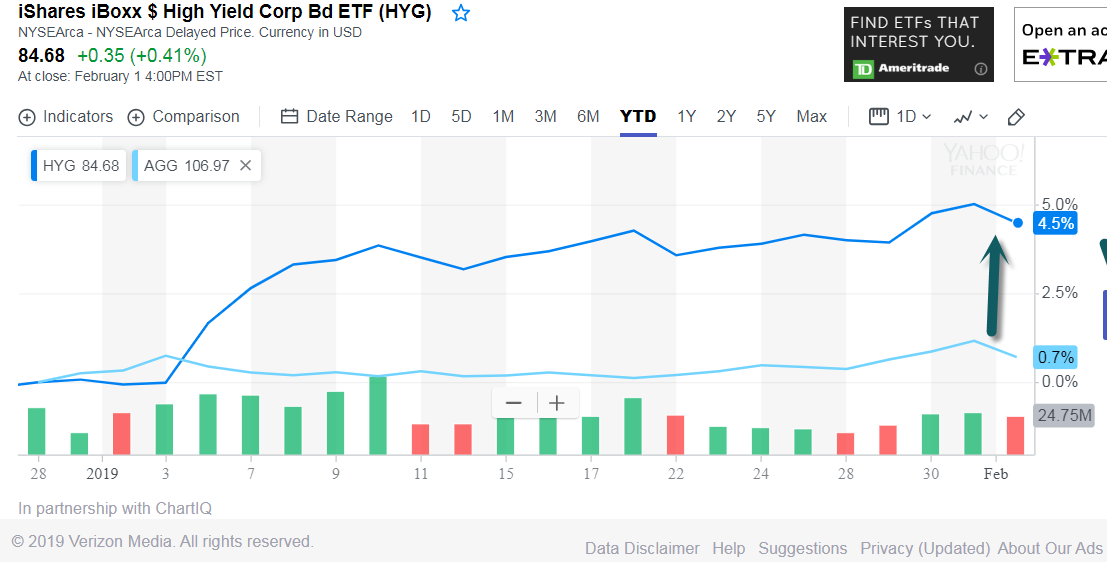
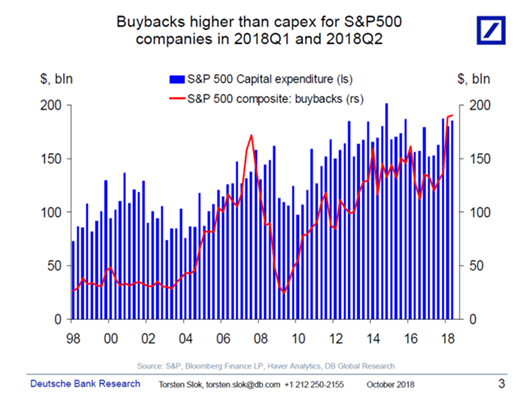
1.As Expected….Buyback Explosion Post Tax Cut.

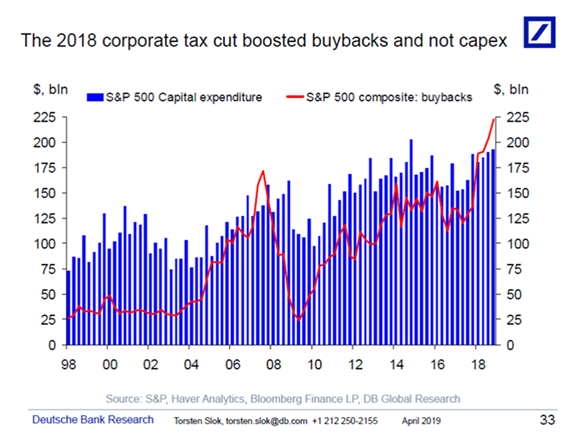
You will notice that this new quarterly record was nearly double that previous one. Corporations aren’t just gradually ramping up their repurchases; they’re falling over themselves to do so.

But is total buyback activity a good stock market indicator? In the 1980s and 1990s, at least, it was. In those decades, a number of academic studies found, the stock of the average company that announced a new buyback company proceeded to significantly outperform the market over several years following that announcement.

Since then, the situation has changed. One recent study, for example, found no outperformance from buyback activity over the decade through 2012 — that the stock of the average company announcing a buyback performed no better than the S&P 500 SPX, -0.58%  after that repurchase program was announced.

Opinion: Stock buybacks are no reason to buy a stock

Share repurchases once signaled confidence, but now just substitute for dividends

https://www.marketwatch.com/story/stock-buybacks-are-no-reason-to-buy-a-stock-2018-07-31

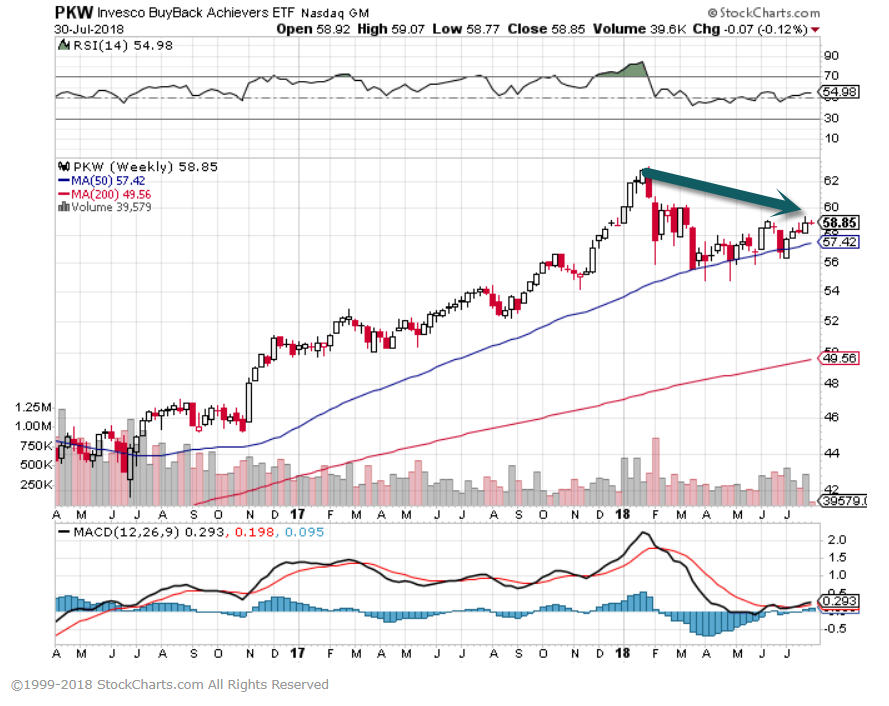
PKW-Buyback ETF Still Below Peaks

www.stockcharts.com

Continue reading →
Topley’s Top Ten – July 23, 2018

There will only be a couple Top 10’s this week due to vacation

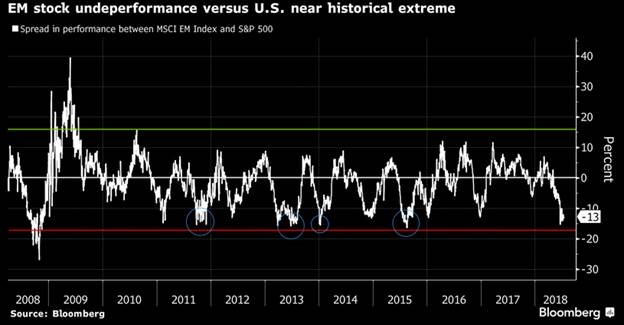
1.Emerging Markets Stock Underperformance Versus U.S. Near Historical Extremes.
Goldman, BlackRock and Franklin Templeton all say now’s the time to buy emerging markets – “The performance of emerging-market equities relative to U.S. large caps, as measured by the spread of rolling three-month returns, is near a threshold of -17 percent, which hasn’t been breached since the global financial crisis”
From Dave Lutz at Jones Trading

Continue reading →